Bitget UEX Daily Report | The three major U.S. stock indices closed lower; bank earnings reports showed mixed performance; AI chip stocks continued to be under pressure (October 14, 2026)
 Core Viewpoint

 Bitget UEX Daily Report
# 1. Selected Hot News
1. U.S. Banking Sector: Goldman Sachs Profit Grows 29%, JPMorgan Trading Business Remains Strong
On October 13, major U.S. banks released their third-quarter earnings reports. Goldman Sachs reported a net profit increase of 29% year-on-year to $5.29 billion, with revenue up 23% year-on-year to $18.68 billion, driven by a 72% increase in stock trading income. JPMorgan's revenue grew 8% to $50.17 billion, with market business revenue up 15% and stock trading income up 49%, although some investment losses affected overall profit performance.
Citigroup's third-quarter profit rose 40% to $5.2 billion, with revenue reaching $23.8 billion. Wells Fargo's profit increased 6% to $5.95 billion, but revenue performance fell short of market expectations. Overall, the trading business of large banks remains resilient, while investment banking is impacted by market volatility and the financing environment.
Market Impact: The bank earnings reports indicate that the U.S. financial system has not yet experienced a comprehensive credit deterioration, with stock trading and wealth management still generating income. However, the high growth in trading income may not be sustainable, as bond market volatility, high interest rates, and a slowdown in M&A activity could affect future profitability. Attention should now turn to net interest income, loan loss provisions, and corporate financing demand.
2. AI Industry: Semiconductor Sector Continues to Adjust, China's Storage Technology Progress Raises Competitive Concerns
On October 13, U.S. chip stocks continued to adjust, with the market focusing on the technological advancements of Chinese storage company Changxin Storage (CXMT) and its potential impact on the global storage industry competitive landscape. The previous day, related news had already triggered declines in storage stocks like Micron. Meanwhile, investors are still assessing whether the massive capital expenditures in AI infrastructure can continue to translate into profits.
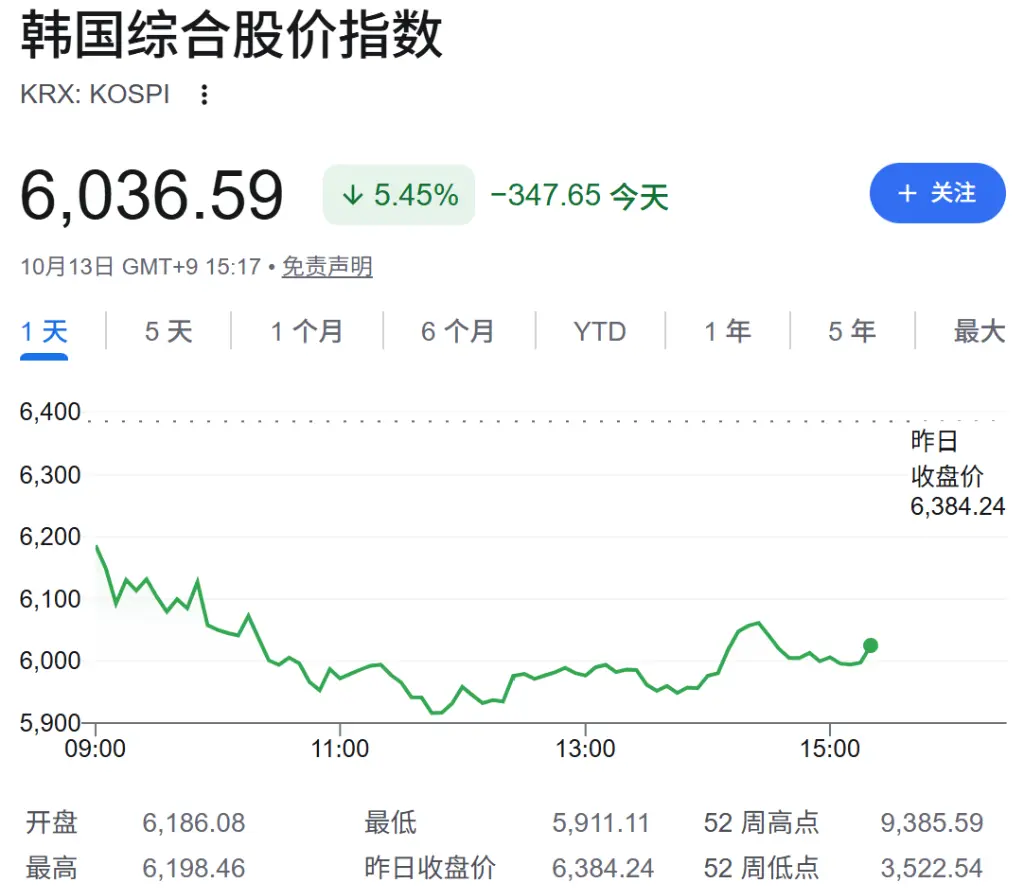
The Asian semiconductor market is also under pressure, with the South Korean stock market experiencing significant declines, and storage-related companies like Samsung Electronics and SK Hynix drawing attention. Market concerns are not only about the growth rate of AI demand but also about future supply competition and the industry's profit cycle.
Market Impact: The continuous growth in AI computing power demand does not mean that all semiconductor companies can maintain high profit margins in the long term. Storage chips exhibit clear supply-demand cycle characteristics, and new manufacturing technologies may affect future cost and capacity competition. However, technological R&D progress does not equate to achieving large-scale mass production, and investors still need to focus on actual shipments, price changes, and corporate gross margins.
3. U.S. Macroeconomics: Oil Prices Retreat, U.S. Treasury Yields Decline, Market Awaits CPI
On October 13, international oil prices retreated from previous highs, and U.S. Treasury yields fell in tandem. Despite some easing of energy and interest rate pressures, U.S. stocks still experienced slight declines due to weakness in the semiconductor sector and mixed bank earnings reports. The S&P 500 index closed at 7,805.45 points, not far from its previous high.
The U.S. Consumer Price Index (CPI) for September will be released on October 14 at 20:30 Beijing time. Previously, rising consumer inflation expectations and persistently high international oil prices have made the market more concerned about whether energy prices are being transmitted to other goods and services.
Market Impact: If the CPI shows that inflation pressures continue to expand, the market may readjust expectations for future Federal Reserve rate hikes and suppress growth stock valuations. If core inflation remains moderate, it may alleviate pressure on bond yields. Given that bank earnings reports indicate that U.S. consumer spending remains resilient, market judgments on economic growth and inflation may continue to diverge.
# 2. Market Review
1. Performance of Major U.S. Stock Indices
Index
Closing on October 13
Change
Dow Jones Industrial Average | 51,670.10 | -0.35%
S&P 500 Index | 7,805.45 | -0.02%
NASDAQ Composite Index | 27,204.38 | -0.15%
Russell 2000 Index | 2,783.37 | -0.40%
All three major U.S. stock indices closed lower on October 13, but the declines in the S&P 500 and NASDAQ were limited. The mixed performance of bank earnings and the continued adjustment in chip stocks created major pressure, while the performance of some financial and non-tech companies mitigated the index declines.
From a market structure perspective, the current adjustment is not a comprehensive sell-off of risk assets. The S&P 500 remains at a relatively high level, and the market is awaiting inflation data and more tech company earnings reports to reassess whether profit growth in a high-interest-rate environment can support existing valuations.
2. Commodity and Forex Performance
Commodity
Reference Price
Data Source
Spot Gold | Approximately $4,157.90/ounce | October 13 U.S. trading session
WTI Crude Oil | $94.14/barrel | October 13 futures settlement
Brent Crude Oil | $105.69/barrel | October 13 futures settlement
U.S. 10-Year Treasury Yield | Approximately 5.22% | October 13 U.S. trading session
On October 13, Brent crude oil fell 0.9%, while WTI rose 0.4%, reflecting the tug-of-war between Middle Eastern supply risks and expectations of increased Russian diesel supply. Gold fell by about 0.3%, as the U.S. dollar and high interest rate expectations continued to limit precious metal performance.
3. Cryptocurrency Performance
This time, we did not obtain a timely snapshot of Bitget BTC/USDT and ETH/USDT, so we do not use the prices and 24-hour changes from October 13, nor do we report unverified total cryptocurrency market capitalization.
BTC | Liquidation Zone Observation
We have not obtained a verifiable latest CoinGlass liquidation map, so we cannot confirm the major potential liquidation zones for shorts above the current price, or the major potential liquidation zones for longs below and their distances.
ETH | Liquidation Zone Observation
Similarly, we lack a timely liquidation intensity distribution, making it impossible to reliably compare the leverage liquidation pressures above and below.
Institutional Holding Cost | BTC
The most recent verified disclosure from Strategy shows that as of October 11, it held 848,250 BTC, with an overall average purchase cost of approximately $75,444. Due to the lack of effective BTC/USD prices during the same period, this version does not calculate real-time cost differences, nor does it use the previous day's 9.22%.
Market Summary
Before the U.S. CPI release, interest rate expectations may become an important factor affecting BTC and ETH risk appetite. Currently, the lack of the latest prices and liquidation maps makes it impossible to determine whether leverage risks resonate with institutional cost lines.
4. Technology and Sector Movement Observations
Semiconductors: Declined for five consecutive trading days. The Philadelphia Semiconductor Index fell 0.23% on October 13, marking its fifth consecutive day of decline, with a cumulative drop of over 8% in five days. Micron Technology fell 3.6%, Applied Materials dropped nearly 7%, while Broadcom rose 0.7%. Concerns about competition in Chinese storage technology and AI investment returns continue to affect market pricing.
Banks: Earnings growth and stock price reactions have diverged. Citigroup fell 5.6%, Wells Fargo dropped 3.1%, JPMorgan fell 0.9%, and Goldman Sachs slightly declined by 0.2%. Despite some banks experiencing rapid profit growth, investors remain focused on net interest income, investment losses, and future business guidance.
Consumer and Healthcare: Individual stock events drove significant volatility. Bumble rose nearly 57% due to reaching a privatization agreement worth approximately $1.3 billion; Johnson & Johnson, despite better-than-expected performance, saw its stock price drop 5.7%; Domino's Pizza fell 4.8% after lowering its full-year sales outlook.
# 3. In-Depth Analysis of Key U.S. Stocks
1. Goldman Sachs (GS): Strong Trading Business, Profit Growth Needs to be Tested for Sustainability
Event Overview: Goldman Sachs reported a net profit of $5.29 billion for the third quarter, a 29% year-on-year increase, with revenue of $18.68 billion, up 23% year-on-year. Stock trading income grew 72%, becoming the main source of growth, but the stock price still slightly declined by about 0.2% on October 13.
Market Interpretation: Volatility in the stock market and clients adjusting their positions increased trading demand, helping Goldman Sachs achieve strong performance. However, trading income is easily influenced by market activity, and the growth in this quarter cannot be simply extrapolated as sustainable growth for the future.
Investment Insight: Focus on future stock and fixed income trading income, investment banking order reserves, and whether the recovery of capital market activities can translate into stable profits.
2. JPMorgan (JPM): Trading Business Growth, but Investment Losses Affect Profit Performance
Event Overview: JPMorgan reported third-quarter revenue of $50.17 billion, an 8% year-on-year increase, with stock trading income up 49% year-on-year and market business revenue up 15%. However, approximately $658 million in investment losses affected overall performance, and the stock price fell about 0.9% on October 13.
Market Interpretation: JPMorgan's operating results indicate that trading demand in the U.S. capital markets remains strong, but investment losses and risk exposure in a high-interest-rate environment are also worth noting. Revenue growth for banks does not mean that the profit quality of all business lines is improving simultaneously.
Investment Insight: Future attention should be paid to net interest income, credit losses, investment asset valuations, and whether stock trading income can maintain a high level.
3. Micron Technology (MU): Competitive Pressure and Storage Cycle Concerns Intensify
Event Overview: Micron Technology fell 3.6% on October 13, continuously affected by advancements in Chinese storage technology and adjustments in the semiconductor sector. The market is focused on how Changxin Storage's technological progress may change the competitive landscape of the future DRAM industry.
Market Interpretation: The storage industry is highly sensitive to supply and demand and pricing. Even if AI drives growth in high-bandwidth storage demand, potential increases in general DRAM supply may alter industry profit expectations. However, R&D achievements do not equate to achieving commercial mass production.
Investment Insight: It is essential to closely track DRAM prices, HBM supply and demand, competitors' mass production progress, and changes in Micron's actual gross margins. Short-term stock price adjustments alone cannot prove that the industry cycle has peaked.
# 4. Market and Project Dynamics
Strategy Holding Update: The company disclosed on October 12 that it purchased 250 BTC last week, bringing its total holdings to 848,250 BTC as of October 11, with an average purchase cost of approximately $75,444. This disclosure pertains to the previous week's trading and should not be interpreted as new buying on October 14.
Ethereum ETF Funding Pressure: Recently, there has been a continuous outflow of funds from the U.S. spot ETH ETF. Some industry data indicates that as of October 9, there have been nine consecutive trading days of net outflows, but this version has not obtained a complete verifiable daily fund flow table, so it does not report unverified cumulative amounts.
AI Infrastructure Financing Risks: The latest IMF research on financial stability warns of uncertainties between massive capital investments in the AI industry and future revenue realization. As more projects use debt financing, the market needs to pay more attention to clients' repayment capabilities and project cash flows, rather than just looking at investment scales.
Active Oil Derivatives Trading: Data from the Intercontinental Exchange shows that in the third quarter, the trading volume of Brent crude oil options reached approximately 28 million contracts, with an average daily trading volume increasing by 63% year-on-year. This change reflects a significant increase in energy market participants' demand to hedge against price volatility, but one cannot judge the future direction of oil prices solely based on options trading volume.
# 5. Today's Market Calendar
Beijing Time
Country/Region
Event
Market Attention Level
October 14 | United States | Third-quarter earnings reports from Bank of America and Morgan Stanley | ★★★★★
October 14 20:30 | United States | September Consumer Price Index (CPI) | ★★★★★
October 15 | United States | Speech by Federal Reserve Chairman Warsh | ★★★★★
October 15, 20:30 | United States | September Producer Price Index (PPI) | ★★★★
Key Event Preview: Tonight's CPI will directly impact the market's judgment on the Federal Reserve's future policies. If inflation continues to exceed expectations, long-term interest rates and the dollar may strengthen again, putting pressure on overvalued tech stocks and Crypto. Meanwhile, the earnings reports from Bank of America and Morgan Stanley will further verify whether the profit growth of large banks is sustainable.
Institutional View: Jake Dollarhide, CEO of Longbow Asset Management, believes that corporate earnings may help investors shift their focus from high interest rates and energy risks back to fundamentals. However, this still depends on whether subsequent companies can meet the market's high expectations for profit growth.
Disclaimer: This report is for market information reference only and does not constitute investment advice. Market conditions and clearing zones lacking the latest verifiable data have not been speculatively filled.
 Risk warning