








Hyperliquid's first L2 ecosystem Elysium officially launched on the mainnet today: Why is it important for Hyperliquid?
 Core Viewpoint

 The success or failure of Elysium will determine whether Hyperliquid can transform the assets and traffic of the "King of Perpetual Contracts" into the foundation of a complete trading empire.
Author: Gu Yu, ChainCatcher
On November 9, Kinetiq's Layer2 network Elysium officially launched its mainnet.
Unlike many new public chains that require significant effort to find ecosystem projects upon launch, Elysium had already attracted a number of mature infrastructures and applications to announce their support before its official opening. From Uniswap, KyberSwap, 0x, to OpenSea, Derive, xStocks, and cross-chain protocols like Wormhole and Mayan, it covers multiple fields such as trading, liquidity, derivatives, NFTs, tokenized assets, and data services.
This launch's "spectacle" is reminiscent of two other new chain releases this year: Circle's institutional Layer1 Arc launched its mainnet on September 16, gathering over 190 ecosystem partners on its first day, with support from 11 traditional financial and payment institutions including Mastercard and Visa; Robinhood's Robinhood Chain also saw nearly a hundred projects announce support on the day of its mainnet launch on July 1.
The launch of Elysium is almost a repeat of the same script. What makes Elysium special is that it does not attempt to build a new financial ecosystem from scratch but hopes to leverage the trading liquidity, users, and market structure already accumulated by Hyperliquid to further expand its application capacity.
This difference stems from its origins.
1. Origins: Hyperliquid's "Insider" Filling the Shortest Board
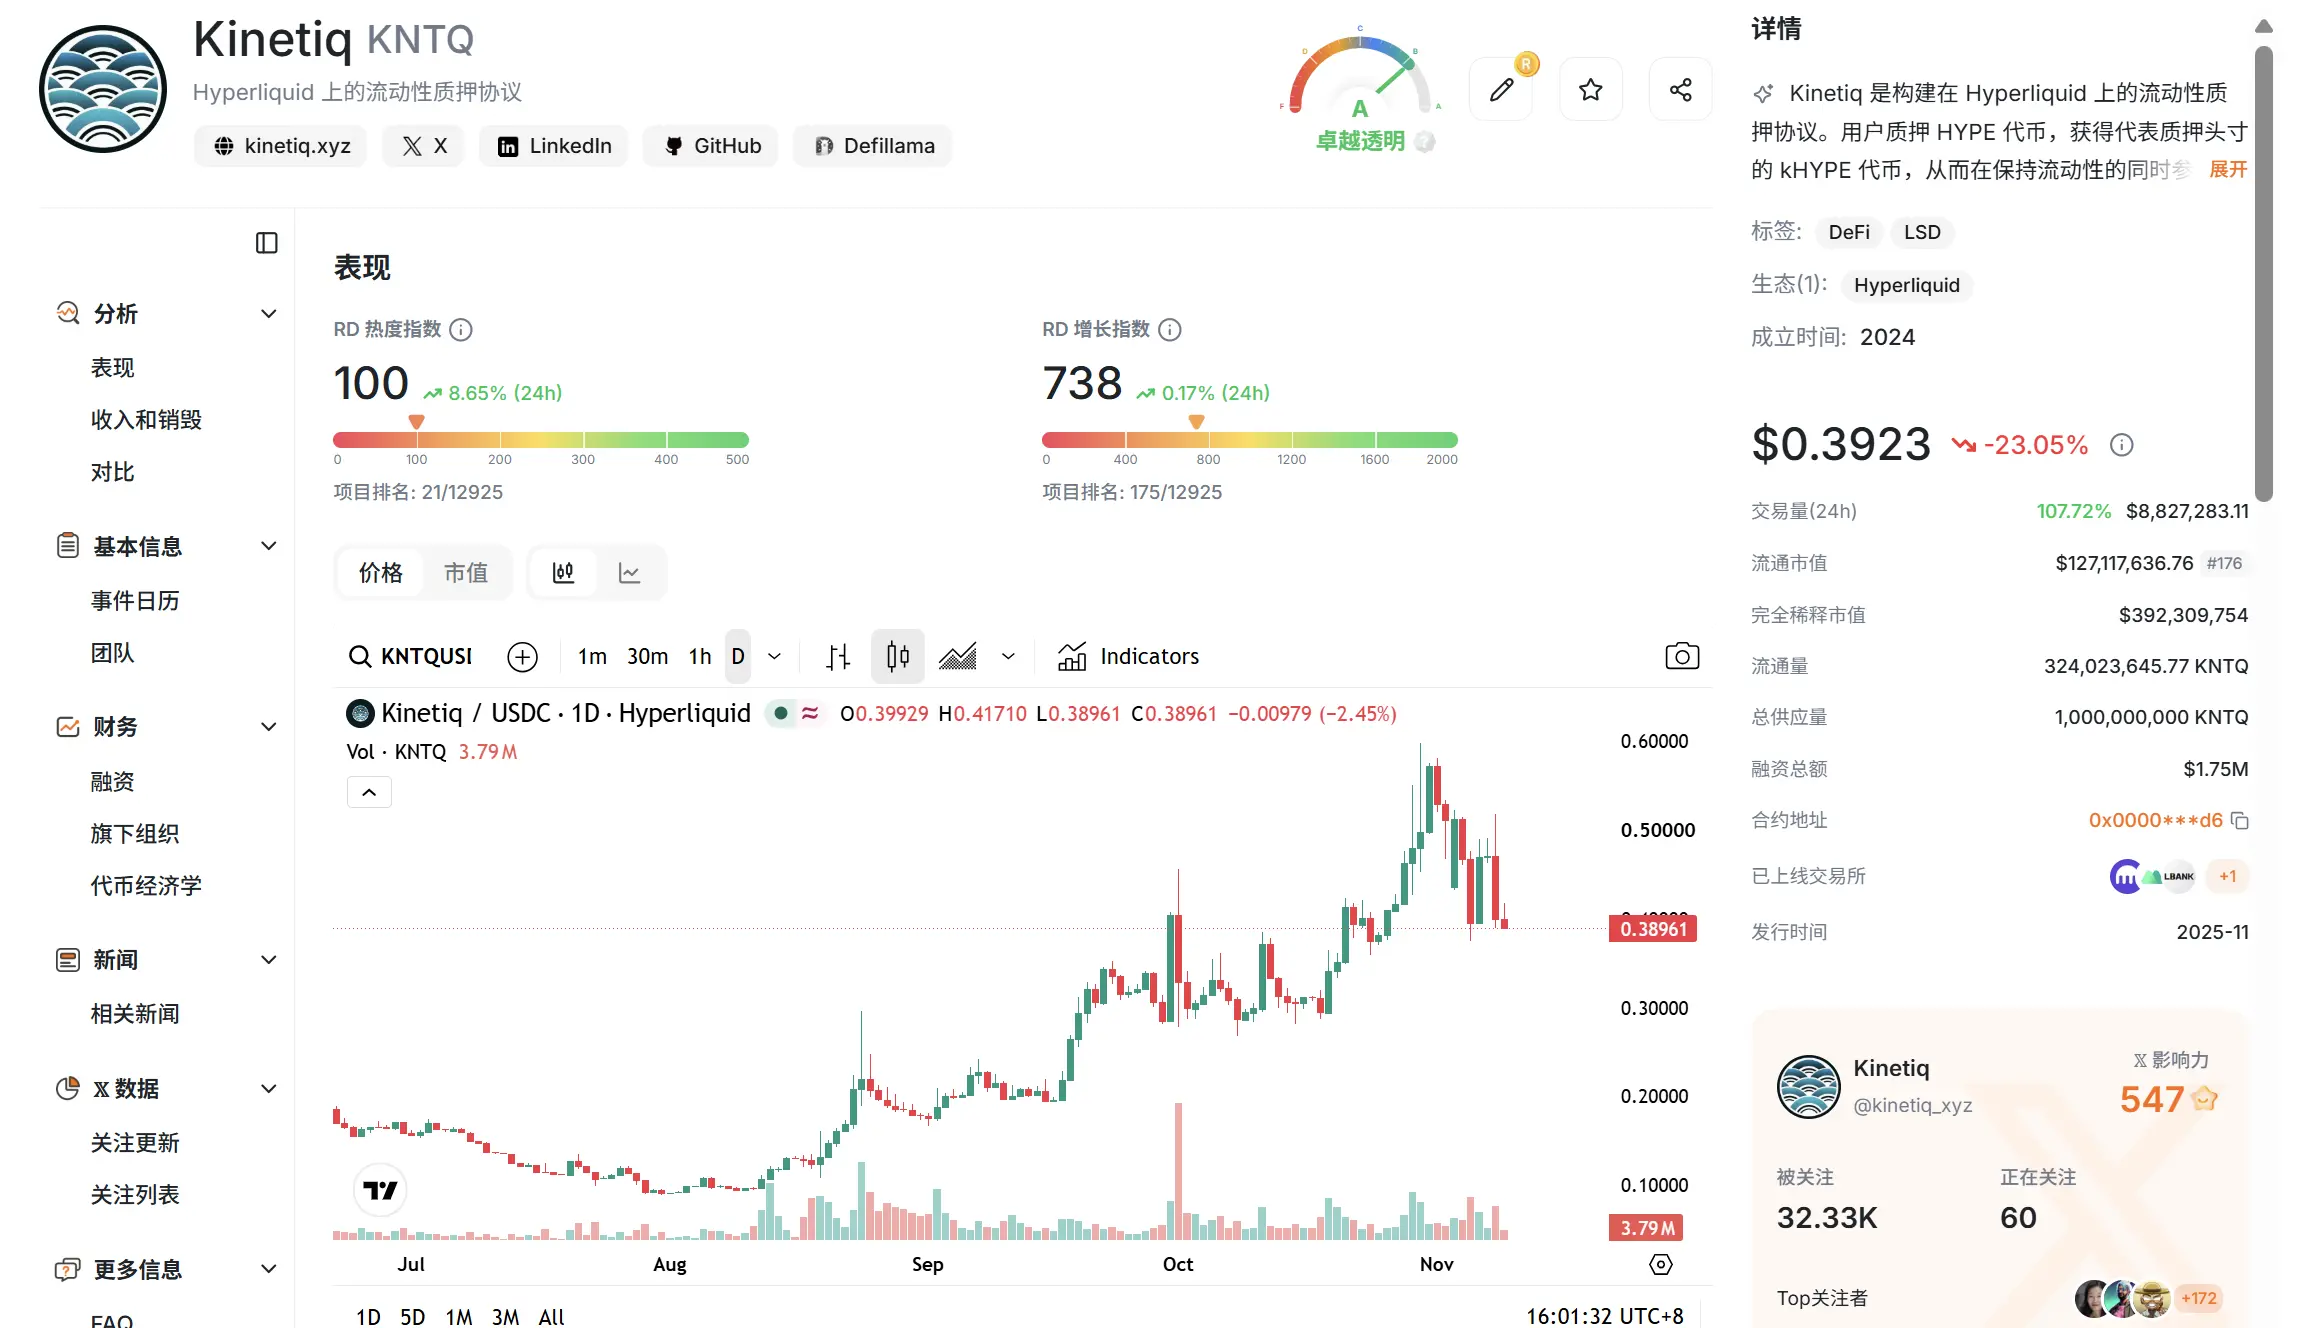
Elysium is not a project created by an external team trying to ride the wave; it is built by Kinetiq—the leading liquidity staking protocol in the Hyperliquid ecosystem and the issuer of kHYPE.
Kinetiq's position in the Hyperliquid ecosystem is quite solid: with a TVL exceeding $1.2 billion, its business lines have expanded from a single liquidity staking to institutional staking products iHYPE, yield products Earn, HIP-3 perpetual exchange deployment platform Launch, and self-operated perpetual platform Markets. The publicly visible co-founders include anonymous developer Omnia, Co-CEO Magnus Lai, and CTO Justin Greenberg, who previously raised $1.75 million in a seed round led by Maven 11, with participation from institutions like Pier Two, Chorus One, IMC, Flowdesk, and Susquehanna Crypto.
More critically, it aims to solve a problem. Hyperliquid has long faced a structural imbalance: perpetual contracts are thriving, while spot and DeFi applications have struggled to gain traction. On-chain monitoring data shows that Hyperliquid's spot trading volume relative to Binance has dropped to a 15-month low, with the activity of the HIP-2 self-market-making mechanism falling to its lowest point since Q4 2024; in stark contrast, on Solana, the on-chain spot trading volume led by PropAMM has long been over 30 times that of HyperCore's spot, and even the nascent Robinhood Chain can achieve about 10 times the volume of HyperCore's spot.
The absence of spot price discovery functionality is becoming Hyperliquid's biggest vulnerability in challenging top centralized exchanges. Elysium is aimed at addressing this gap: it attempts to create a complete asset delivery path—token issuance → AMM liquidity launch → HyperCore spot order book → HIP-3 perpetual contract market, allowing PropAMM-type applications to directly access HyperCore's order book data.
In other words, Elysium is not simply "adding an L2 to the Hyperliquid ecosystem," but is a critical step in Hyperliquid's evolution from a "perpetual contract trading platform" to a "trading infrastructure + application chain." This also explains why projects within the ecosystem are willing to treat it as "their own business."
2. Technology: Expanding HyperEVM's "Lane" by 600 Times
The need for an L2 in Hyperliquid stems from its intentional design choices: HyperEVM's blocks are consciously kept small, making the base layer sufficiently streamlined but also limiting the throughput ceiling for applications.
Elysium's solution is a combination of "standard component assembly + ecosystem-native customization": it is a high-throughput chain based on Arbitrum Orbit (Nitro + standard ArbOS), but the settlement layer is not Ethereum; it is HyperEVM—the smart contract environment of Hyperliquid, deployed in coordination with HyperCore responsible for transactions.
In terms of performance parameters, Elysium aims for 300 million gas per second, 30 million gas per block, and about 100 milliseconds for standard block intervals—officially comparing it to HyperEVM's capacity of 30 million gas every 60 seconds, claiming a difference of 600 times. Data availability uses the AnyTrust committee solution and publishes complete data to HyperEVM as an automatic fallback; withdrawals follow the standard optimistic withdrawal mechanism. On the sorting layer, the network operates with Conduit's G2 sorter, and the underlying architecture complies with SOC II Type 2 security standards.
The most ecologically significant design is that Elysium does not have its own token and does not set up a points program; the native gas token is HYPE. The launch configuration includes a single sorter, neutral priority fee sorting, and no privileged trading channels; MEV telemetry, Timeboost, and permissionless fraud proofs based on BoLD are listed as future reinforcement items.
For developers, this is almost a "zero migration cost" chain: standard EVM compatibility means MetaMask, Solidity contracts, and Uniswap-style pools are ready to use; for users, the only perceived differences are speed and transaction fees.
3. Economic Model: The Demand Black Hole of HYPE, the Value Flywheel of KNTQ
The design of "HYPE as the only gas" means that Elysium does not need to cultivate an independent gas token economy but directly binds network usage to Hyperliquid's economic system. Each transaction will generate actual demand for HYPE.
At the same time, sorter income is also designed as a bidirectional return mechanism. According to Kinetiq's disclosed plan, about 50% of sorter income will be used for public market buybacks and the destruction of KNTQ, with about 25% directed back to applications that bring traffic to the network, and the remainder entering the Kinetiq Treasury.
This allocation mechanism attempts to form a closed loop: gas consumption is captured by HYPE, part of the network income is returned to KNTQ through buybacks and destruction, and applications receive incentives through traffic sharing.
For Kinetiq, Elysium is not just an independent infrastructure product but an amplifier of its existing business: staking, launching, trading, and network usage can further form synergies.
On the day the news was announced, KNTQ surged by 30%, as the market had already reacted to this economic model in advance. However, whether the buyback mechanism can truly create long-term value ultimately depends on network transaction volume and actual income, rather than merely on the design of the mechanism.
4. Ecosystem: The "Hundred Regiments War" of Launchpad and Concerns
The most eye-catching aspect of the Elysium ecosystem is the intense rush of Launchpads. Just weeks after the testnet launch, over a dozen launchpads announced their participation, and thousands of tokens were created—the emergence of data tools like ElyScreener is due to "no one being able to see all the coins in one place."
The ecological map on the first day of the mainnet launch can roughly be divided into several categories: on the trading infrastructure side, Uniswap, KyberSwap, Aero, ArcherSwap, etc., provide liquidity layers; the issuance layer is the most competitive, with aka.fun (previously launched on Arc's mainnet), BunnyPad, PerpMe, Oxley, Neuriio, Ascend (official partner) each employing unique strategies—auction pricing, single transaction launches, AI Agent autonomous token issuance, social account tokenization; derivatives and prediction markets are filled by Derive V3 and Speculate (connecting to the HIP-4 result market); NFTs and games are covered by AtlasHL, slymz, TORPOR, Frog Flip, Eloscape, etc., with Eloscape supporting Robinhood Chain, HyperEVM, and Elysium simultaneously—a new chain choosing to position itself among multiple "peer new chains" indicates that Elysium has been placed in the competitive coordinate system of new chains alongside Arc and Robinhood Chain.
However, the other side of prosperity is concern. First, the ecological structure is clearly "top-heavy"—more than half of the nearly 30 projects are Launchpad and Meme infrastructures, which have short user lifecycles and thin value accumulation; whether they can support the grand narrative of "completing the spot puzzle" remains questionable. Second, the network's launch phase features a single permissioned sorter, and permissionless fraud proofs have not yet been launched, meaning security is still a "commitment" in terms of the roadmap. Third, since the official stance is clear about having no tokens and no points, the various "Elysium tokens" appearing on-chain should be treated as scams—official reminders have repeatedly stated that any Elysium tokens, presales, or points claims are suspicious.
Conclusion
Looking back at the launch of Elysium, what truly deserves attention is not a specific technical indicator but the industry trend it reveals: the threshold for competition among new chains is being redefined—Arc relies on Circle's institutional credibility and compliance narrative, Robinhood Chain relies on the exclusive scenario of U.S. stock tokenization, while Elysium relies on "nurturing external circulation with internal circulation" within the Hyperliquid ecosystem: using the cash flow and user mindset of perpetual contracts to support the shortcomings of spot and applications.
In the past six months, from Solana's PropAMM to Robinhood Chain's RWA spot market, Hyperliquid's lag in the spot trading sector has been repeatedly highlighted. The success or failure of Elysium will determine whether Hyperliquid can transform the assets and traffic of the "King of Perpetual Contracts" into the foundation of a complete trading empire. The grand opening day is merely a ticket to entry—whether the spot trading volume can truly be activated is the first test this chain must answer.
 Risk warning Risk warning

Popular articles





