Depth: Bitcoin mining undergoes drastic restructuring, and the shift towards AI is irreversible
 Core Viewpoint

 CoinShares report: Publicly listed mining companies overall fell below the cash break-even line in Q2, with the pre-tax cash cost per BTC being approximately $75,500.
Author | Luke Nolan, Senior Analyst of Ethereum Research at CoinShares
Compiled by | Wu Says Blockchain
The study period is the second quarter of 2026, so some data may be delayed.
TL;DR
· Public mining companies have overall fallen below the cash break-even line. In the second quarter of 2026, the weighted average cash cost per BTC for public mining companies was approximately $75,500, excluding taxes.
· Mining companies are accelerating their exit from mining, even paying to cancel mining machine orders. Core Scientific paid $41.9 million to cancel a Proto order of 15 EH/s; Keel has completely stopped mining; IREN and Cipher's exit plans will also reduce the mining power of public mining companies by at least about 35 EH/s. Several companies are simultaneously selling BTC reserves to fund AI data center construction.
· The core value of mining sites is shifting towards approved power access resources. Restrictions on data center development and lengthy grid connection cycles have increased the scarcity of powered sites. However, transformation still requires significant renovation investment, and whether tenants can be secured and construction decisions made will determine if the premium can be realized.
· AI valuation premiums have formed, but revenue realization is still in its early stages. Companies with signed AI/HPC contracts have an average EV/future 12-month revenue of 12.9 times, while companies without contracts and continuing to mine are at 3.7 times. Contracts worth over $100 billion currently correspond to only about $1.1 billion in annualized AI/HPC revenue, and of the over 4 GW of contracted capacity, only about 550 MW has begun billing.
· The mining industry is restructuring, not dying. The overall network hash rate has seen its first continuous six-month decline since China's mining ban in 2021, but the report believes it still aligns with historical cycle characteristics. Future mining investments are more likely to come from companies like Riot, MARA, HIVE, and Bitdeer that retain business flexibility.
· The next key is project delivery and financing costs. The Bitcoin rebound has improved mining cash profitability, but it is difficult to reverse the AI transformation locked into long-term leases. Whether mining companies can connect to power on time, start billing, and control financing costs will determine if current valuations can be supported by revenue.
I. Executive Summary
In the second quarter of 2026, public mining companies overall fell into a state where cash inflows could not cover outflows. The overall network hash rate has seen its first continuous six-month decline since China's mining ban, approximately 50% lower than trend levels. In June, the monthly average revenue per unit hash power hit a historical low of $27.7 per PH/s/day.
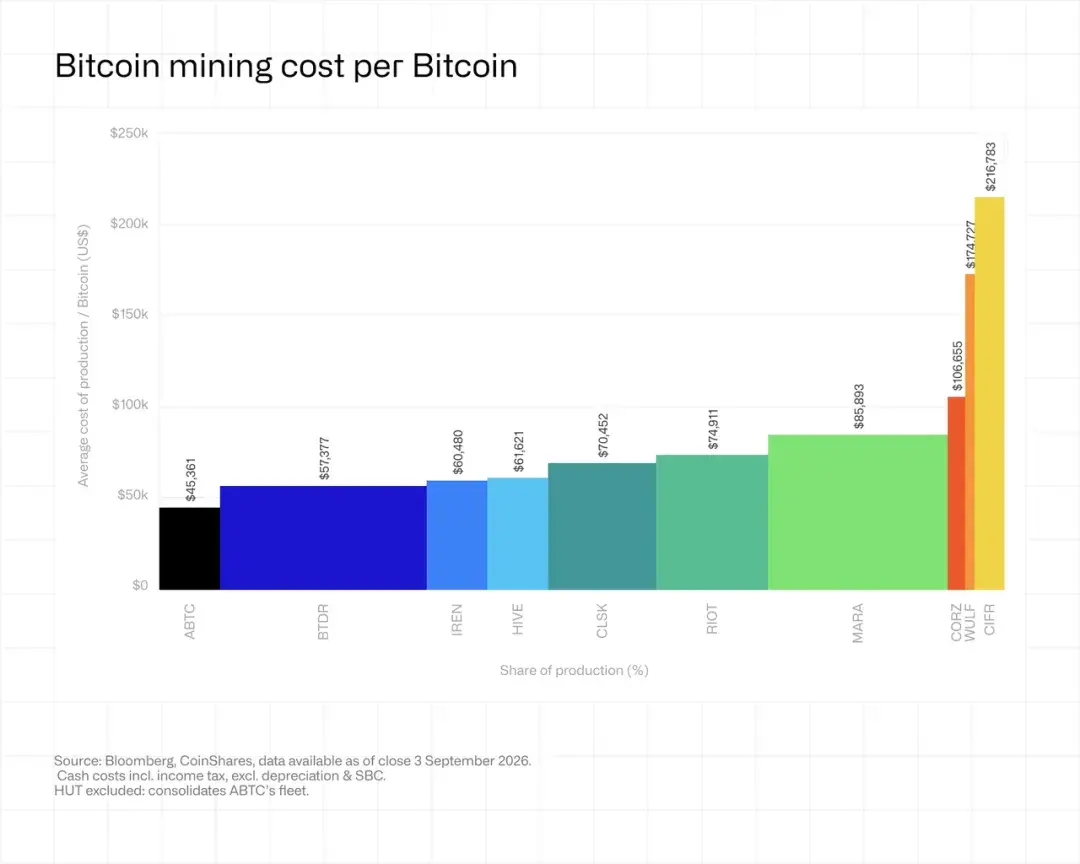
In the second quarter of 2026, the weighted average pre-tax cash cost for public mining companies to produce one Bitcoin was approximately $75,500.
Three core trends emerged this quarter:
Paid exit from mining: Core Scientific paid $41.9 million to cancel an order for new generation Proto mining machines with a total hash power of 15 EH/s. Keel stopped mining on June 29, and third-quarter mining revenue will be zero. With IREN and Cipher completing their exits, the public mining company group will also reduce its hash power by at least 35 EH/s. Keel and Cipher have also reduced their Bitcoin reserves, redirecting funds towards data center development.
Regulation is making powered sites scarce assets: Currently, 30 states in the U.S. have issued at least 225 data center development moratoriums or restrictions, of which 151 are still in effect, with New York being the first to implement a statewide moratorium. The U.S. has approximately 2,600 GW of capacity waiting to be connected to the grid, exceeding the total existing installed capacity nationwide. In Texas, among the 410 GW of large electricity projects in the ERCOT queue, data centers account for 87%. A recent transaction valued three fully leased AI data centers at approximately $27 million per megawatt, while some public mining companies with powered but unleased capacity are valued at less than $3 million per megawatt. Existing grid access resources are becoming increasingly precious.
Valuations have reflected premiums, but revenue has yet to be realized: Companies with signed AI or high-performance computing (HPC) capacity contracts have an average enterprise value to next twelve months sales (EV/NTM Sales) ratio of 12.9 times, while mining companies without such contracts are only at 3.7 times. Keel is an exception; despite not having signed with tenants, its valuation multiple still reaches 18.3 times. Currently, disclosed contracts awaiting fulfillment exceed $100 billion, but the corresponding annualized AI/HPC revenue is only about $1.1 billion; contracted capacity exceeds 4 GW, but only about 550 MW has actually begun billing. In the future, valuations will increasingly depend on whether companies can convert contracted capacity into actual billing revenue.
II. Regulation is Making Powered Sites Scarce Assets
A new limiting factor has emerged in the U.S.: it is becoming increasingly difficult to build new data centers. We believe this is fundamentally reshaping the valuation of existing assets of public mining companies. According to tracking data from ElectricChoice, 30 states in the U.S. have issued at least 225 data center development moratoriums or restrictions, of which 151 are still in effect.
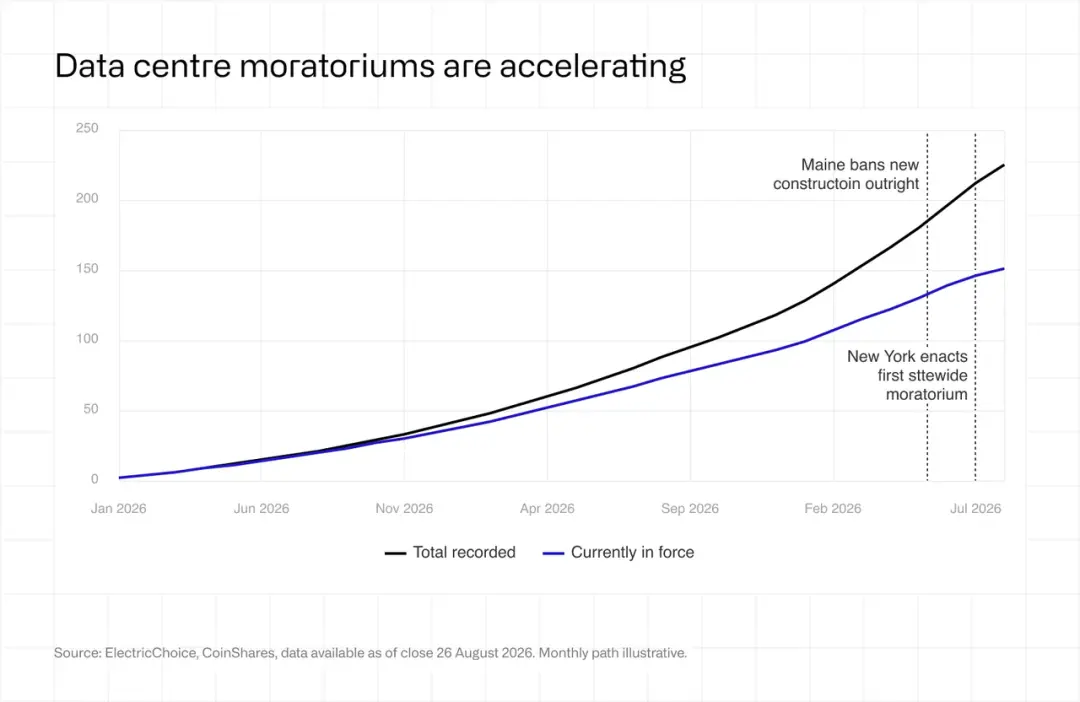
The most significant development occurred on July 14, 2026: New York became the first state to implement a statewide moratorium, halting the issuance of environmental permits for facilities with a capacity of 50 MW or more for one year. Maine's measures are even more aggressive, having fully banned new data centers since April 2026. Meanwhile, county-level restrictions are increasing in Ohio, Michigan, Georgia, and Indiana, with over one-third of counties in Indiana taking measures to limit development. The key is that projects with completed permit applications are often exempt, meaning that existing approvals now have option value that new entrants cannot replicate. This regulatory barrier further exacerbates the already severe bottleneck in grid access.
According to research from the Lawrence Berkeley National Laboratory's "Queued Up," the backlog of projects waiting to connect to the grid in the U.S. is approximately 2,600 GW, about twice the total existing installed capacity nationwide. For projects scheduled to go live in 2025, the median waiting time from application to official operation has exceeded five years.
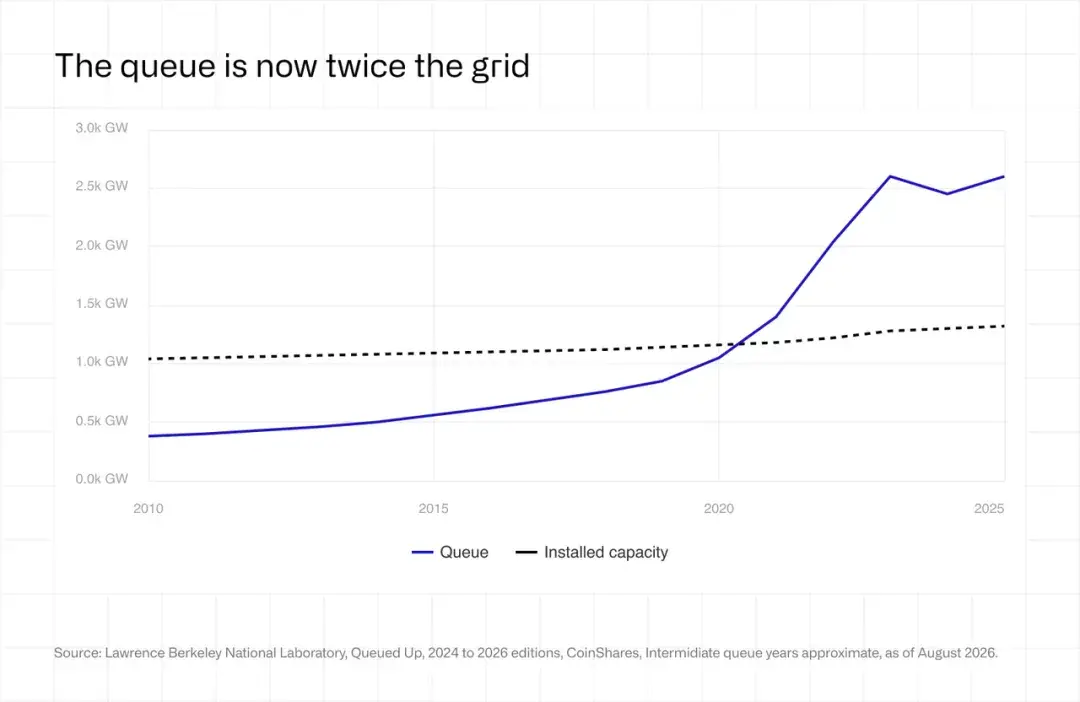
In the PJM grid coverage area, projects scheduled to go live in 2025 take an average of over seven years from initial application to official operation, while the delivery cycle for transformers has now exceeded 160 weeks. Data from ERCOT's large electricity project queue shows that data centers account for 87% of the total 410 GW of capacity waiting to connect. This means that regardless of how abundant the funds are, companies cannot replicate a powered site within a commercially viable time window.
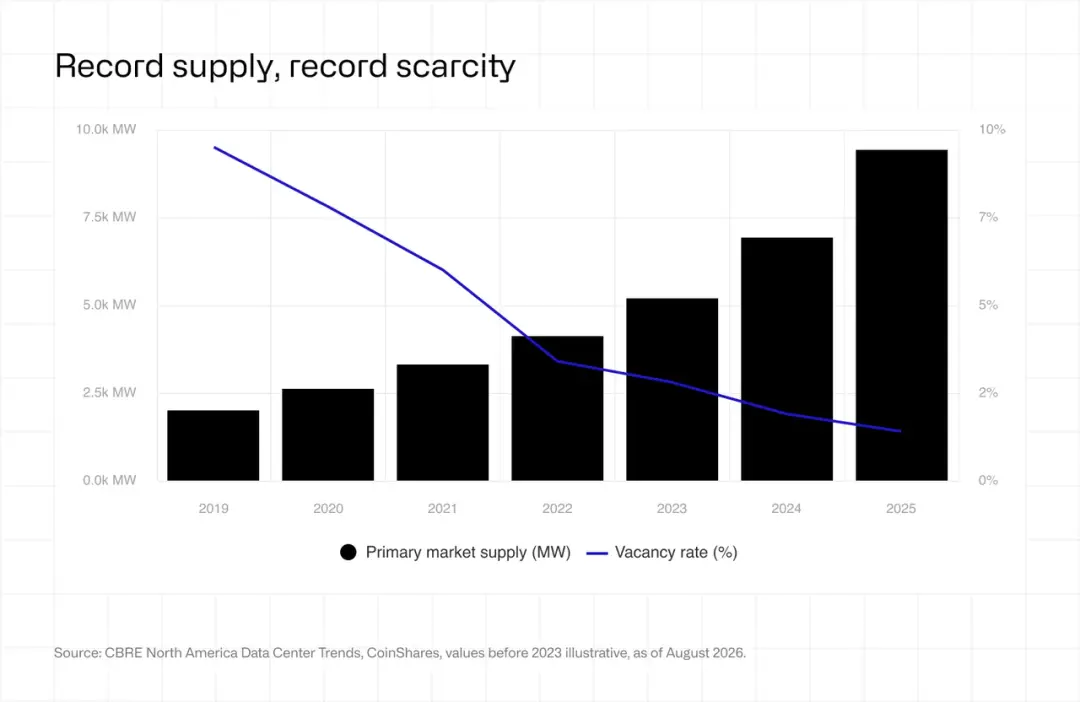
The market has responded by giving significant premiums to existing capacity. According to data from CBRE, despite a year-on-year increase in supply of 36%, the vacancy rate in the major data center market fell to a record low of 1.4% by the end of 2025; by the first quarter of 2026, the vacancy rate in Northern Virginia dropped to just 0.3%. Meanwhile, the pre-leasing rate reached about 75%, while the historical norm is 40% to 50%.
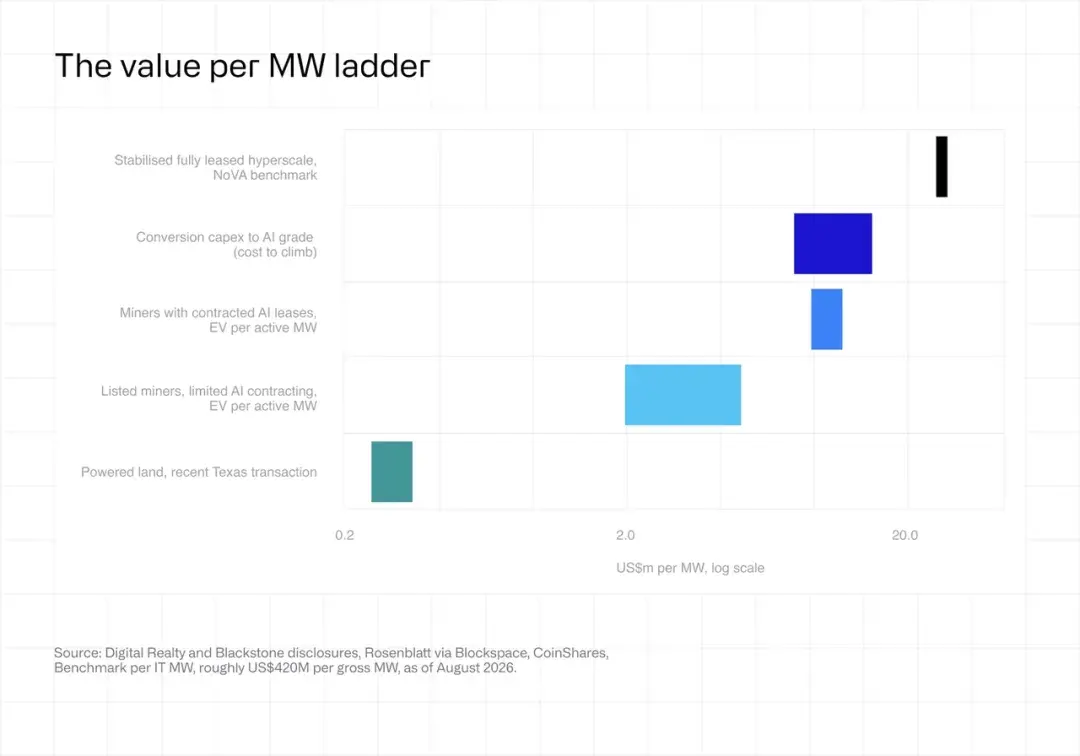
A recent acquisition deal totaling $3.5 billion involved three leased AI data centers in Northern Virginia, establishing a valuation benchmark of approximately $27 million per megawatt for stable AI infrastructure. In contrast, public mining companies with powered but unleased capacity currently have valuations per megawatt that are only a small fraction of this level, with some even below $3 million. These assets lack tenants, not permits.
The experience of one public mining company may best illustrate this valuation reshaping. The company rejected an acquisition offer slightly above $1 billion in 2024, but a year later agreed to sell for $9 billion in an all-stock deal. Its approximately 1.3 GW facility size remained largely unchanged, yet its valuation rose to nearly nine times the original. Even so, shareholders still rejected the deal in October 2025 on the grounds of an insufficient offer. In a more recent transaction, another large operator agreed to pay up to $600 million for land in Texas with 2 GW of grid capacity access rights but no buildings, equivalent to about $300,000 per megawatt. Following the announcement, its stock price rose by 15%.
It should be noted that having powered capacity is only a necessary condition, not a sufficient condition. Transforming mining infrastructure to meet AI requirements is expected to require an investment of $8 million to $15 million per megawatt, while the construction cost of mining facilities is only $700,000 to $1 million per megawatt. Therefore, the premium is primarily concentrated among operators with feasible renovation plans and signed tenants. Nevertheless, the trend is clear: regulatory restrictions and grid congestion have reversed the long-standing undervaluation of mining sites, turning these assets, once viewed as idle and low-grade infrastructure, into one of the most scarce approved power capacity resources in the U.S.
III. Paid Exit from Mining
In the second quarter, Core Scientific paid $41.9 million, terminating its agreement with Block's Proto division and canceling the delivery of next-generation 3-nanometer chips with a total computing power of approximately 15 EH/s. This batch of chips is the most energy-efficient mining hardware to date. Core Scientific intends to maintain its loss-making mining business, with its self-operated mining gross margin at -56%. Management stated that during the site renovation period, the company continues to operate the remaining mining machines purely to offset the power expenses stipulated in the contract.
The title of this section deliberately uses a vivid expression, summarizing the changes in the industry over the past two years: many Bitcoin mining companies are continuously shifting towards a hybrid business model that combines Bitcoin mining with computing power hosting, or completely transitioning to computing power hosting, gradually bidding farewell to what they now refer to as "traditional business" mining operations. The second quarter saw multiple cases reflecting this trend:
Keel (formerly Bitfarms) has officially shut down its Bitcoin mining operations. Its Moses Lake site stopped mining in April, while the Panther Creek, Scrubgrass, and Sharon sites ceased operations on June 29. The company accounted for accelerated depreciation of retired mining machines in its operating costs, resulting in a gross margin of -285% for the second quarter. In the third quarter, its mining revenue will be zero, making it the first publicly traded mining company to have zero mining revenue. Keel also sold 1,085 BTC at an average price of $69,100 each, totaling $75 million. As of August 7, the company held only 1,861 BTC and has indicated plans to liquidate its holdings by the end of the year.
Cipher Digital (formerly Cipher Mining) stated that it will no longer make capital expenditures for mining, expecting that its mining business will no longer have a substantial impact by 2030, and it is likely to completely exit by the end of 2027. In the second quarter, the company mined a total of 346 BTC, all from the Odessa site, which has a fixed electricity price contract of approximately 2.8 cents per kilowatt-hour. Similar to Keel, Cipher Digital sold $123.4 million worth of Bitcoin in the first half of 2026, resulting in a realized loss of $47.7 million, selling coins at a price below cost to fund the construction of facilities required by tenants. Currently, the company has only 646 BTC remaining.
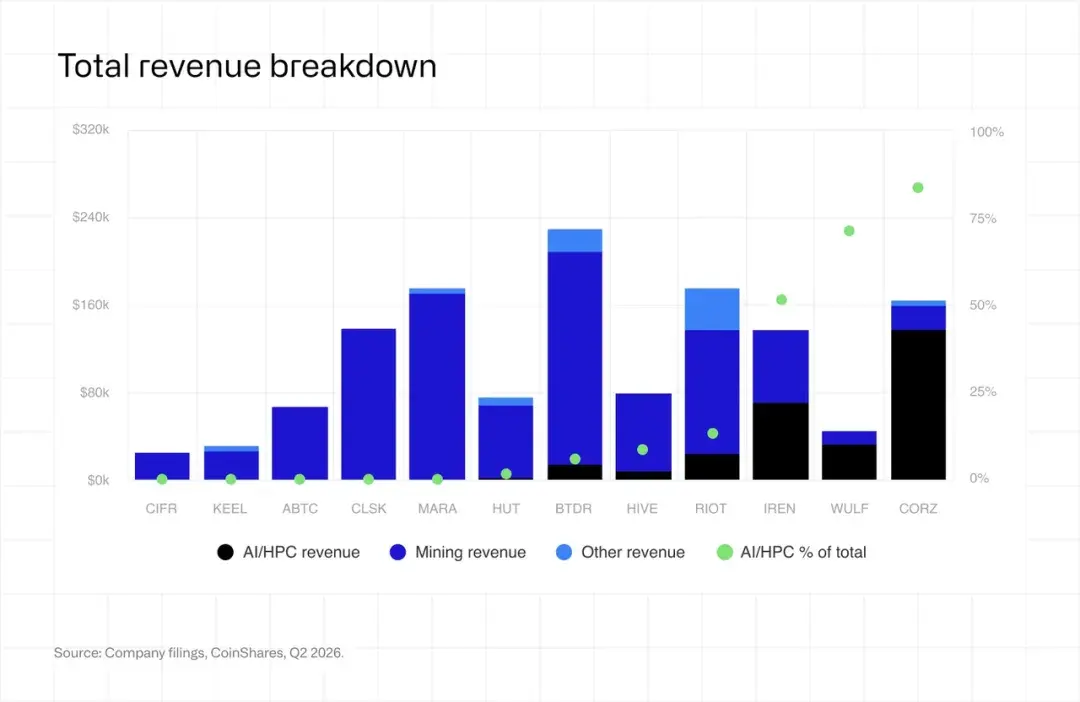
IREN stated in its 10-K annual report that the transition from mining to AI will be largely completed by December 31, 2026. The latest quarterly financial report shows that the company recorded an impairment of $450.4 million due to the decommissioning of mining hardware and an impairment of $102.1 million for mining machines held for sale. Additionally, IREN confirmed an asset disposal loss of $25.1 million. In line with this transition, its AI cloud business revenue has for the first time exceeded mining revenue, with figures of $70.5 million and $66.7 million, respectively. Currently, IREN holds no Bitcoin and has almost consistently maintained the practice of selling the output from its mining operations on the same day.
TeraWulf is also accelerating its transition to AI. In the first half of 2026, two mining facilities at Lake Mariner ceased operations, leading the company to record an impairment of $25.7 million on its mining assets and shorten the expected lifespan of its remaining mining assets. The HPC leasing business currently accounts for 71% of TeraWulf's total revenue, and the status of its mining business has also declined in disclosures: the company mined 179 BTC in the second quarter, which did not appear in the financial report press release nor was it mentioned in the earnings call, only disclosed in the 10-Q quarterly report.
Bitdeer sold $195.5 million worth of Bitcoin this quarter, and its current holdings are 150 BTC, down from 1,502 BTC a year ago. HIVE sold 918 of the 1,004 BTC mined in the second quarter, with another 46 BTC pledged as collateral for equipment deposits, effectively using newly mined Bitcoin to fund the procurement of mining machines.
Bitcoin mining has not headed towards extinction. What we see is a large number of publicly traded mining companies adjusting their business models to seize a lucrative and seemingly sustainable growth opportunity. As will be discussed below, computing power is changing hands; ultimately, the price of Bitcoin can and will alter the economic calculations behind these decisions.
4. Network Hash Rate and Unit Hash Rate Revenue
The Bitcoin mining network has just undergone the most severe test since the halving in April 2024. The total network hash rate dropped from a peak of approximately 1,160 EH/s in early October 2025 to 850 EH/s in early February 2026, a decline of about 27% from peak to trough. The first half of 2026 also became the first six-month period of hash rate decline since China's mining ban in the first half of 2021. Unit hash rate revenue, which is the income miners earn per unit of hash rate, fell to a historic low, remaining at or below the breakeven point for a significant portion of the operational mining machines during most of the first half. Looking at these data alone, the situation seems bleak. However, in historical context, this reflects a familiar stage in the mining cycle rather than a structural break in the industry.
The most effective way to judge the future direction of hash rate is to analyze historical patterns. From a qualitative perspective, hash rate growth is partly driven by Bitcoin prices, as optimistic price expectations encourage miners to increase hash rate in hopes of making profits. However, this judgment relies on assumptions about future prices. Considering the volatility of hash rate, measuring its deviation from the trend is more accurate than relying solely on qualitative judgments. We have explored this in our previous research. In the past, we used out-of-sample trend lines; this time, we chose to use a newer segmented model to construct historical trend lines to measure this deviation. For detailed explanations of this model, please refer to this report.
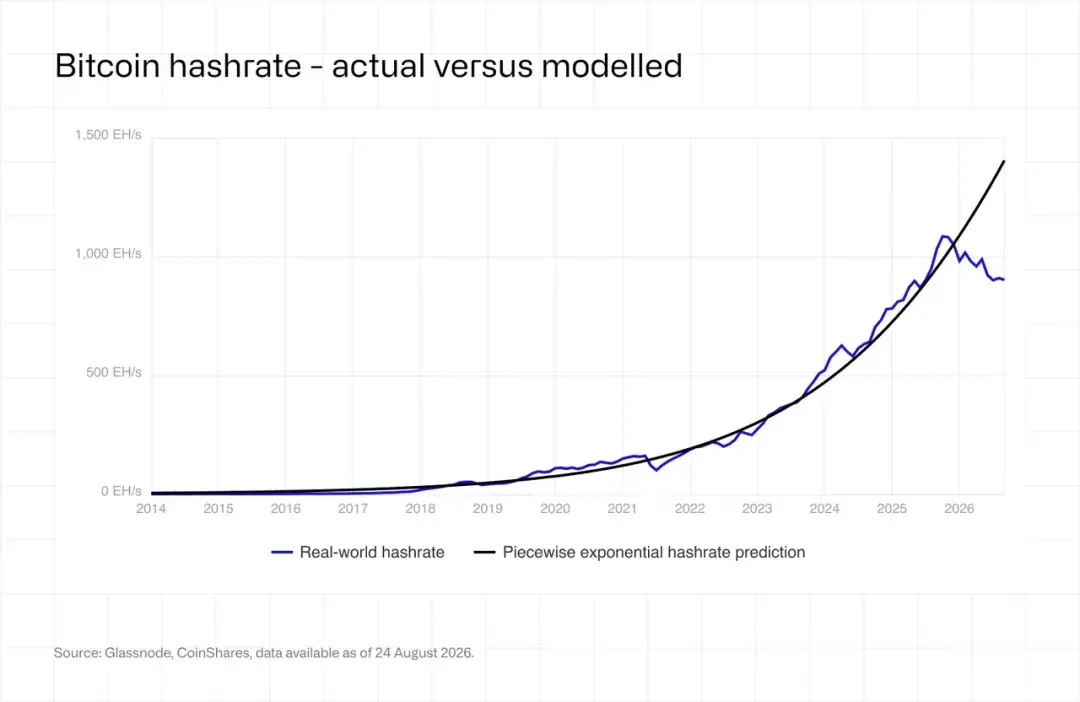
This framework reveals highly regular changes during each halving cycle. In the halving cycles of 2012, 2016, and 2020, hash rate typically drops to about 50% below the trend line within six months after the halving. The mining ban in China in 2021 was particularly severe due to its sudden onset, leading to a sharp decline in hash rate. It should be noted that the deviation magnitude we reported in January 2024 was 42%, which has now been revised due to our recalibration of the trend line using a segmented exponential method, changing the historical deviation measurement results. The overall trend remains consistent: a decline in the early stage of the cycle, recovery in the mid-stage, and a rapid increase in mining activity about a year before the next halving. The logic is straightforward: miners will increase capital expenditures before each halving to maintain competitiveness, thus driving hash rate significantly above trend levels; while the reduction in block rewards after the halving will depress income, thereby suppressing subsequent investments.
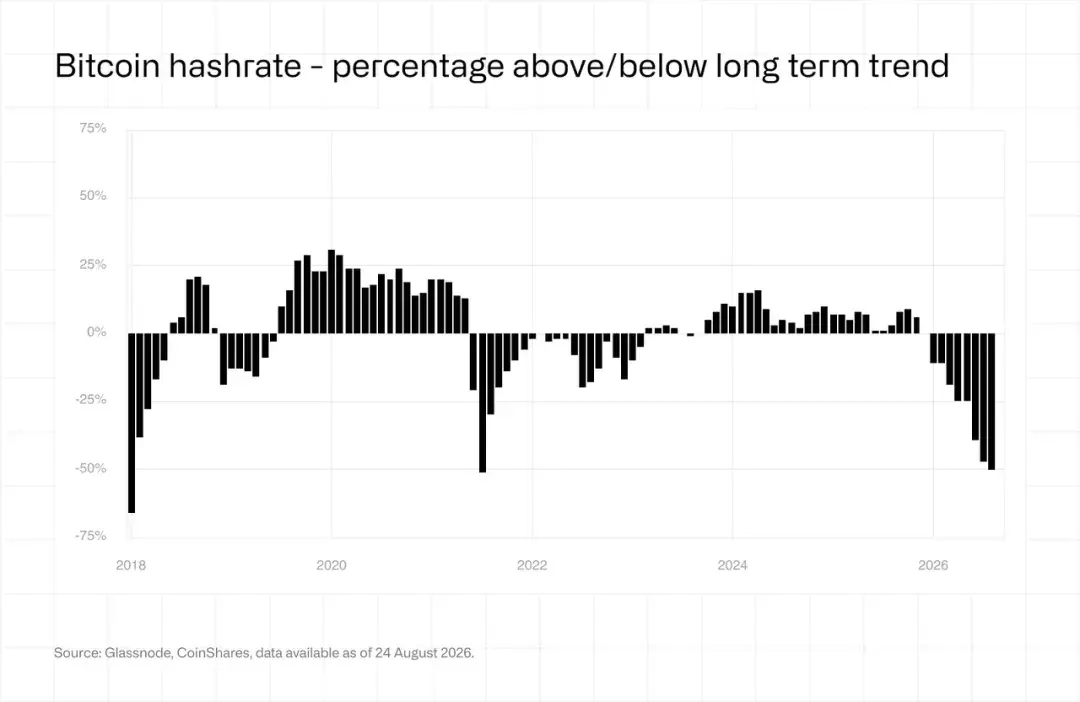
The resulting hash rate deviation is comparable to previous cycles. Currently, the hash rate is about 50% below the trend level, close to the trough shown by the recalibrated trend line after the Chinese mining ban, but this decline has been slower. We believe that this round of decline is due to the significant increase in electricity prices in Texas at the beginning of the year, coupled with mining companies continuously shifting towards high-power AI computing businesses. Whether the decline will continue partly depends on the price of Bitcoin. Currently, the economic attractiveness of AI business to mining companies is far higher than that of mining. According to our estimates, AI business can generate approximately $1.5 million in annual profit per megawatt, while mining only yields $500,000. However, if Bitcoin prices continue to rise, this profit comparison may change significantly, prompting some mining companies to reinvest their power capacity into mining.
Our segmented forecasting model previously predicted that the total network hash rate would reach 1.8 ZH/s by the end of 2026 and 2 ZH/s by the end of March 2027. The contraction in the first half has brought the hash rate far below this predicted path, and it now seems likely that reaching these milestones will be significantly delayed compared to the initial forecast. Meanwhile, the geographical distribution of global mining continues to change. The three major mining countries— the United States, China, and Russia— collectively account for about 68% of the global hash rate, with the United States' share increasing by about two percentage points quarter-over-quarter. Emerging markets such as Paraguay, Ethiopia, and Oman have entered the global top ten, driven by operators like HIVE and Bitdeer: HIVE has 300 MW capacity in Paraguay, and Bitdeer has 40 MW capacity in Ethiopia.
5. Mining Cost Analysis
1. Overview
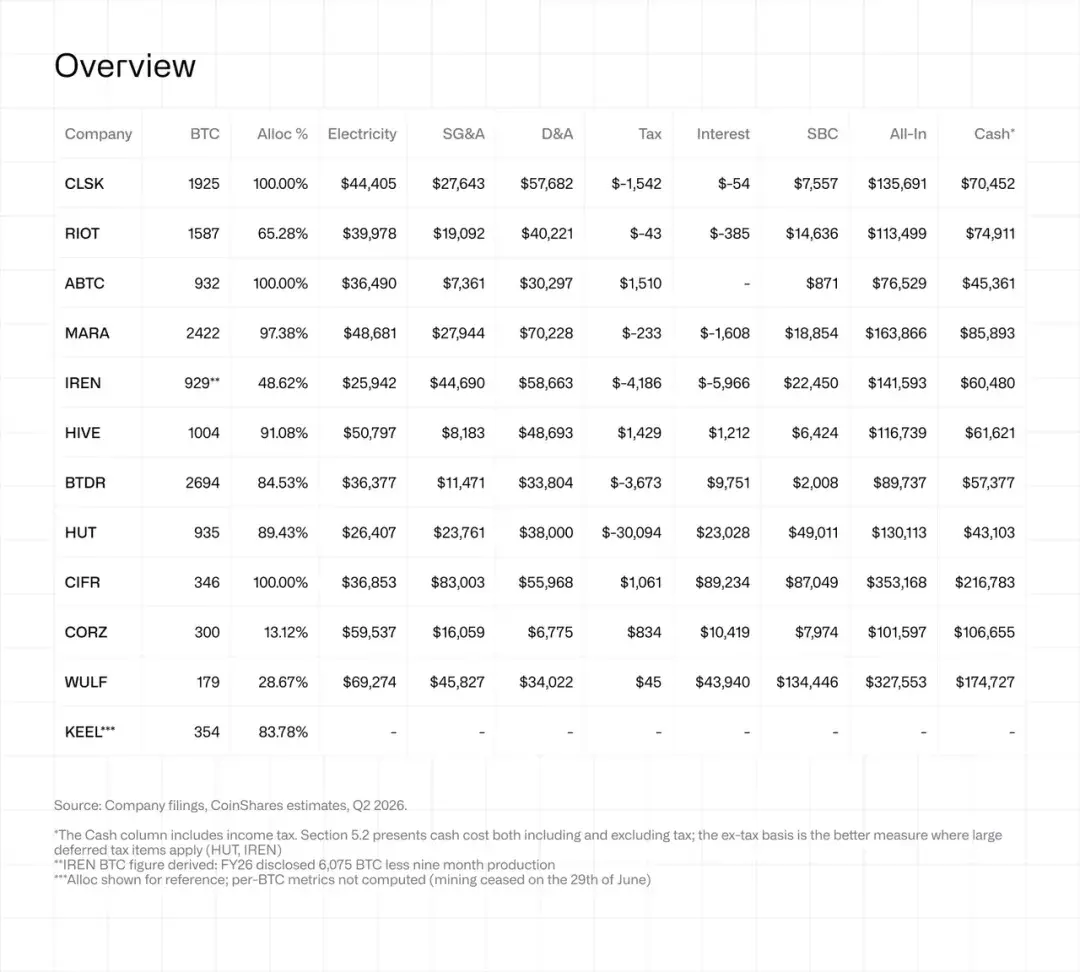
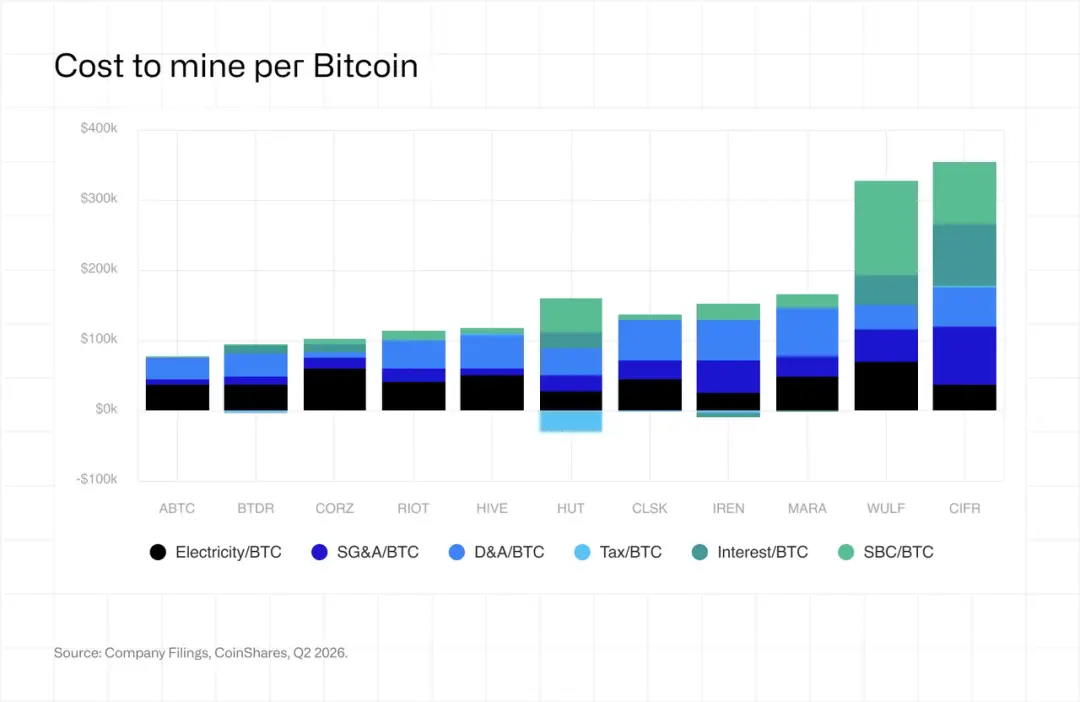
The table below lists the cost details for all mining companies covered in this report for the second quarter of 2026, expressed in USD cost per mined BTC. All data is allocated to self-operated mining business costs using the revenue share method described in the appendix.
Key Observations:
· Significant differences in cash profitability. The cash mining cost per BTC for ABTC, BTDR, HIVE, and IREN is below the actual selling price, while CLSK and RIOT are near breakeven. MARA recorded a cash loss of about $15,800 per BTC, while companies exiting the mining business have higher costs, primarily reflecting the impact of declining output.
· The allocation ratio of self-operated mining costs is increasingly significant to overall costs. Mining revenue accounts for 48.6% and 13.1% of total revenue for IREN and CORZ, respectively, meaning that most company-level costs are allocated to other businesses. Electricity costs are typically the most straightforward metric for directly comparing operational performance, but this is not the case for WULF, as the disclosed figure actually mixes costs from mining and HPC businesses.
· Taxes significantly distorted HUT's data. A deferred income tax benefit of $28.1 million reduced its cash cost per BTC to $43,103 after taxes, while the cash cost before taxes was $73,197 per BTC. Therefore, the pre-tax data better reflects the breakeven level of the mining business.
· Stock-based compensation (SBC) remains an important factor causing cost differences. The stock-based compensation per BTC varies from $871 for ABTC to $134,446 for WULF, with HUT, CIFR, and WULF exceeding electricity costs. WULF's data reflects the impact of a 28.7% allocation of $83.9 million in stock-based compensation to a production of only 179 BTC, indicating the shrinking production base as the company exits Bitcoin mining.
2. Cost details of each company
CLSK | CleanSpark Inc
BTC production: 1,925, all-in cost: $135,691/BTC, cash cost: $70,452/BTC, cash cost (excluding taxes): $71,995/BTC.
Note: CleanSpark's fiscal year ends in September, so the quarter ending in June is its third quarter of fiscal year 2026.
The company produced 1,925 BTC this quarter, with a self-mining cost allocation ratio of 100.00%. Its revenue of $138 million came entirely from mining, with no recorded hosting or HPC revenue, making it the purest mining company in this report.
Electricity costs were $44,405 per BTC, and the cash cost excluding taxes was $71,995, nearly matching the actual revenue of $71,691 per BTC. Depreciation and amortization remain the largest cost item at $57,682 per BTC, followed by selling, general, and administrative expenses (SG&A) at $27,643.
Stock-based compensation (SBC) remains relatively controllable at $7,557 per BTC. However, according to company disclosures, this quarterly expense has tripled year-over-year to $14.5 million. CleanSpark also signed its first HPC lease this quarter, involving the Sandersville site, with a lease term of 20 years and a base lease contract value of $6.6 billion. HPC has not yet contributed revenue in the third quarter of fiscal year 2026, but this agreement means CleanSpark will no longer be a pure mining company going forward.
RIOT | Riot Platforms Inc
BTC production: 1,587, all-in cost: $113,499/BTC, cash cost: $74,911/BTC, cash cost (excluding taxes): $74,955/BTC.
After deducting ERCOT demand response compensation, Riot's electricity cost was $39,978 per BTC, making its all-in cost of $113,499 per BTC somewhat competitive.
The cash cost excluding taxes was $74,955 per BTC, slightly higher than the actual revenue of $71,667 per BTC, indicating that the company's revenue was insufficient to cover all cash costs. The company's disclosed direct mining cost was $49,912 per BTC, which is consistent with our calculated electricity costs plus non-electric direct costs; the remaining difference comes from other business operating expenses. Mining revenue accounted for 65.28% of the company's total revenue of $174.2 million, so about one-third of the related costs were not allocated to the 1,587 BTC produced this quarter.
The $28 million impairment from converting the Rockdale site from mining to data center use was not included in this cost analysis. Riot's transformation also includes a cutting-edge AI lease contract with a capacity of 191 MW, a term of 20 years, and a value of approximately $9.1 billion, with corresponding deployment capital expenditure guidance of $2.1 billion to $2.3 billion.
ABTC | American Bitcoin Corp
BTC production: 932, all-in cost: $76,529/BTC, cash cost: $45,361/BTC, cash cost (excluding taxes): $43,851/BTC.
ABTC is the lowest-cost producer in the table, with an all-in cost of $76,529 per BTC and a cash cost excluding taxes of $43,851 per BTC, while the actual revenue per BTC is $71,905. Its electricity cost of $36,490 per BTC corresponds to a $34 million hosting fee paid to its 80% parent company Hut 8 based on a fixed arrangement, rather than the underlying cost of electricity consumed by the mining machines.
Hut 8's consolidated financial statements show that the direct costs for the same batch of mining machines do not exceed $24.7 million. Based on its disclosed gross margin of 66% for ASIC computing, the cost for just the ASIC business is estimated to be about $22.8 million. The quarterly difference of about $11 million, or about $12,000 per BTC, is obtained through transfer pricing by the parent company. ABTC's minority shareholders must bear the full impact of this transfer pricing, while the related transactions will be offset in Hut 8's consolidated financial statements. ABTC's SG&A and SBC are $7,361 and $871 per BTC, respectively, both the lowest in the table. The income tax expense disclosed by the company increased the all-in cost per BTC by $1,510.
MARA | MARA Holdings Inc
BTC production: 2,422, all-in cost: $163,866/BTC, cash cost: $85,893/BTC, cash cost (excluding taxes): $86,126/BTC.
MARA mined 2,422 BTC, but the cash cost excluding taxes of $86,126 per BTC is about $15,800 higher than the actual revenue of $70,315. Therefore, measured by all cash costs, the company is incurring significant losses in mining. Electricity costs were $48,681 per BTC, of which $11.79 million of the electricity expenditure was paid to third-party hosting service providers. The complete operating costs also included $26.9 million in non-electric direct costs, amounting to about $11,000 per BTC, which is also included in cash costs.
Depreciation and amortization are the largest components of the all-in cost, reaching $70,228 per BTC, which includes $28.1 million in accelerated depreciation. SG&A and SBC added costs of $27,944 and $18,854 per BTC, respectively, ultimately bringing the all-in cost to $163,866 per BTC.
This quarter, MARA's tax distortion issue was also resolved. The company recognized a valuation allowance for deferred income tax assets of $587.2 million, offsetting the deferred income tax benefit arising from the fair value accounting treatment of BTC holdings, leaving only a tax benefit of $233 per BTC in the cost calculation. MARA's policy allows for the sale of any portion of its total reserve of 53,822 BTC. Additionally, the company acquired a 64% stake in Exaion for $174.5 million, and a collaboration project with Starwood plans to sign two data center leases by the end of the year. Neither of these businesses generated significant revenue this quarter.
IREN | Iren Ltd
BTC production: 929, all-in cost: $141,593/BTC, cash cost: $60,480/BTC, cash cost (excluding taxes): $64,667/BTC.
Note: IREN's fiscal year ends in June, so the quarter ending in June is its fourth quarter of fiscal year 2026.
IREN's electricity cost of $25,942 per BTC is the lowest among publicly listed mining companies, and the cash cost excluding taxes is $64,667 per BTC, still lower than the actual revenue of $71,798. The main cost pressure comes from the company's construction of an AI business platform while Bitcoin production contracts.
AI cloud business revenue reached $7.05 million, surpassing mining business revenue of $6.67 million for the first time, accounting for 51.4% of total revenue. According to company disclosures, SG&A for fiscal year 2026 tripled year-over-year to $128.3 million; during the same period, the number of employees also increased nearly threefold, with the company appointing five executives and completing acquisitions of Mirantis and Nostrum. Even after allocation, SG&A reached $44,690 per BTC, while SBC and depreciation and amortization were $22,450 and $58,663, respectively. Net interest income reduced the cost per BTC by $5,966: the company's $7.6 billion cash balance generated $35.9 million in interest income, while financial expenses were $24.5 million.
The 10-K annual report states that the company will essentially complete its exit from Bitcoin mining by December 31, 2026, which means this quarter is likely to be IREN's last full quarter of operation as a Bitcoin mining company. This cost analysis does not include $450.4 million in impairment of mining hardware, $102.1 million in impairment of machines held for sale, $25.1 million in asset disposal losses, and $9.6 million in other operating expenses.
HIVE | HIVE Digital Technologies Ltd
BTC production: 1,004, all-in cost: $116,739/BTC, cash cost: $61,621/BTC, cash cost (excluding taxes): $60,192/BTC.
Note: HIVE's fiscal year ends in March, so the quarter ending in June is its first quarter of fiscal year 2027.
According to company disclosures, as the Paraguay site expanded, production this quarter increased by 147% year-over-year to 1,004 BTC, with an average hash rate of 24.0 EH/s. The cash cost excluding taxes was $60,192 per BTC, still lower than the actual revenue of $71,773 per BTC. Therefore, despite electricity costs reaching $50,797 per BTC, the company still retains a considerable cash profit margin.
Depreciation and amortization are the largest cost items, at $48,693 per BTC, reflecting the company's impact of accelerated depreciation arrangements for ASIC miners. SG&A remains at a low level, at $8,183 per BTC, while interest costs are $1,212. HIVE sold 918 of the 1,004 BTC mined this quarter and converted another 46 BTC into a deposit for Bitmain equipment, accompanied by a repurchase option with an exercise price of $110,000. At the end of the quarter, the company held 190 BTC. Additionally, HIVE raised approximately $276 million this quarter, increasing its cash balance from $23.1 million to $208 million.
The $84.65 million provision for Swedish VAT accrued due to an unfavorable ruling from the appellate court is not included in this cost analysis. There is also a $10.9 million Boden loan contingent on obtaining a favorable ruling, with a related $1.8 million receivable already impaired. These legal matters and the accounting impact of depreciation are significant, but the cash cost of $60,192 per BTC, excluding taxes, indicates that the continuously expanding mining business still has good profitability compared to the actual revenue level this quarter.
BTDR | Bitdeer Technologies Group
BTC Production: 2,694, All-in Cost: $89,737/BTC, Cash Cost: $57,377/BTC, Cash Cost (Excluding Taxes): $61,051/BTC.
Bitdeer is the company with the highest production in the table, mining a total of 2,694 BTC this quarter, a 61% increase quarter-over-quarter, while ranking second lowest in all-in cost at $89,737 per BTC. Its self-mining and joint mining operations have an electricity cost of $36,377 per BTC, benefiting from the high efficiency of the miner fleet at 15.8 J/TH and an average electricity cost of $44 per megawatt-hour. The cash cost excluding taxes is $61,051 per BTC, significantly lower than the actual revenue of $71,789.
The quarterly performance supports the company's rationale for investing heavily in the vertically integrated SEALMINER model, but there are two accounting factors to note. First, the company will transition from International Financial Reporting Standards (IFRS) to U.S. Generally Accepted Accounting Principles (US GAAP) starting January 1, 2026, and has restated data from previous periods. Second, the company has expensed $36.1 million in R&D costs, primarily for chip development. According to the customary method used in this report, this portion of expenditure is not included in the cost analysis. If this expenditure were allocated, the cost per BTC would increase by approximately $11,300.
Interest costs are $9,751 per BTC, the highest among major mining companies in the table, reflecting the $1.8 billion debt incurred for the expansion of the Tydal project. Bitdeer also raised $463.8 million through an ATM market offering in the second quarter.
HUT | Hut 8 Corp
BTC Production: 935, All-in Cost: $130,113/BTC, Cash Cost: $43,103/BTC, Cash Cost (Excluding Taxes): $73,197/BTC.
Note: Hut 8's data reflects the operational situation of the ABTC miner fleet from a consolidated financial statement perspective.
ABTC paid Hut 8 $34 million to host miners. In Hut 8's consolidated financial statements, this fee is offset, leaving the actual operating cost of the miners. According to its disclosure, this cost does not exceed $24.7 million. The approximately $11 million difference is profit obtained by Hut 8 from its own subsidiaries. The minority shareholders of ABTC bear this cost, while from an accounting perspective, Hut 8 shareholders recover it through the consolidated financial statements.
When comparing costs, data excluding taxes should be used. The apparent cash cost of $43,103 per BTC benefits from a $28.1 million deferred income tax benefit, equivalent to $30,094 per BTC, but this does not represent cash actually received by the company. After excluding this impact, the cash cost is $73,197 per BTC, slightly higher than the actual revenue of $71,674 per BTC.
The interest cost of $23,028 per BTC comes from the $7.5 billion project notes issued by the company for the construction of the AI park. The $49,011 per BTC in SBC originates from the $51.2 million equity incentive grant expense recognized this quarter, which occupies a significant portion of the all-in cost.
CIFR | Cipher Digital Inc
BTC Production: 346, All-in Cost: $353,168/BTC, Cash Cost: $216,783/BTC, Cash Cost (Excluding Taxes): $215,723/BTC.
Cipher's all-in cost of $353,168 per BTC can be misleading, as it primarily reflects the company's transition to AI. Although all disclosed revenue this quarter comes from mining, the company-level costs supporting a 5.3 GW infrastructure asset portfolio are allocated to only 346 BTC of production. SG&A, interest, and SBC contributed $83,003, $89,234, and $87,049 per BTC, respectively. The fixed electricity price agreement at the Odessa site of approximately 2.8 cents per kilowatt-hour, along with $2.3 million in demand response compensation and electricity sales income offsets, keeps electricity costs at $36,853 per BTC, which is also the only economic justification for the continued operation of this site.
The interest expense in the income statement for the first half of the year is $125.9 million, exactly matching the debt discount amortization from the $1.3 billion zero-coupon convertible notes maturing in 2031. Meanwhile, $23.2 million in construction period interest was capitalized, with actual cash interest paid in the first half of the year being $63.9 million. Overall, these per BTC cost data reflect the operational burden of the entire business platform, not the marginal production costs of the Odessa site.
CORZ | Core Scientific Inc
BTC Production: 300, All-in Cost: $101,597/BTC, Cash Cost: $106,655/BTC, Cash Cost (Excluding Taxes): $105,821/BTC.
Core Scientific is the only company where the cash cost excluding taxes is higher than the all-in cost, at $105,821 and $101,597 per BTC, respectively. The cash cost includes all expenses necessary to maintain mining operations: electricity costs, as well as personnel and site costs of approximately $19,800 per BTC. The calculation of all-in costs starts only with electricity costs, adding depreciation and amortization and SBC. However, since mining revenue now accounts for only 13.12% of total revenue, only a small portion of these expenses is allocated to Bitcoin mining operations.
Core Scientific's own segment disclosure shows that the operating cost of self-mining is $33.7 million, with cash costs of $23.8 million, the remainder being depreciation. Allocated to the 300 BTC mined this quarter, this amounts to approximately $79,300 in direct cash costs per BTC, while the average actual revenue per BTC is $71,783. This aligns with the loss situation reflected by the -56% gross margin disclosed by the company. According to the company, the number of online miners has decreased by about 30% since the end of the first quarter, and the remaining miners continue to operate purely to absorb the electricity expenses stipulated in contracts during the site renovation period.
WULF | TeraWulf Inc
BTC Production: 179, All-in Cost: $327,553/BTC, Cash Cost: $174,727/BTC, Cash Cost (Excluding Taxes): $174,683/BTC.
TeraWulf disclosed a production of 179 BTC only in the 10-Q quarterly report. HPC leasing income was $31.9 million, accounting for 71% of total revenue of $44.8 million, thus the cost allocation for Bitcoin mining is 28.67%. The all-in cost of $327,553 per BTC and the cash cost excluding taxes of $174,683 mean that TeraWulf cannot be directly compared on a unit economic basis: the company is shutting down its mining operations, while the AI business has become the dominant factor affecting the cost structure.
Even the electricity cost of $69,274 per BTC is overstated, as the corresponding operating cost item, after deducting $2.8 million in demand response compensation, still mixes mining electricity costs and electricity charges passed on to HPC tenants at cost. The $134,446 per BTC in SBC is particularly high: 28.67% of the group's $83.9 million equity incentive expense is allocated to a very small amount of BTC output, thus failing to accurately reflect its mining costs. Interest further adds $43,940 to the cost per BTC.
KEEL | Keel Infrastructure Corp
BTC Production: 354, All-in Cost: Not Applicable, Cash Cost: Not Applicable, Cash Cost (Excluding Taxes): Not Applicable.
Mining ceased on June 29, 2026.
Our table does not list Keel, as any per BTC cost data for the second quarter lacks sufficient reference significance. It is included in the analysis solely because the company produced 354 BTC this quarter, and it is necessary to record the date it ceased mining. According to the company's disclosure, the cessation date is June 29. Mining indeed contributed 84% of revenue this quarter, but this proportion will drop to 0% in the third quarter. By any definition, Keel is no longer officially a Bitcoin mining company.
6. Mining Company Stock Performance and Valuation
In the second quarter, mining companies experienced a significant valuation reassessment. Among the 12 companies covered in this report, 10 saw their stock prices increase between 70% and 195%. Notably, Keel led with a 194.4% increase despite shutting down its mining operations this quarter. IREN rose by 33.4%, while ABTC was the only company with a stock price decline, falling by 26.3%. Year-to-date, all companies except ABTC have outperformed Bitcoin, which dropped 10.1% during the same period. ABTC remains an exception, having accumulated a 67.2% decline year-to-date, with its valuation premium formed at the time of its listing at the end of 2025 continuing to fade.
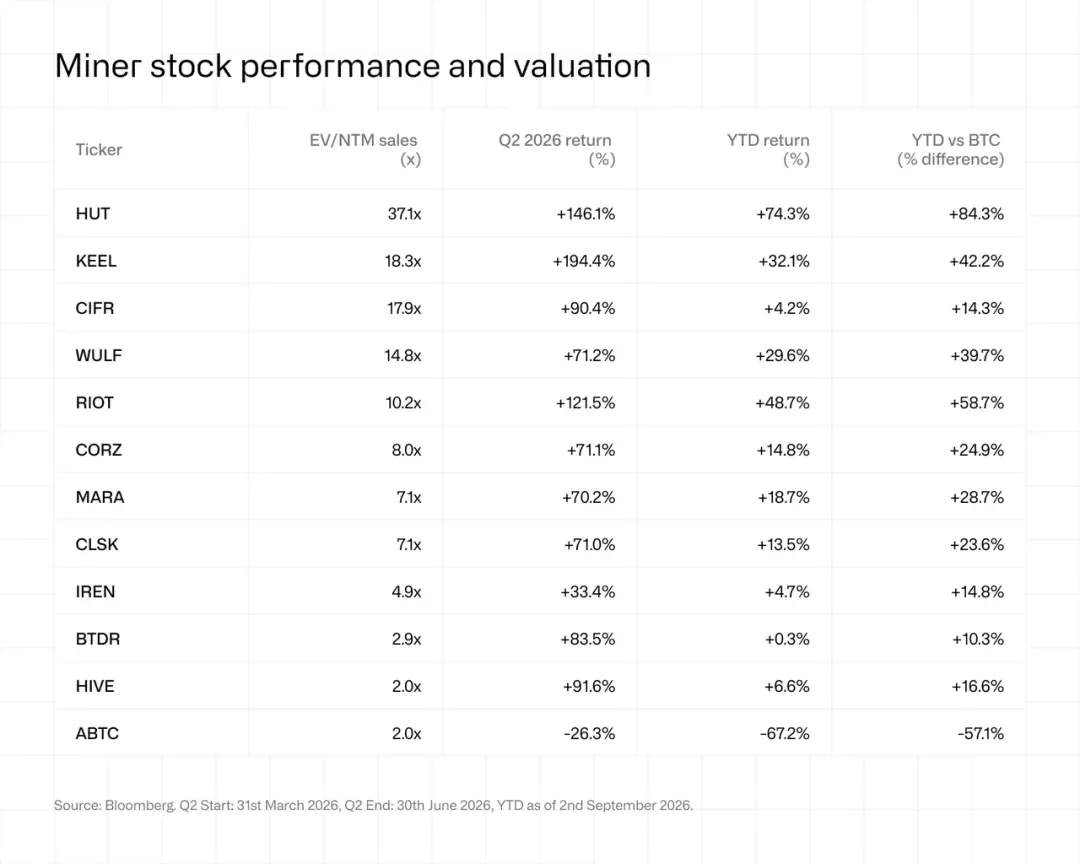
The valuation gap between mining-focused companies and those focused on AI has further widened. The average enterprise value to next twelve months sales (EV/NTM Sales) ratio for HUT, CIFR, WULF, and CORZ is currently 19.4 times, while MARA, CLSK, RIOT, and HIVE average 6.6 times. Companies that have signed AI or HPC capacity contracts have an average valuation multiple of 12.9 times. Among companies that continue to engage in mining and have not signed such contracts, the average for MARA, HIVE, and ABTC is 3.7 times. Keel is a clear exception, with a valuation multiple reaching 18.3 times despite not having signed contracts with tenants.
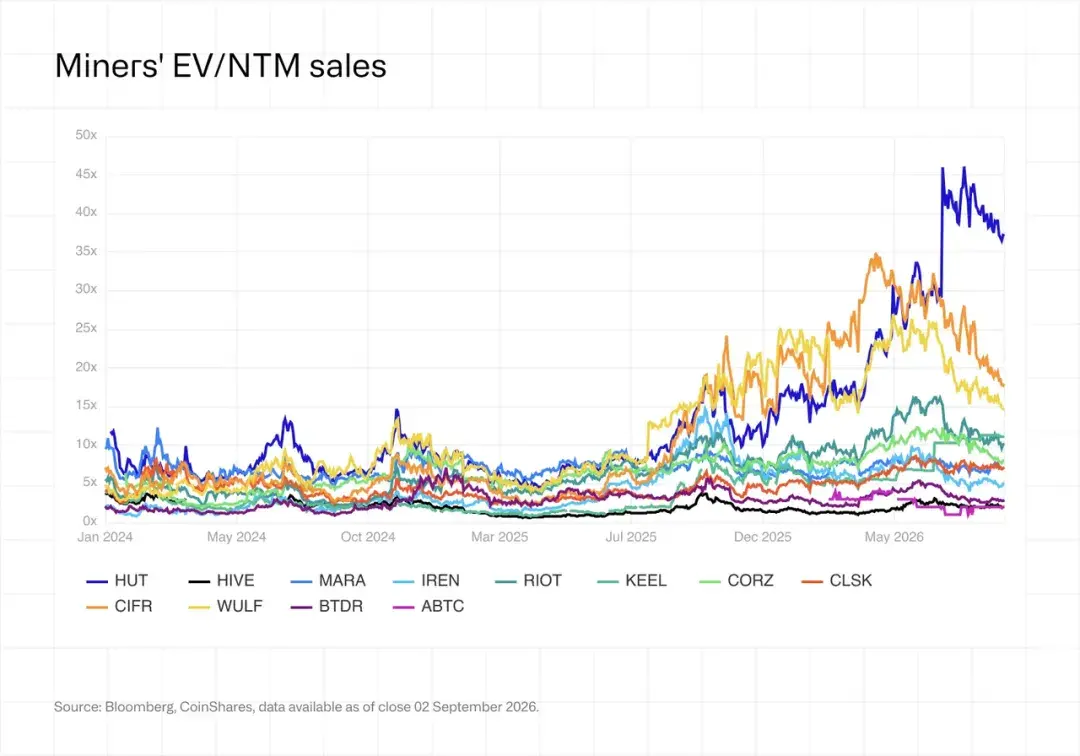
The valuation differences among contracted companies are also significant, ranging from 2.9 times for BTDR to 37.1 times for HUT. CORZ has one of the largest backlogs of contracts in the industry, yet its valuation multiple is only 8.0 times, lower than RIOT's 10.2 times, despite the latter having a much smaller contracted volume.
Understanding the extreme values in the valuation range requires context. HUT's valuation multiple has dropped from nearly 46 times in late July to 37.1 times, but it remains high partly because the $7.5 billion project debt raised in the second quarter has been included in the enterprise value, while the related projects have yet to generate actual revenue. IREN's valuation multiple is only 4.9 times because the market consensus has incorporated part of its $4 billion annual recurring revenue (ARR) target. CIFR most clearly reflects this effect: despite its stock price rising 90.4% in the second quarter, its valuation multiple fell from about 35 times in mid-April to 17.9 times, as revenues from the Black Pearl project were included in forecasts. As contracted projects gradually enter revenue expectations, even if stock prices rise, valuation multiples may decline.
Currently, the companies covered in this report have signed IT capacity contracts totaling over 4 GW, but only about 550 MW have actually begun billing. Therefore, the disclosed backlog of contracts exceeding $100 billion corresponds to an annualized revenue of less than $800 million from colocation services.
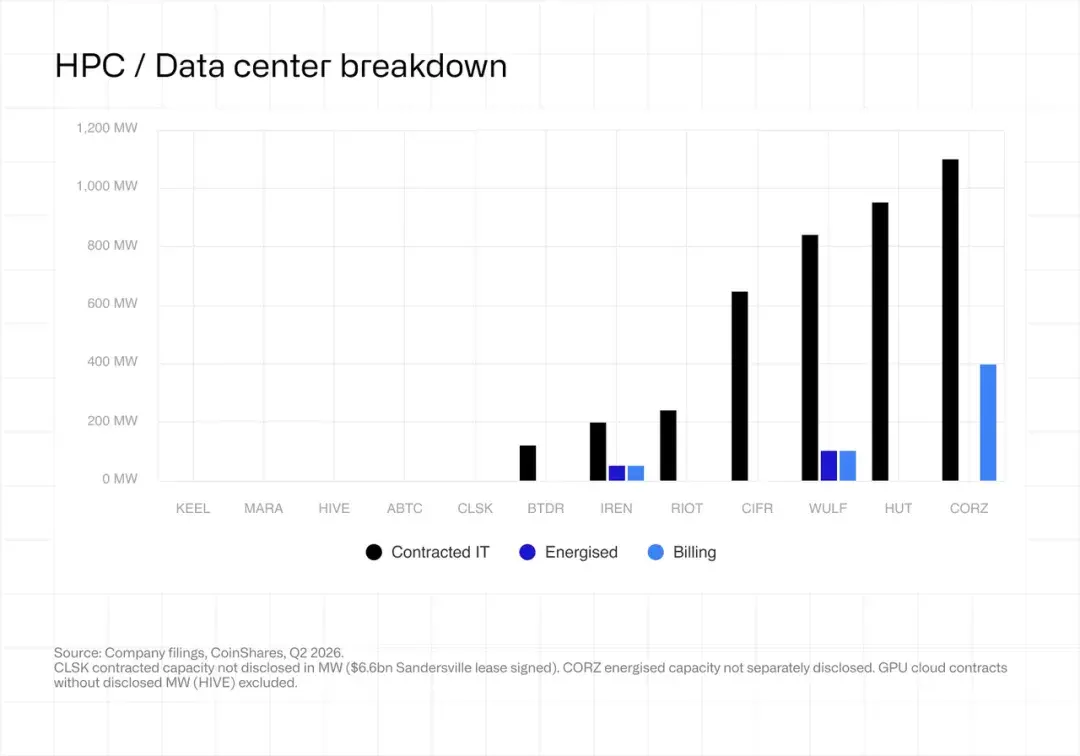
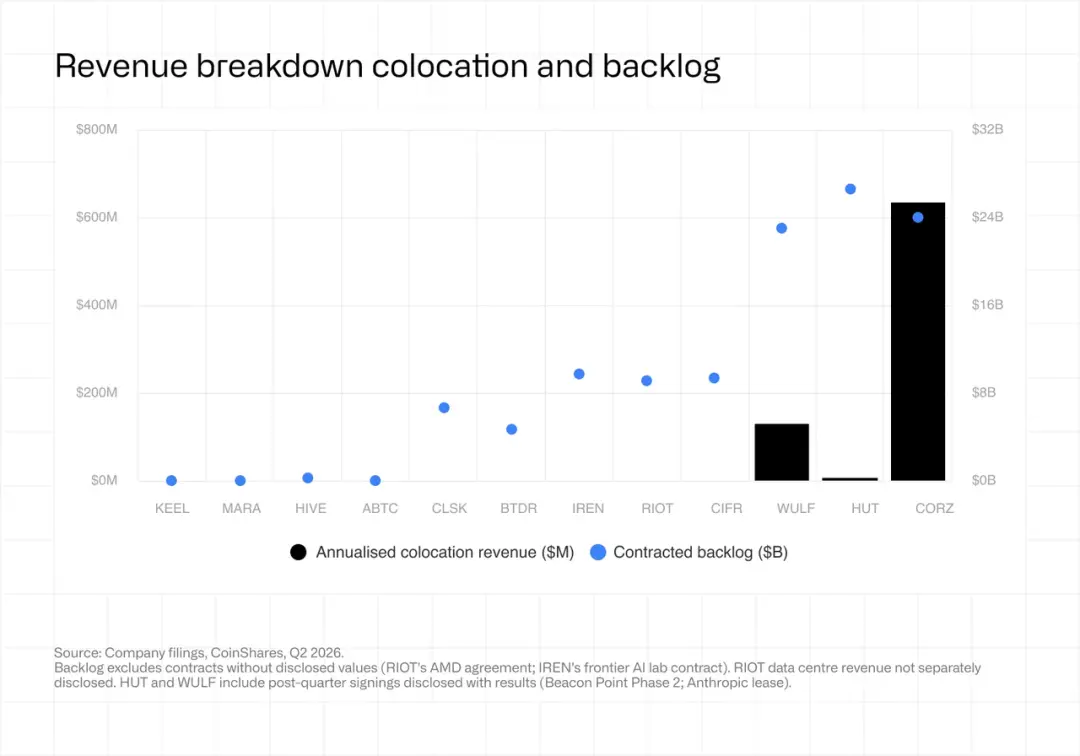
Companies that can bring capacity online as planned are expected to gradually catch up in revenue with their valuations; however, project delays will make it increasingly difficult to support the current valuation premiums.
VII. Outlook for Q3 2026 and Beyond
1. The mining capacity planned for exit by listed mining companies is at least 35 EH/s. Keel's mining capacity has dropped to zero. IREN currently has installed capacity of 23.2 EH/s and plans to exit mining by December 31, 2026; Cipher's Odessa site has 11.6 EH/s capacity, and the company is likely to exit by the end of 2027. TeraWulf is also gradually shutting down the remaining 145 MW of mining capacity, but the impact on the overall network's hash rate depends on whether its mining machines are retired or resold.
2. A rebound in Bitcoin prices is unlikely to reverse the trend towards AI transformation. Core Scientific has paid $41.9 million to terminate its Proto agreement involving 15 EH/s of capacity, and several other companies have repurposed sites to fulfill 15-year leases. Therefore, the next round of mining investments is more likely to come from Riot, MARA, HIVE, and Bitdeer, which have retained greater business flexibility.
3. The continued rebound in unit hash rate revenue still depends on Bitcoin prices. At the end of the second quarter, Bitcoin's price was $58,400, and only ABTC, BTDR, HIVE, and IREN had cash mining costs below the actual selling price. Subsequently, Bitcoin rebounded to around $77,000, driving daily revenue per unit hash rate up to about $38/PH/s. The key for the third quarter is whether Bitcoin can maintain above $70,000 throughout the quarter, thereby improving the economic benefits of mining.
4. Mining machine prices may decline. Mining machines from Bitmain and Bitdeer with energy efficiency below 10 J/TH will gradually be released in the second half of 2026, and the 15 EH/s Proto mining machines related to canceled orders may also re-enter the market. This should help reduce equipment upgrade costs for companies that continue to mine, improving the economic benefits of upgrade investments.
5. AI/HPC revenue is expected to accelerate growth in the second half of 2026. Currently, contracts exceeding $100 billion correspond to about $1.1 billion in annualized revenue. However, Core Scientific has already begun billing for 437 MW of capacity, Cipher's Black Pearl project started charging rent in August, and IREN plans to reach an annual recurring revenue (ARR) of $4 billion by December for its operational business. We expect that by the time the next report is released, the annualized revenue scale will increase to more than double the current amount.
6. Financing terms will become a more important factor in widening the gap between companies. Hut 8 raised $7.5 billion in non-recourse project debt in the second quarter, while Cipher and IREN secured financing at a 6% interest rate. Project-level financing costs will be more indicative than profits calculated under Generally Accepted Accounting Principles (GAAP), especially in the context where the three companies recorded a combined loss of $1.95 billion due to warrant remeasurement in the second quarter.
Appendix: Research Methodology
Denominator: The amount of BTC produced from self-mining this quarter.
Allocation Ratio: Self-mining revenue / Total revenue. This ratio applies to selling, general and administrative expenses (SG&A), depreciation and amortization (D&A), stock-based compensation (SBC), interest, and taxes.
Total cost per BTC = Power cost (excluding demand response compensation) + SG&A (excluding SBC) + Depreciation and amortization + Net interest expense + Income tax + SBC. Each expense is allocated based on the proportion of mining revenue, then divided by the amount of BTC produced from self-mining this quarter.
Cash cost per BTC = Operating costs (excluding depreciation and amortization) + SG&A (excluding SBC) + Net interest expense + Income tax. Each expense is allocated according to the above ratio, then divided by the amount of BTC produced from self-mining this quarter.
Power costs have been adjusted for demand response and curtailment compensation. Cost calculations do not include asset impairments, fair value remeasurements, or non-operating items, such as BTC revaluation gains and losses, changes in fair value of derivatives, and debt conversion inducement costs.
Unless otherwise stated, amounts are in thousands of dollars.
 Risk warning