








Thinking about Hood Chain in the context of RWA
 Core Viewpoint

 What will the next round of new assets be, and where will they be traded? This issue shares insights starting from the distribution demand of RWA, discussing the growth logic of Hood Chain, and then returning to the traffic, ARPU, and asset income of Robinhood.
Guest Speaker: HB, Debate Academy
CHAPTER 01 Why Study RWA
- Two Questions: What are the new assets for the next outbreak? Where are the new assets traded? In the past two to three months, the Robinhood chain has emerged, sparking a wave of meme frenzy.
- Quoting a line from the previous round: The meme itself is a marketing campaign for the chain it belongs to, with the chain behind it as the main character. When it comes to investment, it’s about looking at the chain behind the meme.
- The primary market is consolidating, and the boundaries between the primary and secondary markets are disappearing. Money and projects are concentrating at the top, with rounds often reaching 2 billion or 3 billion dollars; a recently studied fund has put 40% of its money into one project. Robinhood Ventures has entered its second phase, turning twenty to thirty primary projects into an index.
- RWA represents a paradigm shift at the bottom of the financial system, possibly the most significant change in the financial industry in thirty to forty years, but it will be much slower than AI. AI is a productivity tool that first penetrates the consumer side before reaching the business side; RWA is a transformation of the financial system—Bitcoin was born in 2008, and it may take 50 years to move assets entirely on-chain.
- The essence is to allow financial information to flow freely point-to-point like messages. For example, in the future, the academy's annual meeting could send stocks to the best students, just like sending a QQ message directly.
CHAPTER 02 What is RWA and What Does it Solve
2.1 Definition: The Same Logic as Q Coin
- Q Coin: 1 dollar is given to Tencent, and 1:1 Q Coin is minted. Stablecoins: 1 dollar is given to Circle/Tether, minting USDC/USDT. Stock tokenization is the same: hand over Apple stock to the issuer (like Ondo, token resembling AAPLon) or Robinhood, and mint tokens 1:1.
- What holders receive is not the asset itself but the issuer's promise (Q Coin is not owned in your hands; it is essentially Tencent's promise to you).
2.2 Three Functions
Distribution (Core Pain Point): Latin America and Africa cannot access US dollars; USDT can deliver dollars to them. The same applies to stocks: users in mainland China and Asia, Africa, and Latin America cannot buy US stocks but can purchase them on-chain. This is a distribution channel for dollar assets to the whole world. The end goal is to issue stocks directly on-chain and trade directly, bypassing Nasdaq and eliminating the boundaries between primary and secondary markets.
24/7 Trading: The financial infrastructure off-chain in the U.S. is also upgrading, and this is being solved off-chain.
A Large Ledger, Programmable Portfolio: For example, collateralizing a loan with Apple. Currently, due to regulatory and legal barriers between China and the U.S., this cannot be done, but it can be done on-chain.
2.3 Issues with Stock RWA: Two Parallel Settlement Systems
- In today's financial system, a stock transaction involves four steps: Order receipt (e.g., IBKR) → Execution → Clearing → Settlement, and the same four steps occur on-chain. Native tokens (BTC, ETH, UNI, etc.) complete the entire process from order receipt, matching to clearing and settlement on-chain.
- Stock tokens complete clearing and settlement on-chain, but off-chain, another delivery must be done because legal rights and dividends are off-chain. Two systems operate in parallel, and efficiency is determined by the slowest link, so RWA has not solved the efficiency issue.
- Why Stablecoins are the Most Successful: Not because they are the most standardized, but because dollars do not need off-chain settlement; all clearing and settlement can be completed on-chain.
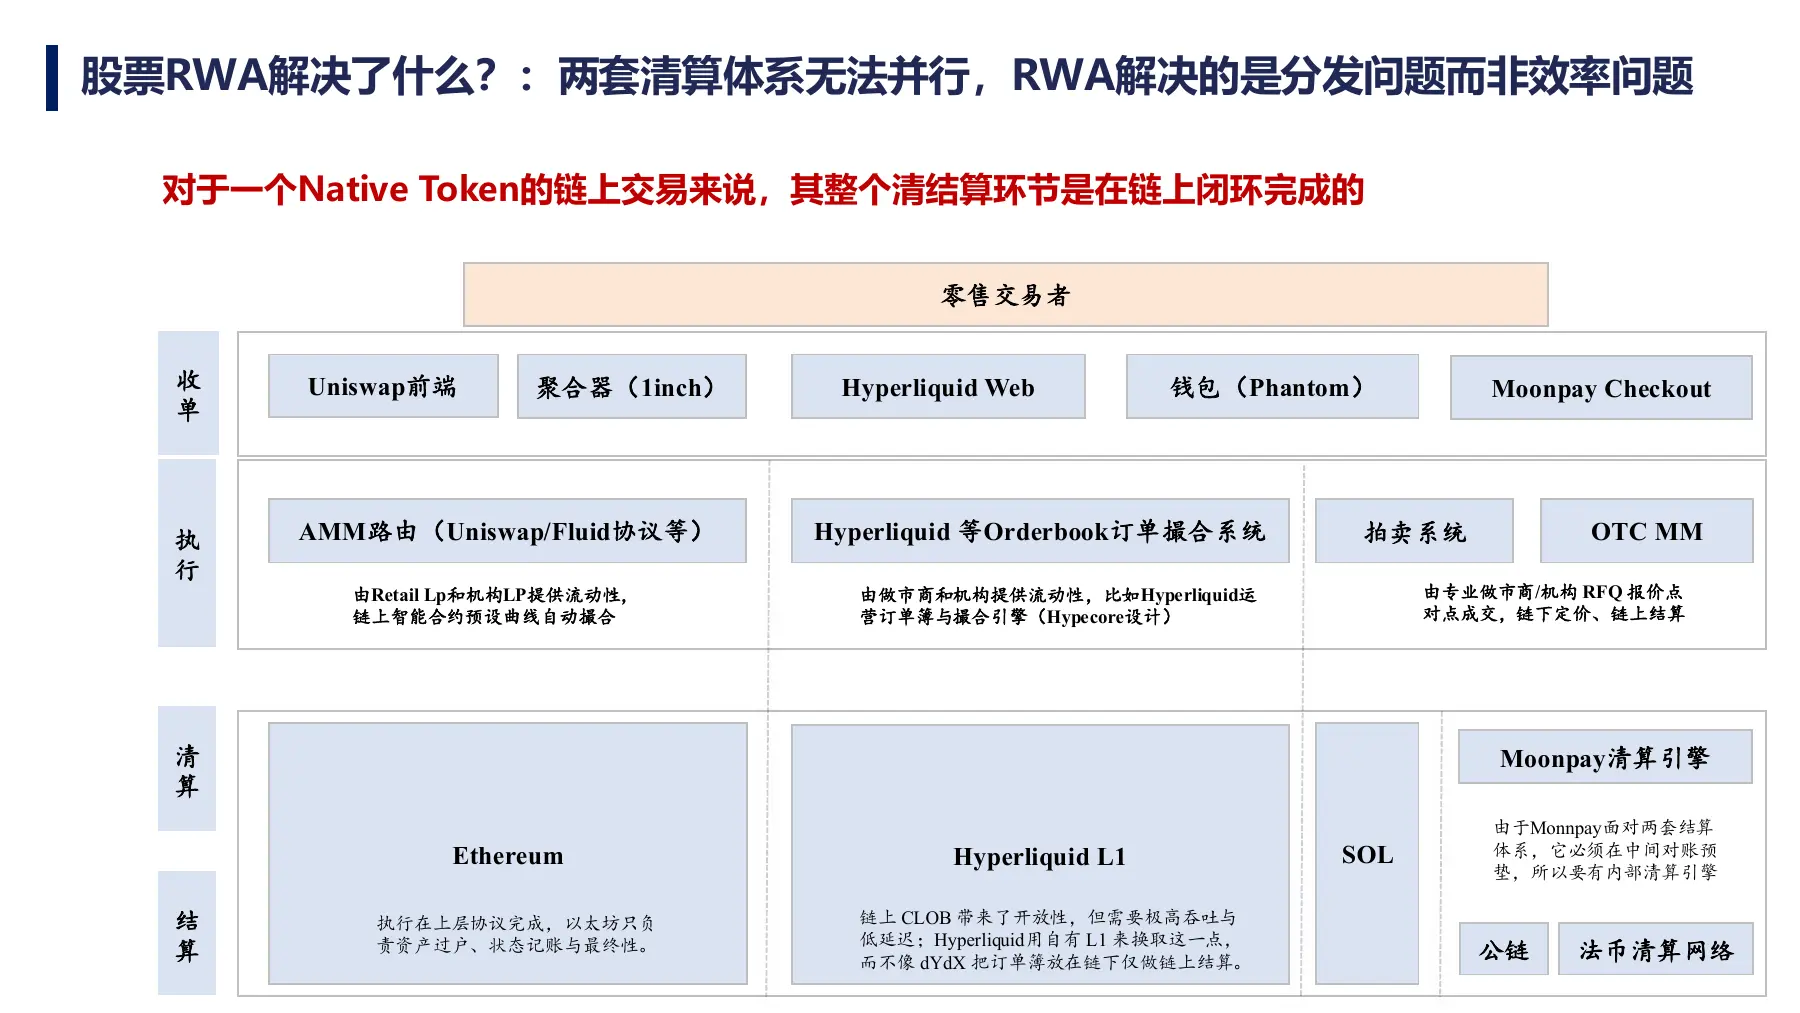 On-chain Trading and Settlement of Native Tokens · Original Slide Page 3 · Click to enlarge
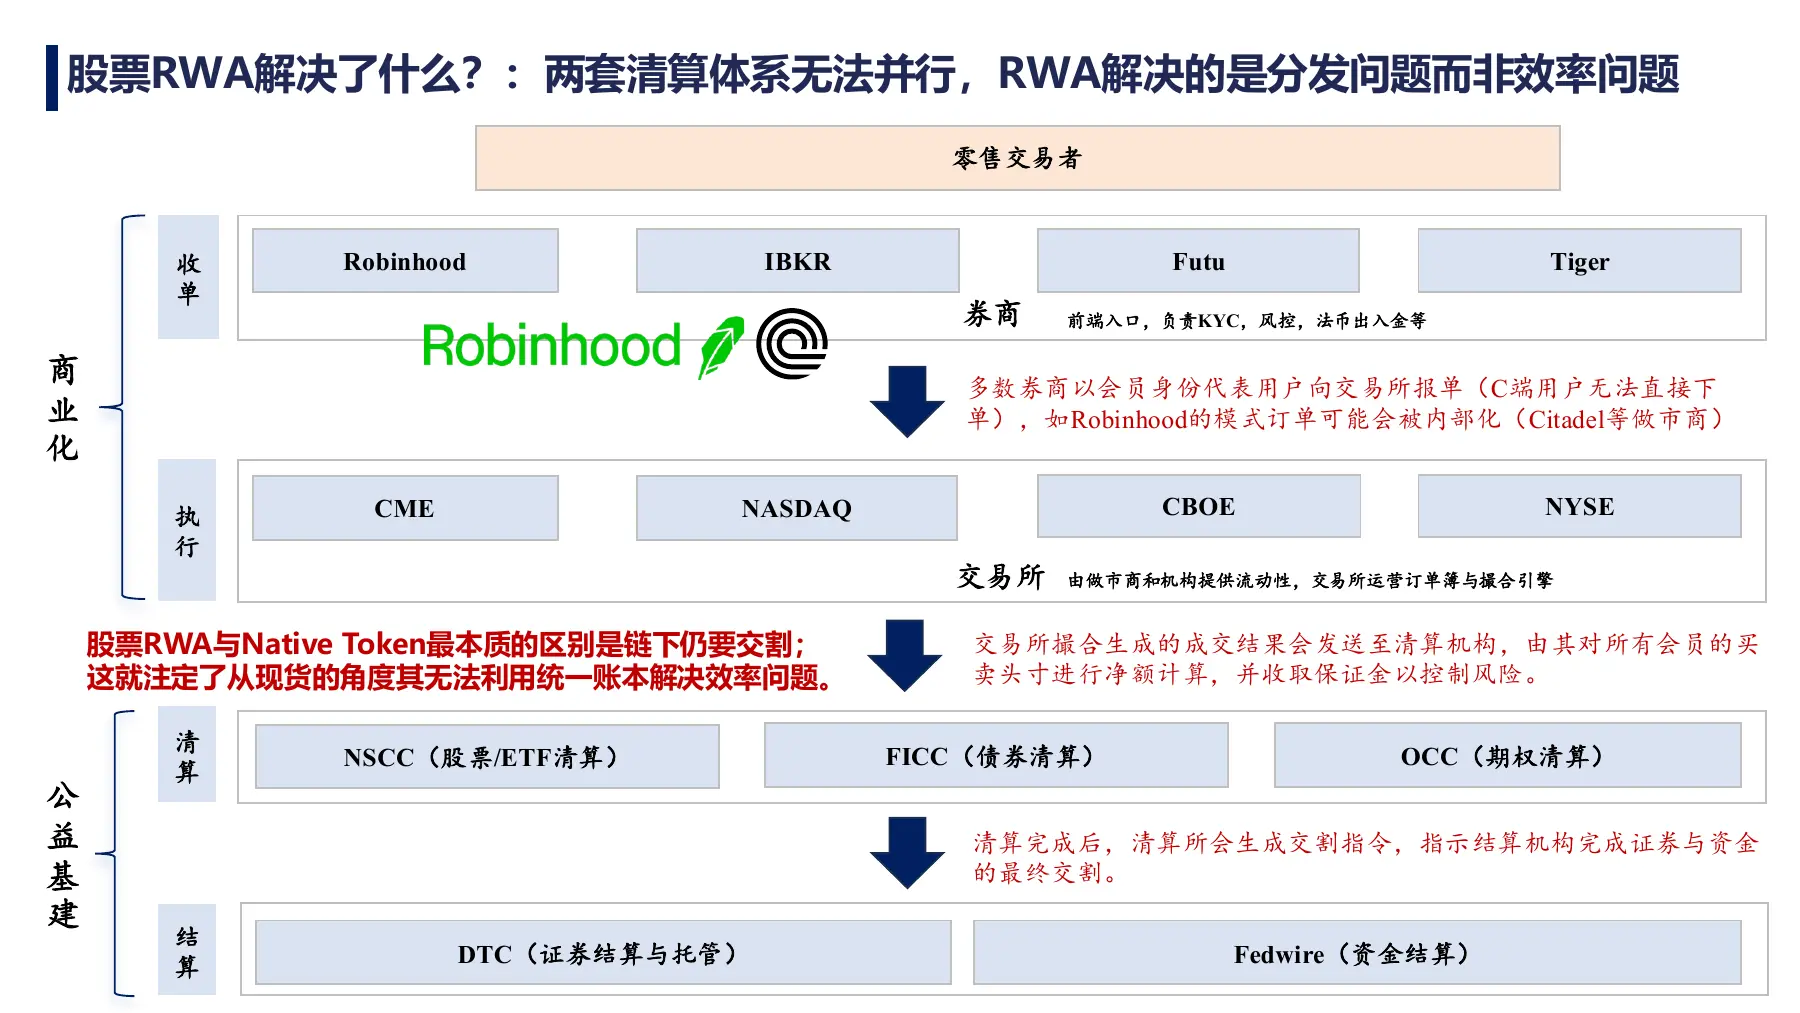 Off-chain Delivery and Dual Ledger of Stock Transactions · Original Slide Page 4 · Click to enlarge
2.4 Evolution: 1.0 / 2.0 / 3.0
| Stage | Timeline in Materials | Form and Representatives | Judgments in Sharing | |---------|-----------------|---------------------------------------------------------------|----------------------------------------| | RWA 1.0 | Starting in 2023 | Asset management firms like BlackRock, WisdomTree, UBS, Hashnote, etc., issue government bonds and ETFs on-chain through offshore SPVs. | Serving supply side rather than demand side, lacking user thinking. | | RWA 2.0 | Early 2026, volume starts around March | Perpetual contracts for Nasdaq 100, Nvidia, commodity futures on Hyperliquid; Binance, Bitget, OKX follow suit. | Previous rounds like FTX had U.S. stock contracts, but liquidity suppression stifled demand; this round's demand has been proven. | | RWA 3.0 | Sharing at that time | Binance connects brokers in off-chain apps to sell stock spot directly, no longer doing token mapping. | On-chain operations may become a hindrance; crypto is not an advantage, offshore is the advantage. |
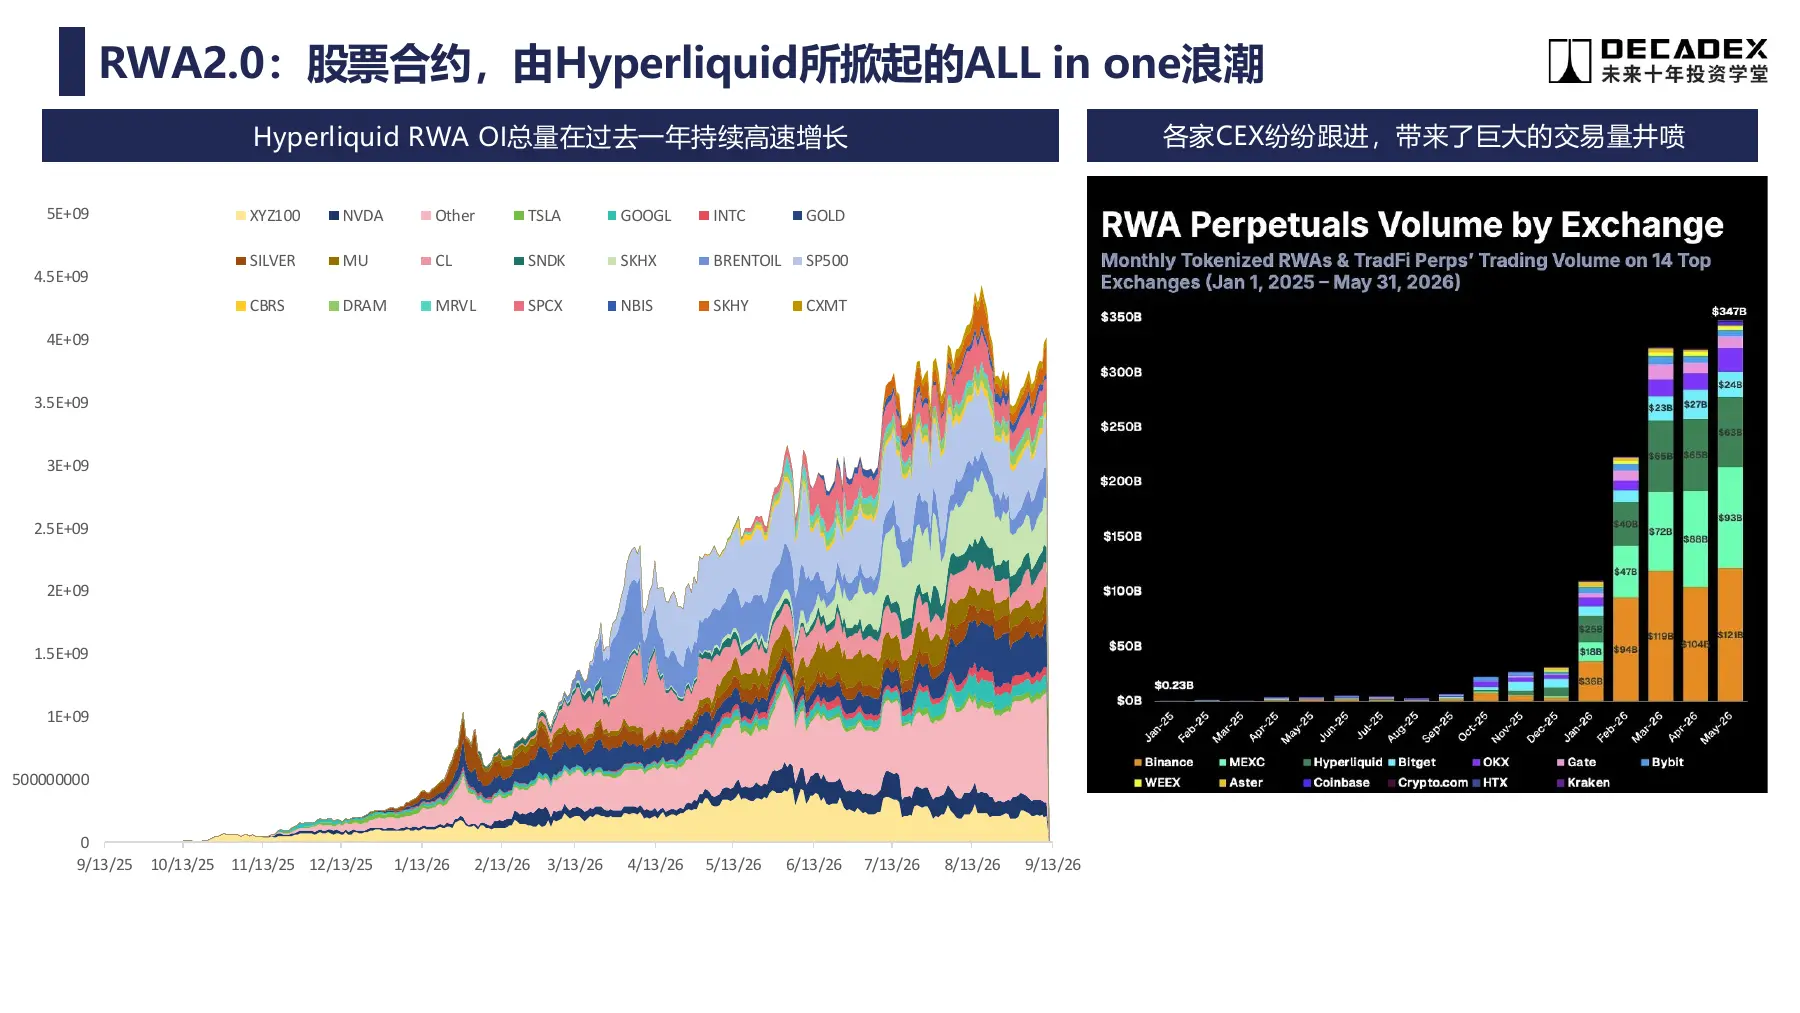 Stock Perpetual Contracts: Observations of RWA 2.0 in the Slides · Original Slide Page 7 · Click to enlarge
2.5 Timing: Money in the Market, Lack of Assets
- Crypto native projects are declining: Historical fundraising amounts of CryptoVC, the frequency of listings on Coinbase, and the total market value of altcoins outside the top ten are all decreasing (there was a recent spike, and the chart needs updating). Chinese Crypto Twitter is complaining about no one picking up altcoins.
- The total market value of stablecoins has remained flat since the bear market began (October 2025): money is still in the market, but there are no investable assets. Exchanges pushing RWA also carry anxiety—exchanges earn from transaction fees, not asset appreciation, so they can push any asset.
- BTC and QQQ were highly correlated from 2021 to 2025 (BTC is roughly equivalent to leveraged QQQ), but a divergence occurred in June to July this year (QQQ surged, BTC plummeted), during which RWA exploded.
- Two Open Questions: ① Did the launch of RWA siphon off native funds, or did the decline of native accelerate RWA? ② What does this mean for Crypto native in the long term? Will the total market of native continue to shrink, even falling below the previous round?
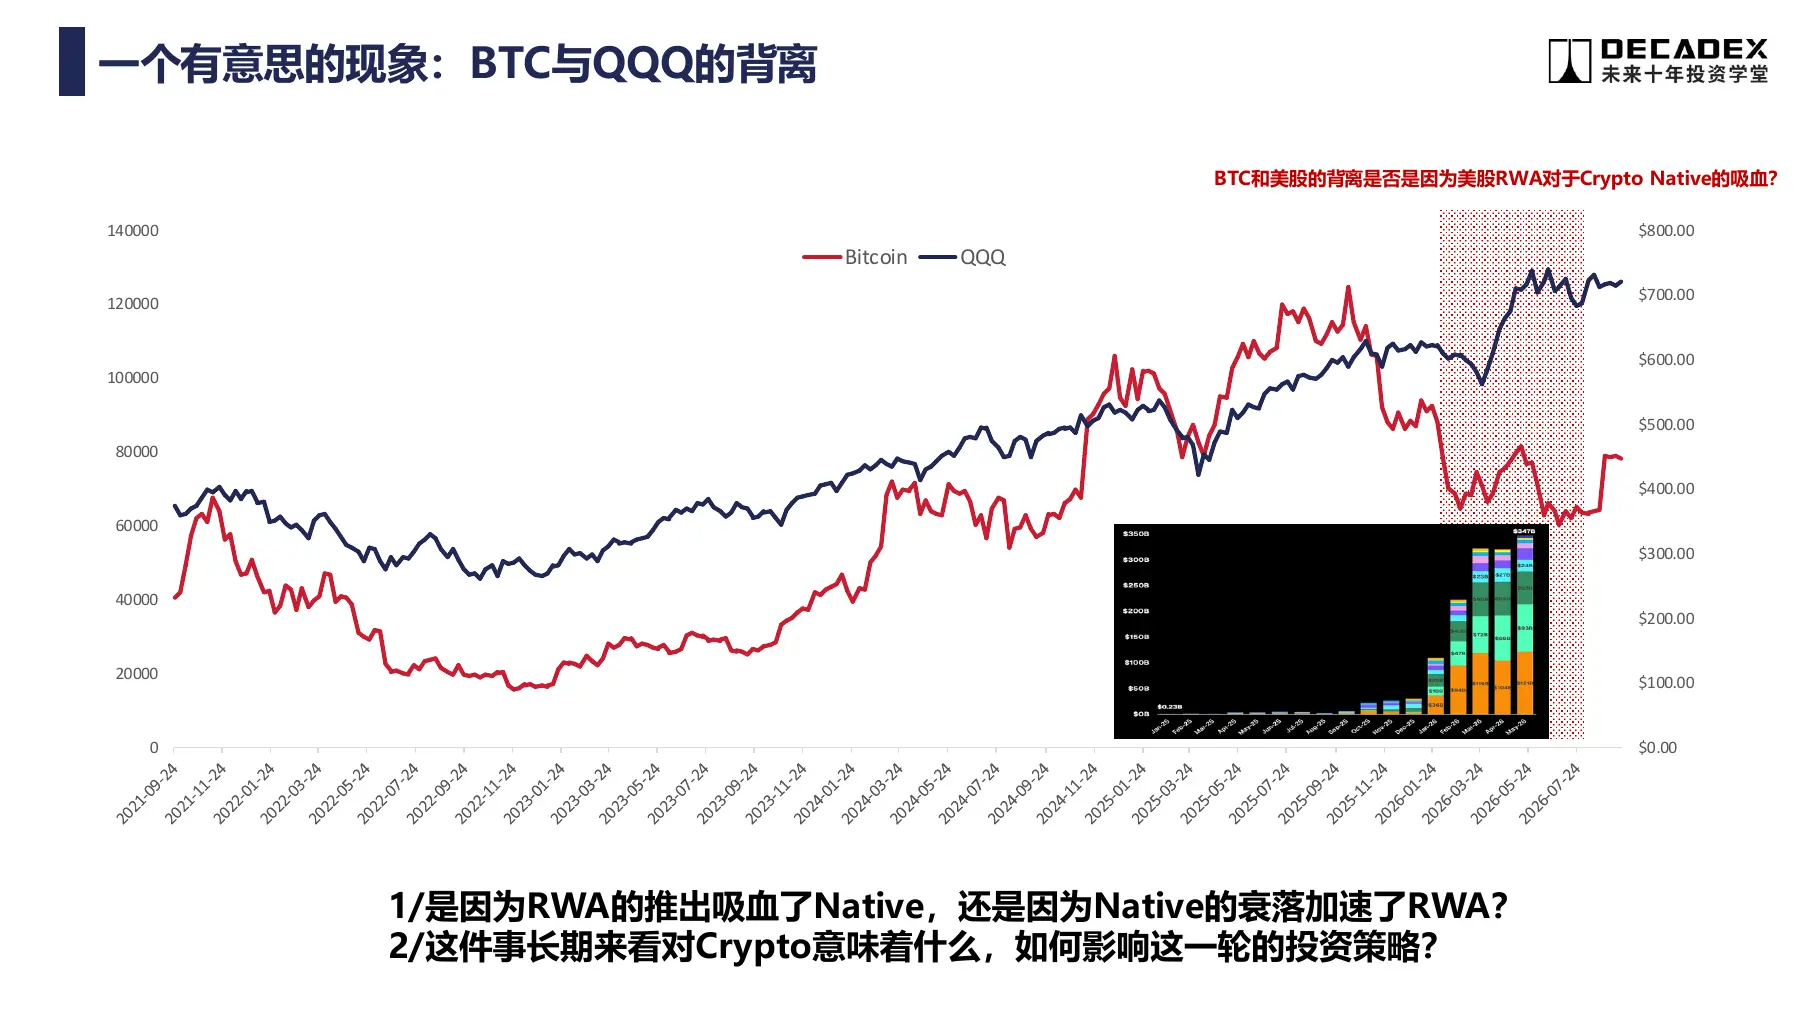 Divergence of BTC and QQQ: Open Questions in Sharing · Original Slide Page 9 · Click to enlarge
CHAPTER 03 On-site Discussion
3.1 Reasons for Divergence, Will Native Shrink?
- Kacey: The divergence began after October 1 last year, primarily due to the macro high-interest environment (around 3.5% interest rate); there is only so much money that can rotate between U.S. stocks and BTC. She is not optimistic about stock spots on CEX, but contracts are a huge advantage of crypto over traditional finance: institutions use 1x contracts as spot purchases, and the basis trading volume done by Jane Street on Binance may be larger than in traditional markets. The SEC has allowed financing below 500,000 dollars to be issued directly with on-chain stocks, and new stocks will gradually be issued directly on-chain. Altcoins and new assets will still exist; A-shares and Hong Kong stocks are also creating markets.
- Tron: The core is still distribution; as long as it is a quality asset, users will use it immediately. Crypto assets are being stockified: after Hyperliquid, more and more projects are using revenue to buy back and burn, equivalent to an on-chain IPO; such assets will become blue-chip.
- TW: In terms of quality assets, stocks are definitely greater than coins. CEX originally had both asset issuance and trading functions; after the new asset categories decrease, the issuance function will significantly weaken.
- YJ: Disagrees that the divergence is related to RWA. The volume of on-chain RWA perpetual contracts is insufficient to impact BTC; the divergence is mainly due to AI and semiconductor stocks, along with the siphoning effect of upcoming IPOs like OpenAI, Anthropic, and SpaceX.
3.2 Fees and Taxes
- Binance's stock spot trading fee is about 0.15% to 1%, around seven to eight dollars for 10,000 USDT, which is about 2-3 times that of IB. IB is the cheapest, has the best liquidity, and does not have to worry about regulation, provided one can open an account.
- TW: Non-KYC scenarios meet the needs of non-compliant regions, one of which is tax avoidance. U.S. capital gains tax is very heavy, so Americans do not sell stocks (for example, Kevin is reluctant to sell his stocks).
- YJ: Not reporting taxes on profits made from trading U.S. stocks on exchanges is definitely illegal. The IRS made it clear four or five years ago that on-chain transactions (NFTs, tokens) must be reported for taxes; currently, the volume is small, and the IRS does not yet have the willingness or resources to investigate. BN is not open to U.S. residents; if Hyperliquid enters the U.S., it will 100% connect with tax authorities. U.S. short-term and long-term capital gains taxes can exceed 50%; Europe is about 15%-20%, while Singapore and Hong Kong are very low. Therefore, tax avoidance is merely a regulatory arbitrage in the early, small-scale stage and will not be a core necessity.
3.3 Contracts, pre-IPO, and New Assets
- For those who can already buy stocks, why buy RWA? Summarized into two points: ① New gameplay (such as 100x leverage); ② Assets that cannot be purchased (such as unlisted DeepSeek).
- Contracts do not require the issuer or shareholders' consent, nor do they need a 1:1 mapping; they can be traded directly by opening a ticker, so it's fast. Pre-IPO contracts like Kimi have already gone live; essentially, it's like pre-market, betting on size, and it's a new asset in quotes. What cannot be sold off-chain cannot be sold on-chain either.
- Regarding decoupling and default risk: On-chain prices are determined by the liquidity of the pool, not by the real stock market, relying on whether the redemption channel is smooth to attract arbitrageurs to pull back the price. USDT and USDC have both decoupled; the core concern is the underlying reserves, so one must trust that the project party does not act maliciously. As long as the underlying is genuinely purchased, there are basically no issues; the price difference between on-chain and traditional markets over the weekend is the arbitrage space for market makers.
3.4 Settlement Speed: Understanding Blockchain from the Ledger Perspective
- On-chain, transactions settle immediately, and true delivery occurs; when stocks are transferred to you, they show up in your account, but they only truly belong to you after T+1.
- Within the same ledger, transfers are instantaneous (like internal transfers in Alipay, Binance UID transfers); cross-system coordination is needed (like transferring from Alipay to WeChat). The first principle of understanding blockchain is the ledger; in the traditional world, each entity has an isolated ledger, while blockchain has one ledger on-chain.
3.5 Vision: The Essence of RWA is Capital Efficiency
- There is no need to be overly concerned about current compliance; the core is what benefits and gameplay it can bring, and it can play a pioneering role.
- Case Study: An institution dealing in derivatives has moved its original options Delta strategy targeting BTC and ETH to Hyperliquid, specifically targeting stocks about to IPO (like Changxin Storage), packaged as discounted buy products for external sales. This is something that centralized exchanges cannot achieve off-chain.
- In his view, the essence of RWA going on-chain is capital efficiency (programmable, financial Lego), not distribution, because distribution can be replaced: Kraken has integrated Hyperliquid HIP-3, Hyperliquid is about to launch an Android app, and Robinhood Wallet can now directly buy stocks on-chain. There is no need to worry about entry issues in the medium to long term.
CHAPTER 04 Robinhood Chain
4.1 Positioning: Traffic Thinking vs ARPU Thinking
- Native exchanges in the crypto space (Binance, Hyperliquid, OKX, Bybit) addressing the RWA issue solve the ARPU problem: users no longer want to buy coins, so they switch to other assets to continue earning fees.
- Robinhood's chain addresses the globalization/traffic issue: China and Europe have not taken off, and using the chain eliminates the need to obtain licenses and push regulations in each region.
- Externality Investment Thinking: Robinhood invests resources in subsidies, and the biggest beneficiaries are not Robinhood itself, but smaller players like Uniswap, Fluid, Pulse, and Lighter (Lighter and Uniswap have recently increased by about 5 times). This is analogous to large companies investing in CAPEX: a large company might grow by 20 percentage points, while a computing chain grows by 10-20 times.
- Gameplay: Primarily stock-coin pairing (using stocks to buy memes, based on AMM), along with various launchpads, has taken away part of the meme market share from SOL, sparking a meme season.
- Vlad is determined to make the chain a business that can be discussed in financial reports, rather than a marginal innovative business; Robinhood's quarterly conference will continue to discuss on-chain derivatives.
- On-chain Snapshot: Robinhood's trading activity is now between Base and Solana. It is expected that this round of activity can reach the first tier, comparable to SOL, and TVL can benchmark against Base.
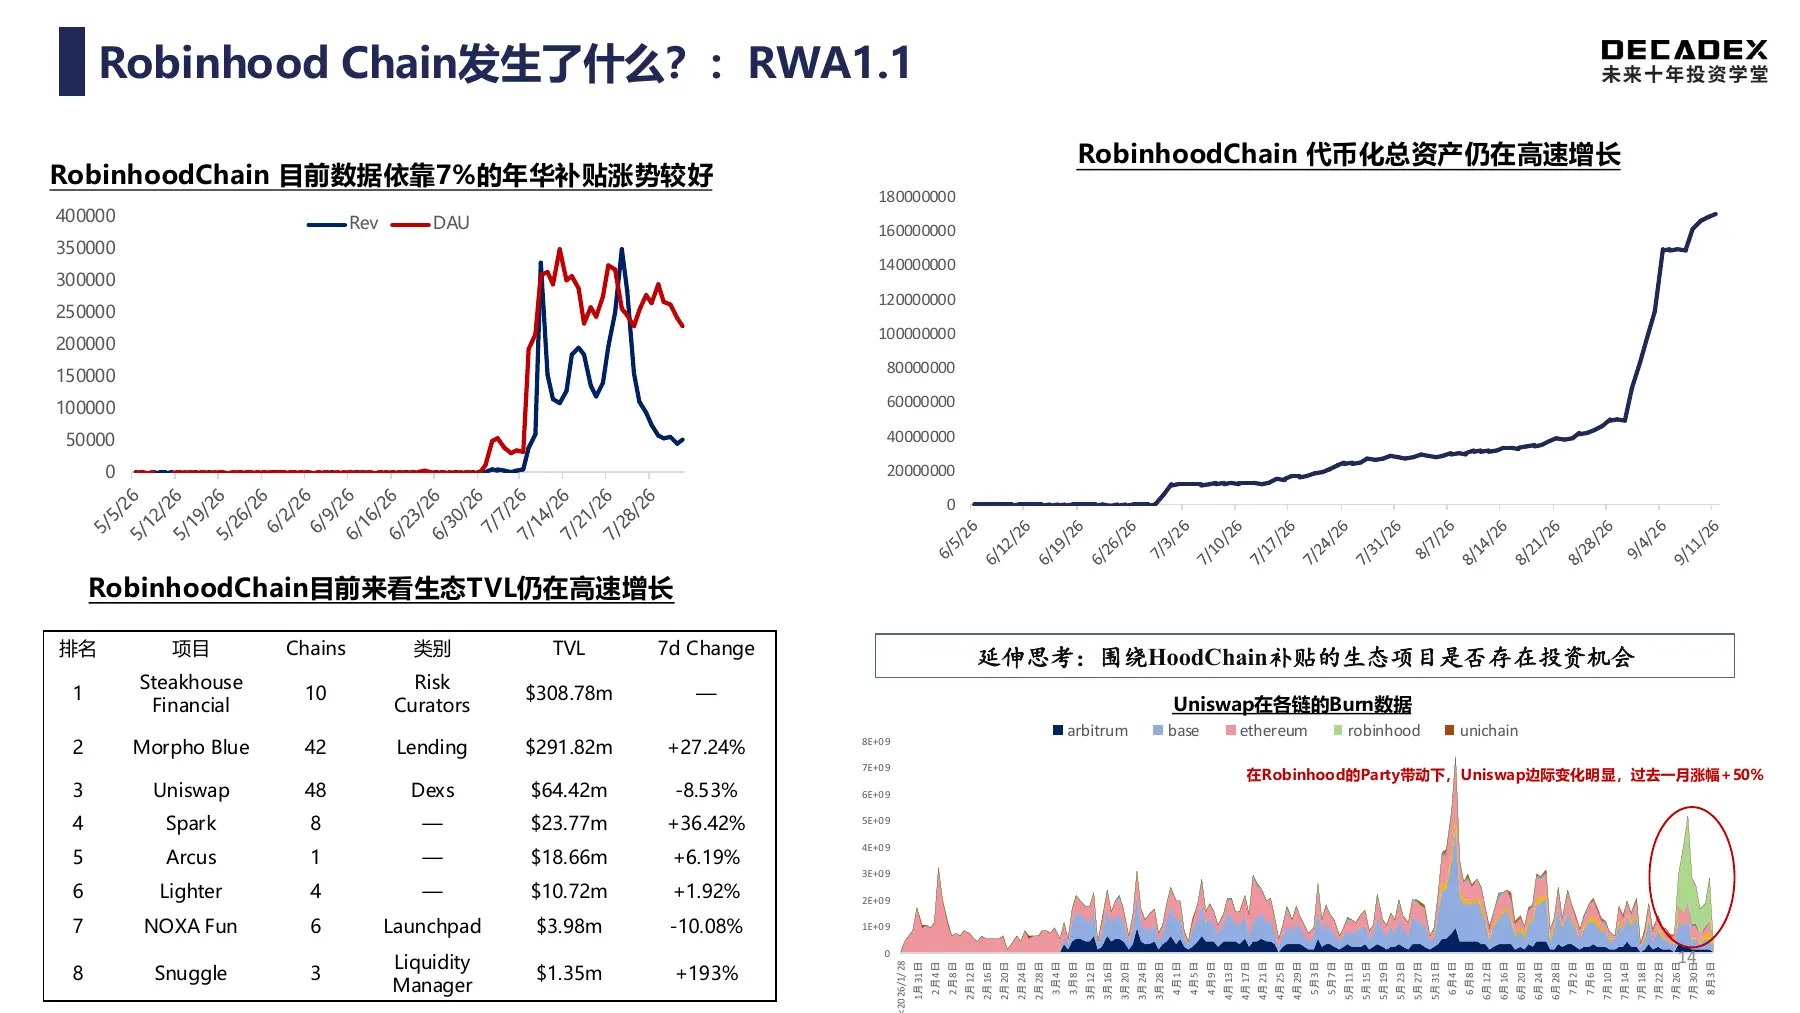 Products and Assets of Robinhood Chain · Original Slide Page 14 · Click to enlarge
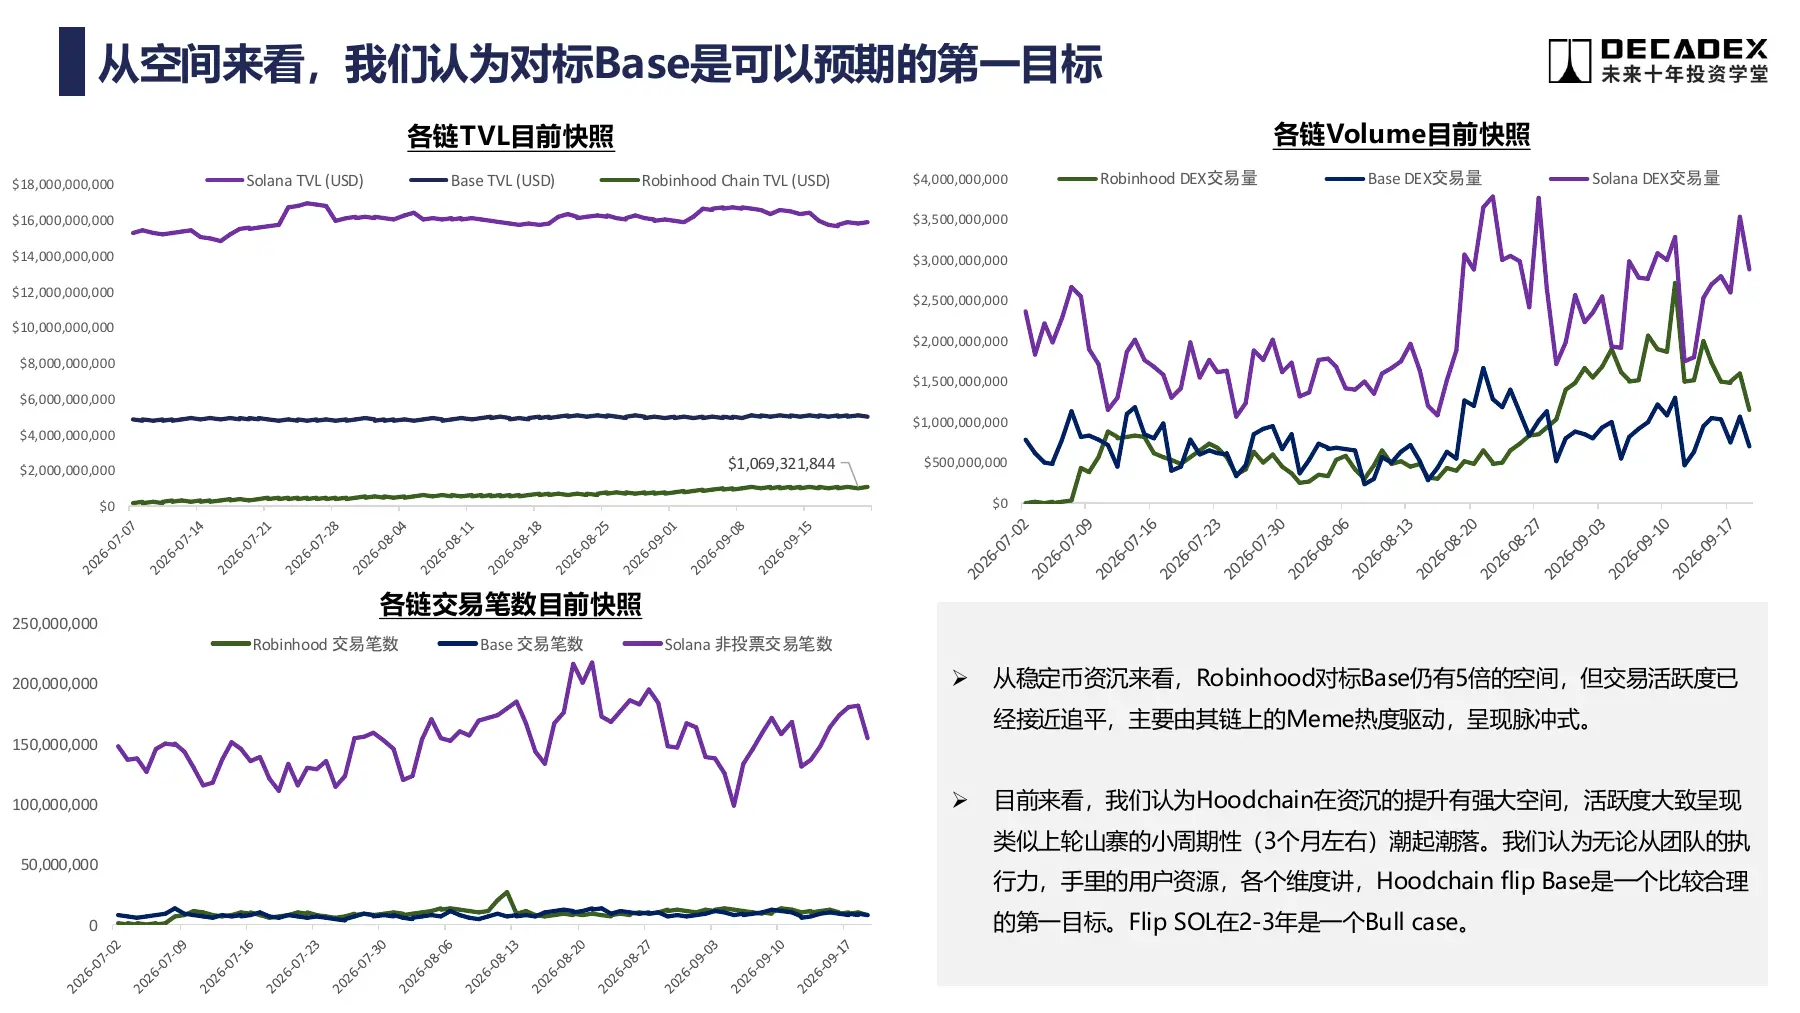 Comparison of TVL, Trading Volume, and Number of Trades · Original Slide Page 17 · Click to enlarge
4.2 What Cards Are Available and What Are Lacking
| Available Cards | Lacking Cards and Constraints | |--------------------|-----------------------------------------------------------------------------------------------| | Determination, strong product capability, and execution power | Lack of core applications in the native ecosystem. Solana has Jupiter, Pump.fun, Raydium; the main applications on Hood Chain are EVM-based DeFi like Uniswap, Morpho. | | Backing: Robinhood itself | As a publicly traded company under SEC regulation, expanding into on-chain US stocks may face compliance disputes. | | U.S. C-end user mindset | The material also mentions AMM exemptions and the company's political PR capabilities, suggesting the need for dynamic observation. |
Conclusion: Meme is just a means; RWA is the goal. Robinhood chain flipping Base is the base case, even the bear case.
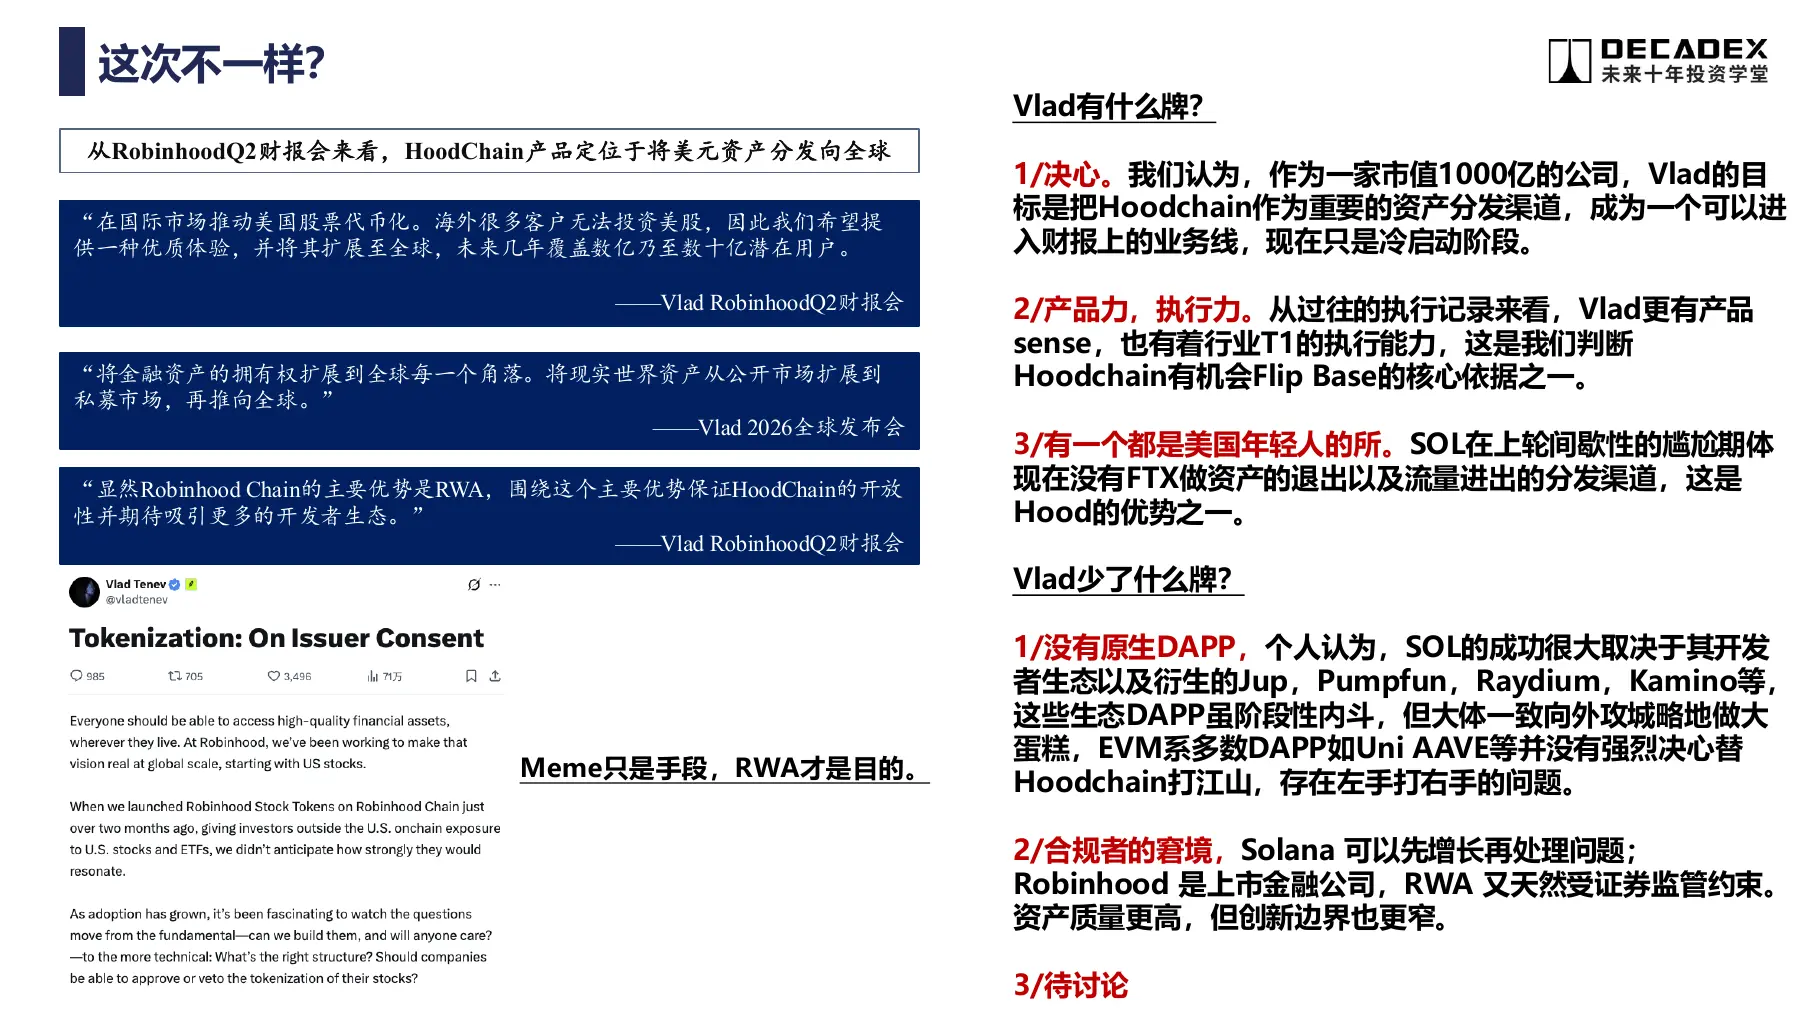 Advantages and Constraints of Robinhood · Original Slide Page 19 · Click to enlarge
4.3 Discussion on Robinhood Chain
YJ
- On-chain U.S. stocks have two layers: ① Clearing and settlement going on-chain is inevitable. Vlad has been pushing T+2 → T+1 → T+0, with Robinhood, Coinbase, Nasdaq, and DTCC promoting it from the top down, but the scale is uncertain; essentially, it is a faster SaaS for transaction matching. ② Entry going on-chain means distribution, and this layer does not necessarily have to be on-chain.
- Three reasons for Robinhood to pursue the chain: T+0; distributing U.S. stocks worldwide (previously collaborated with Baidu to enter China, also tried Singapore and the UK, but got stuck in regulations); Vlad's goal to democratize finance for all, allowing retail investors to trade pre-IPO assets monopolized by VC and PE.
- The North Star metric is TVL (corresponding to AUM off-chain, which is a core item in financial reports), followed by trading volume and MAU. He expects TVL to catch up with Base in 2-3 years, synchronized with this cycle.
- This round of memes is unlikely to reach the height of the previous round: The Trump coin has already set a cap; industrialization on the supply side, combined with AI enabling rapid coin issuance; declining faith on the demand side creates a vicious cycle. However, there will still be meme volumes in the range of $500 million to $1 billion. Vlad is just using the momentum from Solana to cold start and does not intend to make the chain a meme chain.
- The next step is to interface with regulators to bring more U.S. stocks on-chain, targeting non-U.S. users. There are about 23 million U.S. users, and growth has stagnated; those who can use it have already done so. Crypto accounts for about 20%-25% of Robinhood's revenue.
- Employee Perspective: The chain is not the company's top priority; the company is racing multiple business lines (credit cards, Trump account, pension accounts, previous prediction markets), and whichever performs well will get more personnel. Vlad has clearly listed the chain as a priority externally, but employees are not optimistic about it.
- Reasons for the failure of internationalization: When entering the UK in 2021, it was nearly successful, but the local prohibition of the PFOF model was cut at the last minute; after the GME incident, focus shifted to infrastructure; a restart is planned for 2024-25, with crypto products already pushed to Europe. The contradiction is that U.S. users do not need the chain, while regions like Europe that need the chain have a weak Robinhood brand. Once this issue is resolved, the chain can bring considerable revenue.
WY
- Institutions look at revenue and profit margins. The stock spot fee rate is hard to see; traditional brokers also rely on 0DTE options to pull profit margins, and relying solely on issuance and trading makes it hard to sustain a team.
- RWA memes may not be the best answer, but they represent an imaginative breakthrough: pulling up volatility based on the underlying stock increases both fee rates and trading frequency. After this wave, many traditional brokerage owners have come to seek him out.
- Retail demand on-chain: pre-IPO (before Changxin, SpaceX IPO), high leverage (10x Hynix, 5x QQQ). Futu's prediction market volume has exploded rapidly, especially for 15-minute contracts.
- If he were Robinhood, the North Star would be profit margin; the priority of the prediction market is higher than that of the chain because explosive events like the World Cup can be pushed quickly, while it is hard to create equivalent explosive events on-chain.
- The upper limit of memes is essentially the upper limit of the backers (referencing Telegram-related projects at about $2 billion), which ultimately needs to be converted into marketing budgets and revenue. The logic of pulling volatility to increase profit margins has a high ceiling, but the correct answer has yet to emerge.
Tron
- Robinhood chain has strong externalities, but from the on-chain addresses, most users have migrated from other chains, with few new users.
- The stock purchase volume on BSC mainly comes from Alpha points and arbitrage, with very few stock purchases driven by memes; those who really want to buy stocks can open a US stock account to solve it.
- The real benefit of the stock meme campaign is to accelerate ecological integration: launchpad, App Store, lending, etc., are all interconnected at once.
- Robinhood's advantage is that US small-cap stocks can be directly on-chain; however, Ethereum's DeFi protocols and liquidity are hard to shake, currently not posing a significant threat to BSC. The significance of the chain lies in its permissionless nature.
CHAPTER 05 Robinhood Company and Valuation
5.1 Brokerage Framework
- Brokerage = Traffic × Conversion Rate: Traffic is measured by DAU / funded accounts, and conversion rate is measured by ARPU. The areas where the company focuses indicate its goals: issuing credit cards is to increase ARPU, while developing the chain is to capture traffic.
- In the consumer sector, the team is more confident in brokerages than in food and beverages. The team's research path is: altcoins → chains → coin chains → finance. In a few years, there may no longer be a term like blockchain, just called Fintech.
- New brokerage track in seven words: Liquidity, traffic, compliance. Research on Futu and Robinhood starts from these seven words.
5.2 Thinking About Robinhood from Charles Schwab
- MAU has not exceeded 2021; this batch of young users in the US has reached saturation.
- Revenue is divided into two parts: Trading revenue shows significant cyclicality, with a surge in 2021 driven by Crypto and options, and a decline of 60%-70% in 2022-23; starting in December 2025, Crypto business will shrink, mainly relying on prediction markets to sustain. Asset income (net interest, asset management) has a compounding nature, with the underlying logic being excessive issuance of dollars and continuous asset appreciation.
- Charles Schwab had about 70%-80% trading revenue from 1993 to 2000, while Robinhood is currently around 60%. In the long term, trading revenue will definitely have a ceiling, and the biggest beta in the long run is assets. Charles Schwab captured the baby boomer generation and internet traffic, while Robinhood captures the millennial generation and mobile internet.
- Traffic first, liquidity follows. From the perspective of asset income, Robinhood is a growth stock, while from trading income, it is a cyclical stock.
- The phase when Charles Schwab truly outperformed the S&P was during the high growth period of users and trading revenue from 1994 to 2000; afterwards, asset income increased, but it did not outperform again.
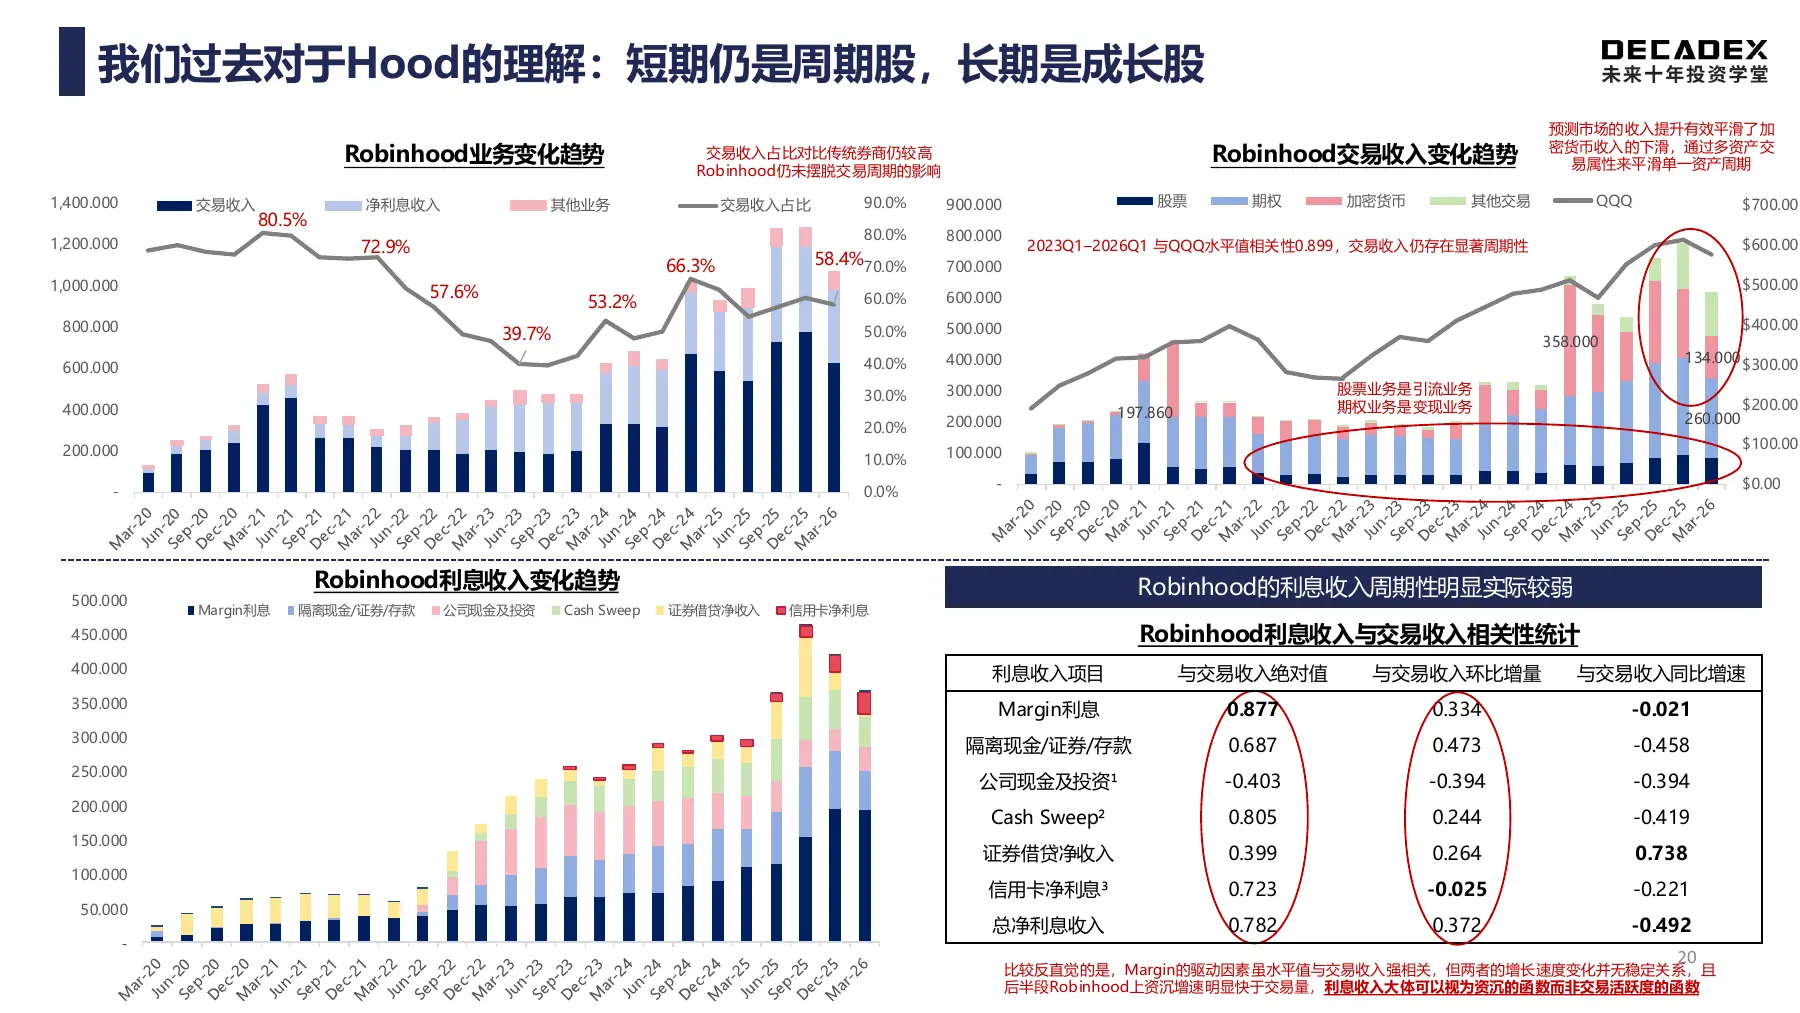 Trading Revenue and Asset Income · Original Slide Page 20 · Click to enlarge
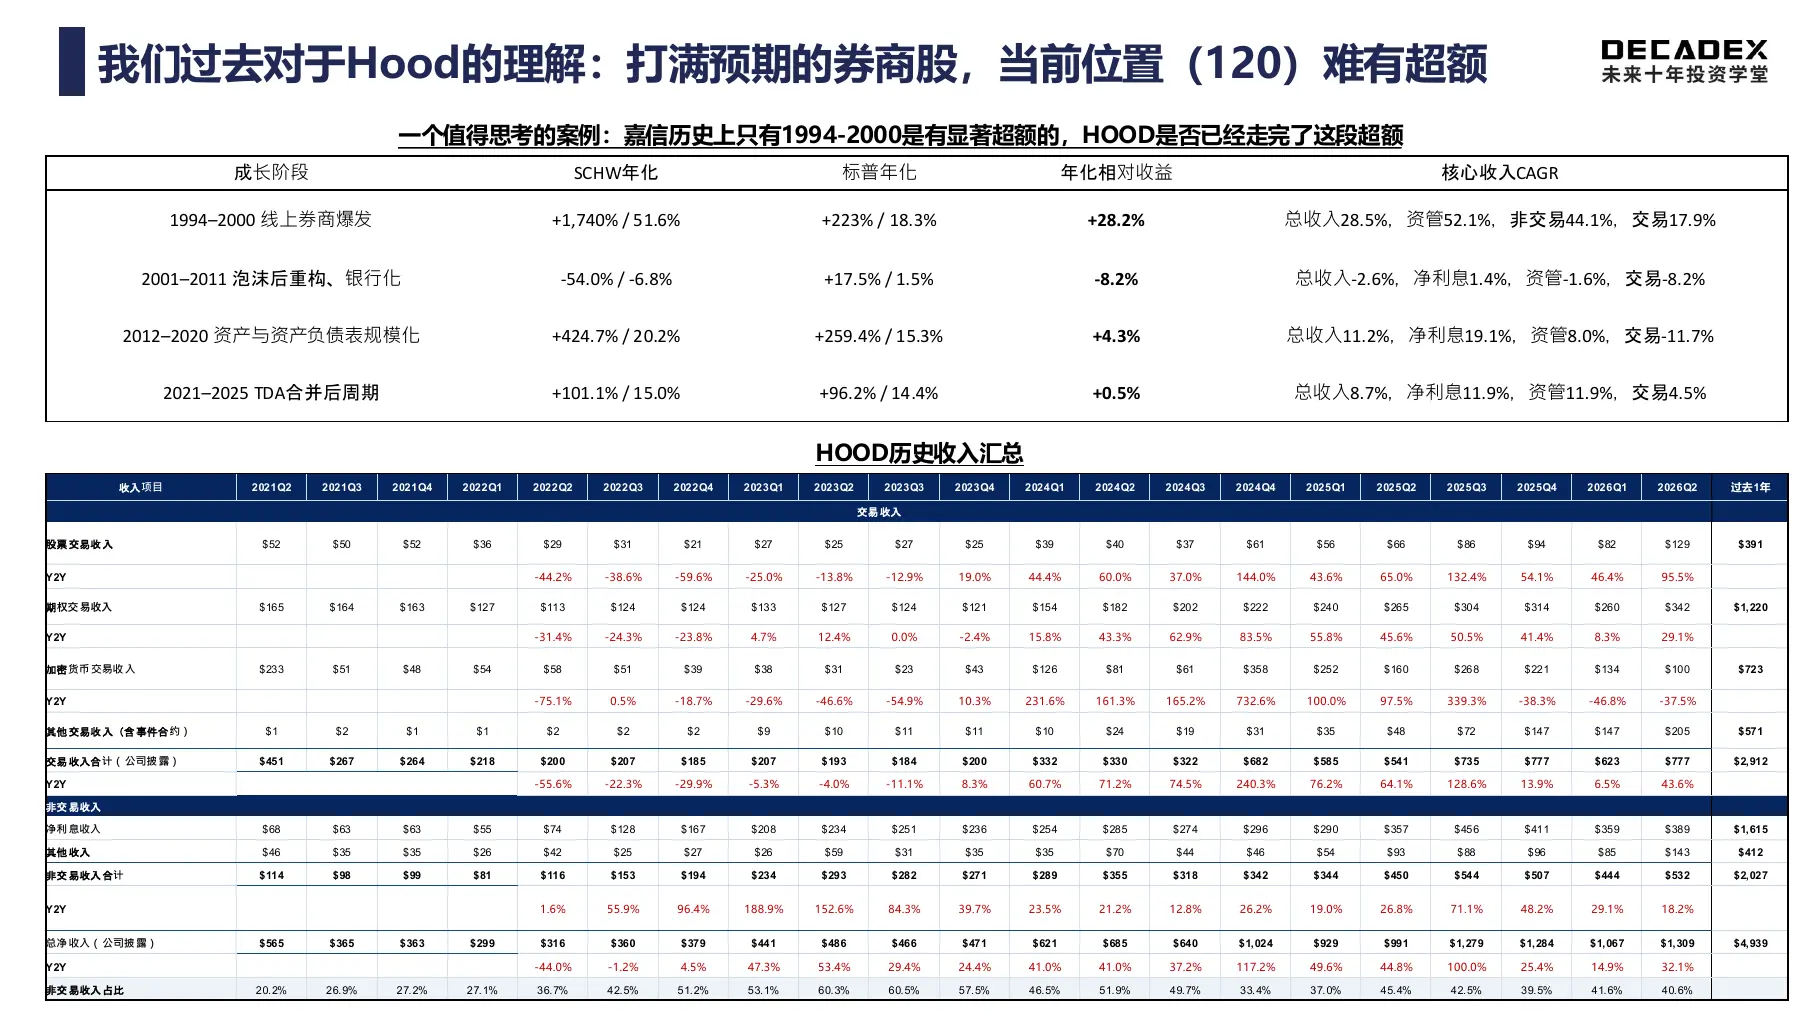 Charles Schwab's History and Robinhood's Reference · Original Slide Page 22 · Click to enlarge
5.3 Investment Ideas
- YJ: Robinhood will become the only super finance app for all in the US in the next 10-20 years, but it follows the US stock market; now is not a good entry point, wait for a significant drop in the US stock market and a decrease in trading volume before buying.
5.4 Valuation Page
| Key Figures | Current Metrics in Share | Forecast / Reference | |-------|----------------|-------------------------------| | Funded Accounts | 13.5 million | Approximately 32-33 million in the next two years (based on accounts, not users) | | ARPU | Approximately $187 | Approximately $300; Charles Schwab's ceiling is about $1000 | | Revenue | Nearly $5 billion in 2025 | About $10 billion in 2 years, at most not exceeding 3 years | | Market Cap Ceiling | Currently $107.2 billion | About $300 billion at the peak of brokerages (considering inflation) |
- If internationalization is hindered, the main driver will be the increase in ARPU (issuing bank cards is essentially about monetizing existing users).
- In the future, every earnings report will focus on four numbers: User count, ARPU, revenue, corresponding market cap.
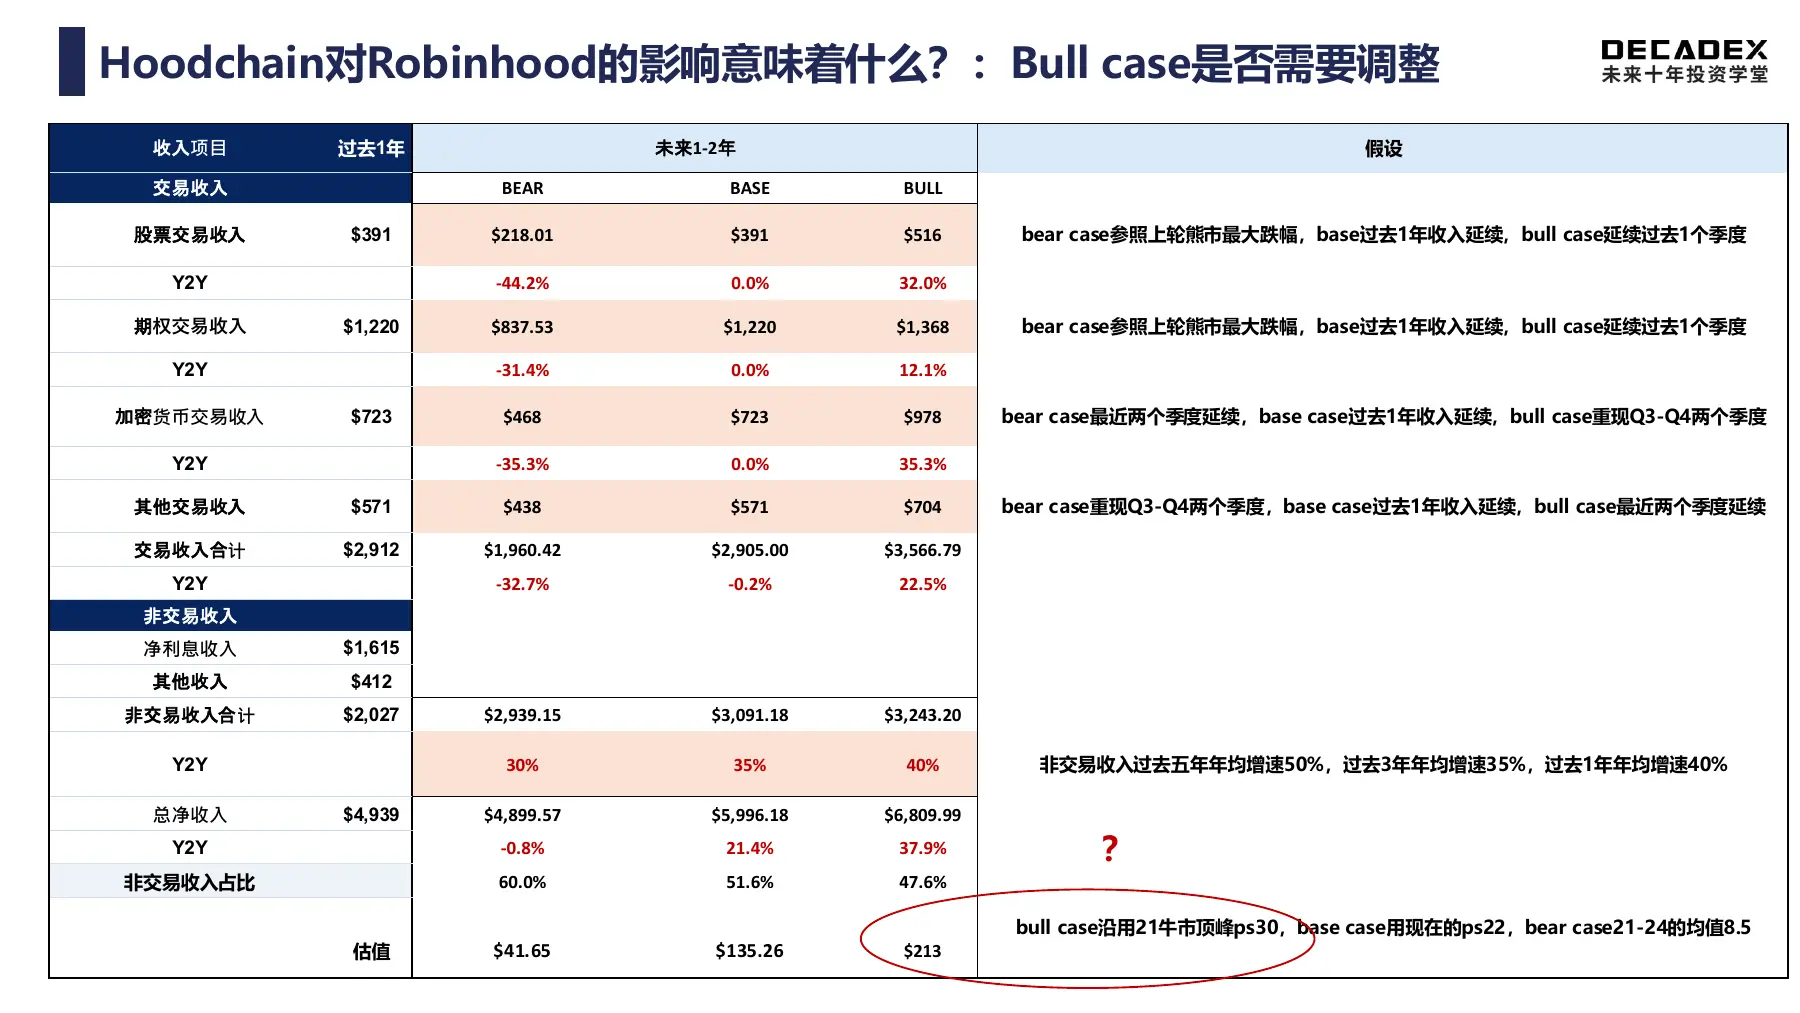 Robinhood Revenue and Valuation Scenarios: Assumptions in the Presentation · Original Slide Page 23 · Click to enlarge
CHAPTER 06 On-Site Opinions and Portfolio
6.1 Using Compliance as a Boundary
- Looking at these platforms from three dimensions: traffic, liquidity, and team execution. Compliance is key: if the Democratic Party comes to power in the midterm elections, it may crack down on non-compliant exchanges, posing a black swan risk. Non-compliance is used to increase sharpness (Hyperliquid, Binance), with rapid scaling and high efficiency, providing short-term alpha.
- Reasons for selecting these four platforms: RWA is essentially old assets, homogenized; with no asset differentiation, the platform's compliance, brand, and liquidity will concentrate towards the top.
6.2 Portfolio
| Guest | On-Site Expressed Portfolio | Logic | |--------|---------------------|-----------------------------------------------------------------------------------------------------------------------| | HB | BTC + Circle | At the most fundamental level, blockchain only has two businesses: BTC and stablecoins; timing in Crypto is more important than stock selection, making several trades in a cycle. | | YJ | BTC + Circle + HOOD | HOOD is a foundational stock, too high taxes to sell; new positions should wait for a significant drop in the US stock market; on-chain assets like ETH, UNI, Lighter, and Pulse can be bought, with little alpha difference. | | Kacey | Ethereum + Circle | Robinhood's growth lies in internationalization and on-chain; new liquidity enters from Ethereum and USDC; Hood Chain uses Arbitrum architecture, has no native token, which may bring incremental growth. | | Vision | "All in Ethereum" | Infrastructure like the sorter for 2022-24, OP Stack, Arbitrum Orbit, etc., will be realized on RWA; technological advancements but no increase in valuation, focusing on the Glamsterdam upgrade. The materials also mention that Robinhood pays about 10% fees to Arbitrum. |
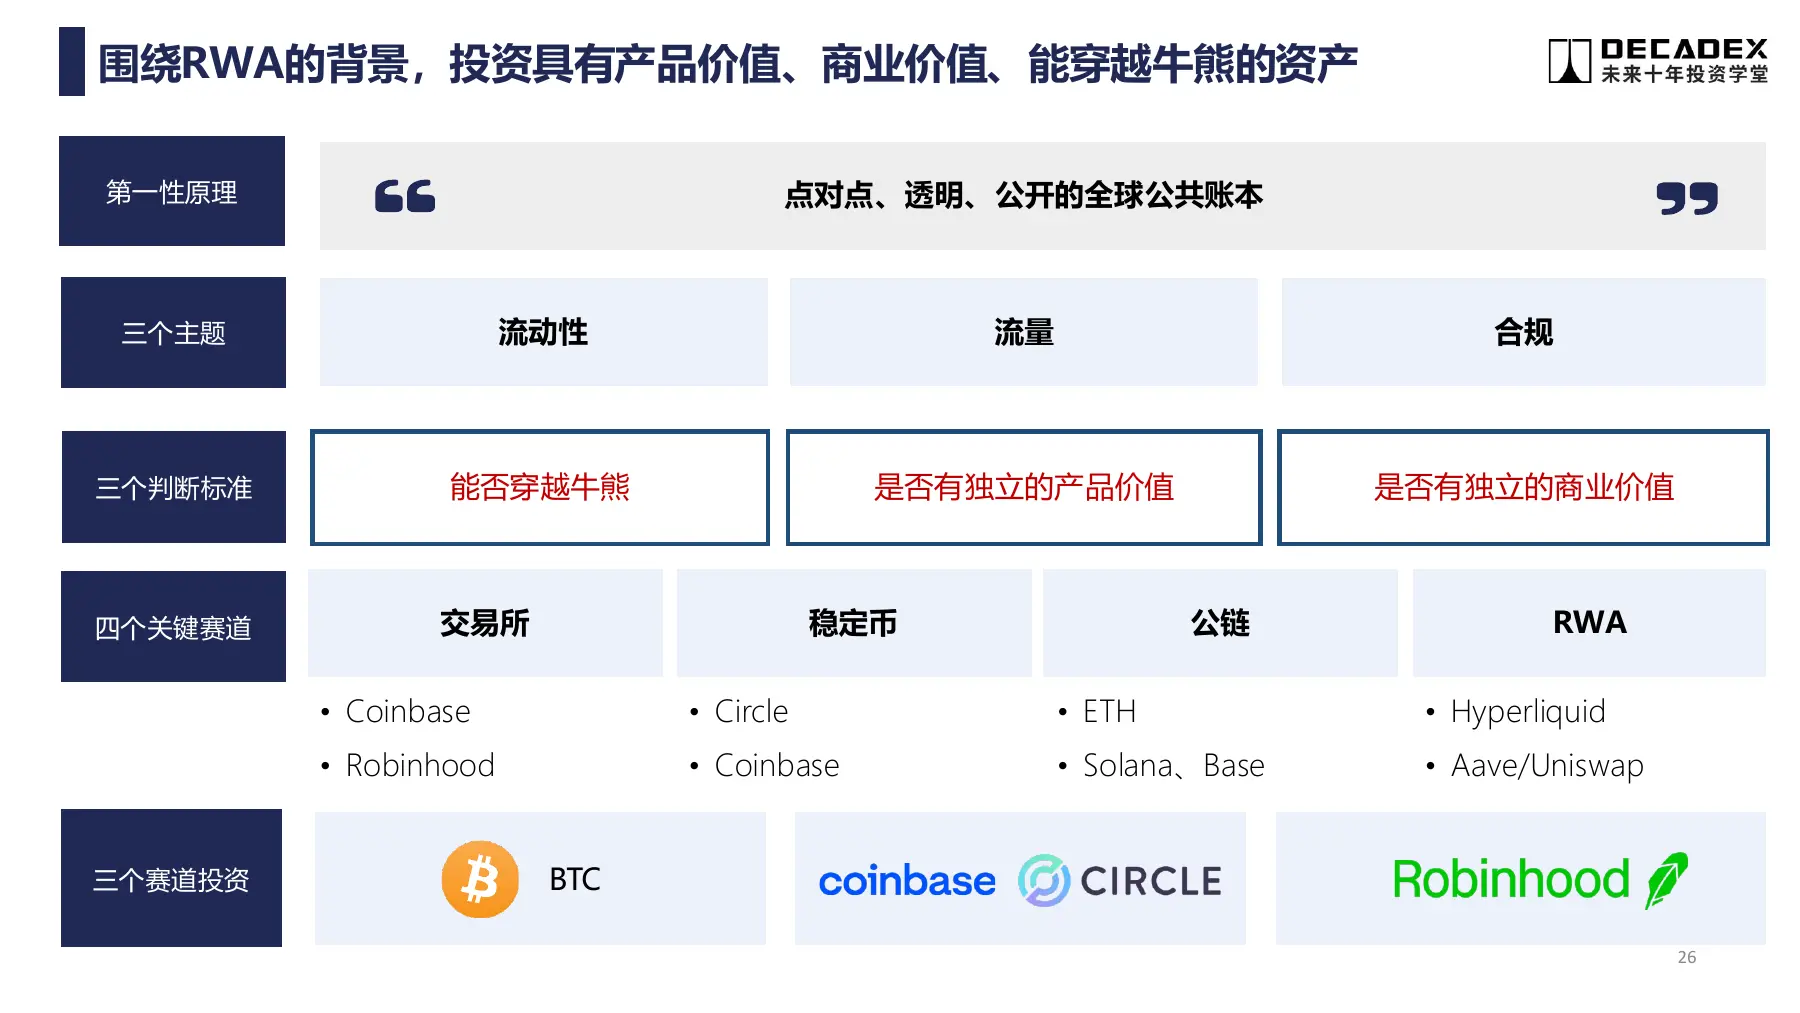 Asset and Platform Research Framework in the Context of RWA · Original Slide Page 26 · Click to enlarge
 Risk warning
Popular articles





