The "Meme Factory" has surfaced; how does the harvesting assembly line of Robinhood Chain operate?
 Core Viewpoint

 The methods of continuous token issuance and centralized control of opening prices are not uncommon on various platforms; it's just that here they are dressed in the guise of stocks and real estate.
Author: Zhou, ChainCatcher
On September 22, the token DEED launched on the issuance platform Pons of Robinhood Chain, and within less than a day, its market value evaporated by more than 90%.
Since its launch in July, Robinhood Chain has become one of the most active token issuance platforms. According to independent statistics from Pons Ledger, Pons alone has issued nearly 900,000 tokens. With such a high density of token issuance, the collapse of a new coin is not surprising.
However, after on-chain analysts traced the funds of DEED, they discovered that the same group had orchestrated dozens of token issuances over about two months, extracting approximately $18.43 million in total. Let's take a look at how they operated.
1. Profits from the last round of harvesting pay for the next round of launch
DEED claims to be a real estate vault on Robinhood Chain, stating that holders can share rental income from a portfolio of apartments after costs are deducted. On September 22, DEED launched on Pons, and its market value once surged to $4.23 million.
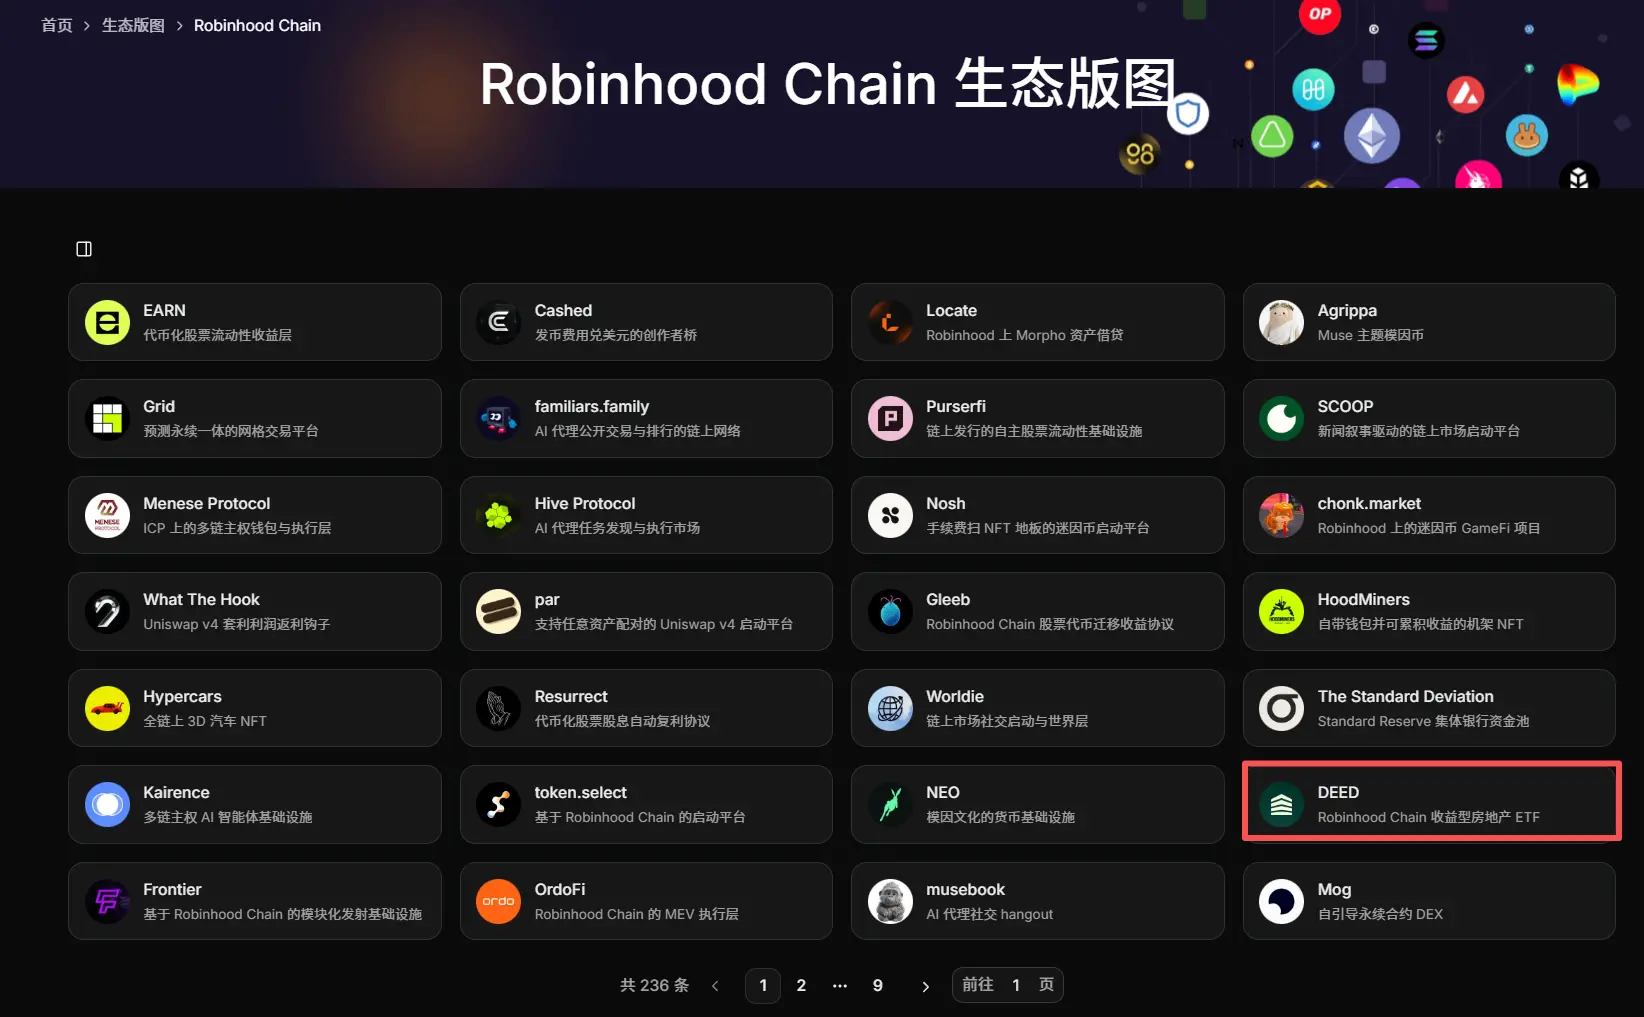
However, the hype lasted for less than a day. On September 23, Onchain Lens detected that DEED was suspected of a Rug Pull. 110 associated wallets once controlled about 86% of the token supply and extracted approximately $700,000 in funds, while the creator also received a creator fee of 68.5 ETH, worth about $188,900. At this point, DEED's market value had fallen to about $55,000, a drop of about 98.7% from its peak.
According to on-chain analyst Wazz, DEED is not an isolated incident. The funds behind it came from another token previously issued by the same group.
The story begins with DRAFT from a week ago. On the evening of September 14, 98 wallets holding DRAFT transferred 179.88 ETH to the same address within three seconds, and this money was subsequently transferred in full to a wallet starting with 0x9d06, where it stayed for a week.
On the morning of September 22, this money began to prepare for the launch of DEED. 0x9d06 first transferred out 50 ETH, and two minutes later, 20 ETH of that arrived at DEED's funding wallet. Sixteen seconds later, this funding wallet distributed 15.98 ETH to 50 addresses through a batch transfer, including the creator of DEED and 25 wallets that were pre-set to be exempt from the platform's anti-sniping tax.
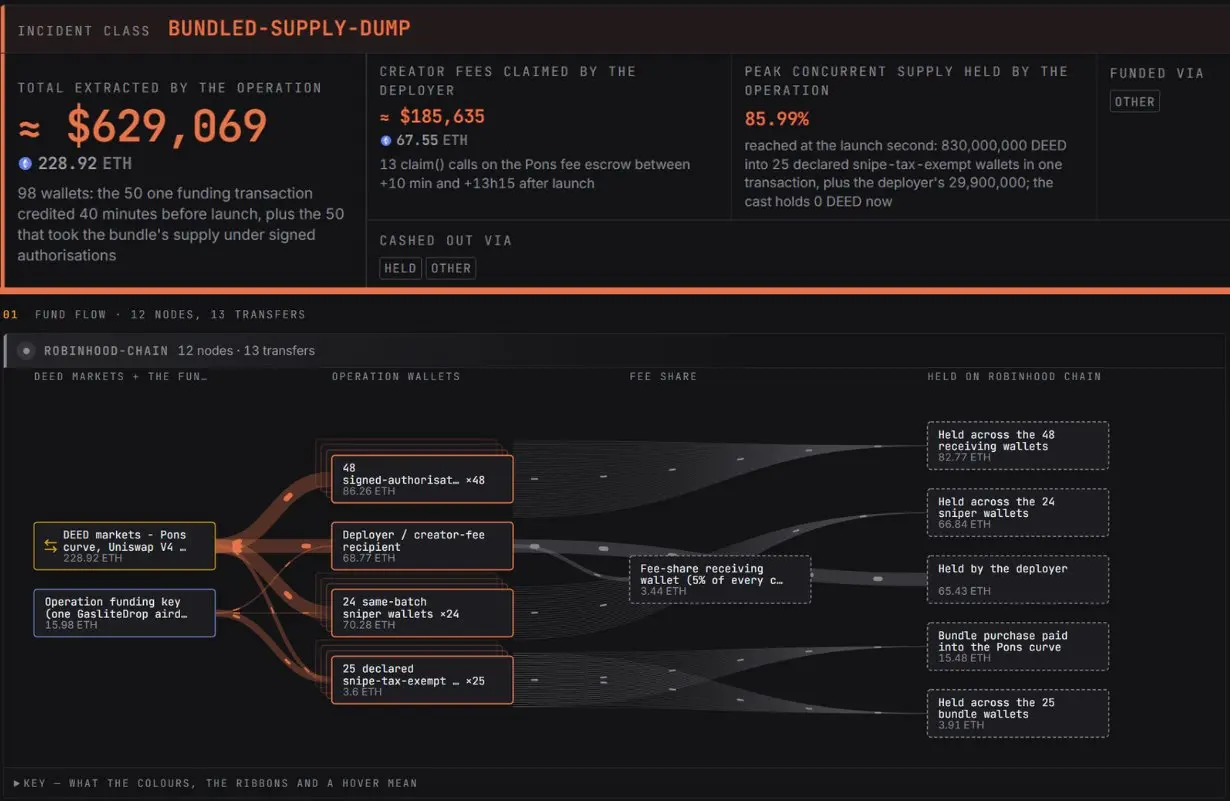
Forty minutes later, DEED launched. The first buy after the launch concentrated the positions for these 25 tax-exempt wallets. By the time the buying was completed, the creator and this batch of wallets held about 86% of the supply.
One second later, they began to sell, and the chips were subsequently dispersed to more wallets for gradual offloading. By the time Onchain Lens issued a warning, this round of harvesting had already been completed.
The connection between DRAFT and DEED is just a microcosm. Wazz found that the same rhythm repeated itself repeatedly over the course of two months.
Before each token issuance, the group prepared dozens of wallets and listed them as tax-exempt. Once the token went live, these wallets would take most of the chips within one or two blocks. When external buyers entered the market, they would gradually sell out, with the funds collected into a few addresses, becoming the starting capital for the next token.
Wazz traced 45 issuances along this funding chain. Additionally, four issuances had their starting funds signed by the same private key, and another four had the proceeds from sales pooled into the same collection address. Ultimately, he attributed 53 issuances from July 10 to September 21 to the same group, most of which were issued through Pons V2.
To amplify profits, the group also repeatedly used the same name. On the same day that 0x9d06 funded DEED, it also funded another token also called DEED. PINK, CRUMBS, and DEED each issued three times within about a day. Wazz believes that the group first uses tokens with the same name to harvest the traffic brought by the hype, and then reveals the real contract address.
According to Wazz's estimates, these 53 issuances extracted approximately $18.43 million in total, but this figure accounts for the funds taken from the market by the group, with counterparties including retail investors, other traders, and bots, which does not equate to the total losses of retail investors.
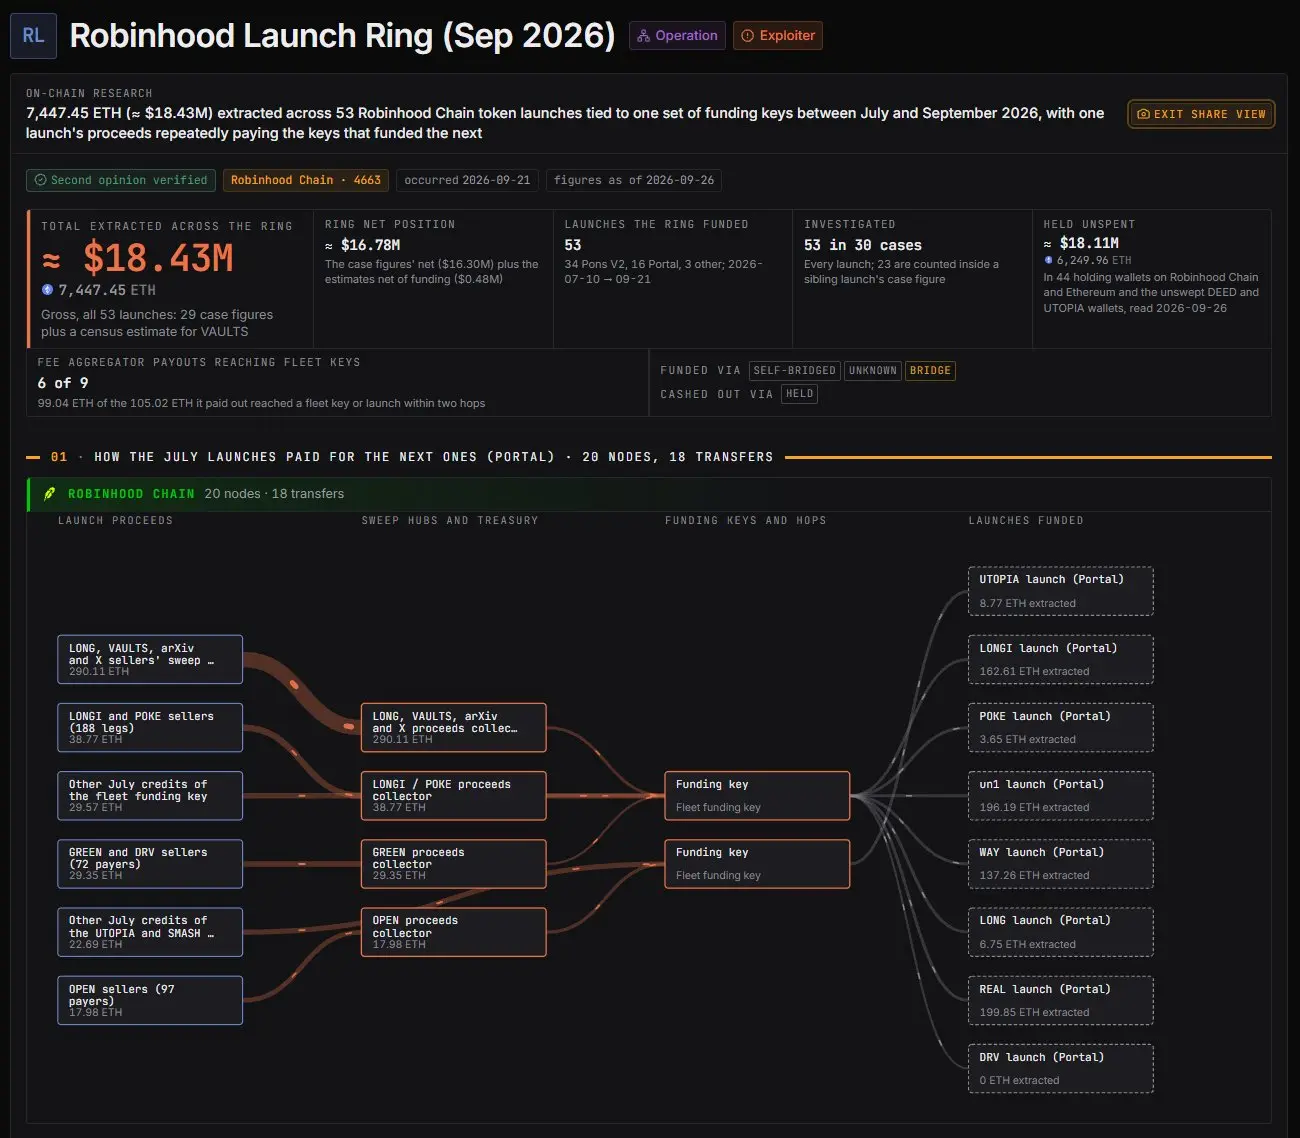
As a clue, DEED's single issuance scale is not large. The highest extraction amounts were from CRUMBS and LEGS, approximately $3.12 million and $2.90 million, respectively. Wazz stated that most of the funds remain on-chain in the form of ETH and cannot be frozen.
2. Anti-sniping tax blocked bots but did not stop those who obtained exemptions in advance
The previously mentioned tax-exempt list is key to the repeated harvesting. It comes from a set of rules designed by Pons to prevent bots from front-running.
After a new token launches on Pons V2, it first trades on a joint curve, where the more people buy, the higher the price goes. Once the curve is sold out, the token automatically graduates into the Uniswap v4 pool, with liquidity permanently locked. Pons documentation shows that graduated tokens do not have the functionality to withdraw liquidity at all.
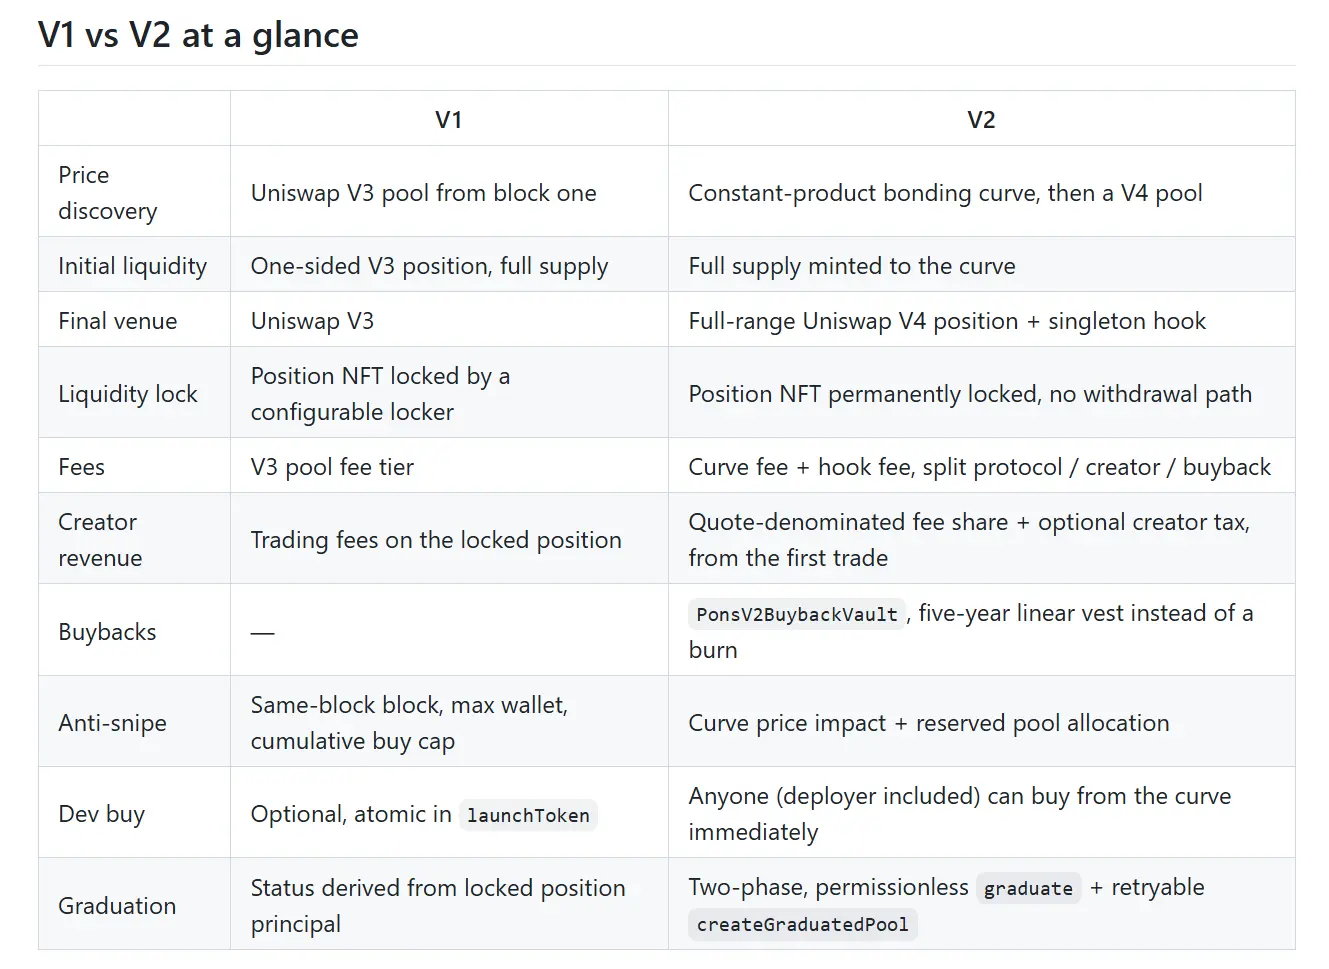
This design blocks the old route for project parties to withdraw liquidity and run away, but it does not control who can buy chips at launch.
In the first few seconds after a new token goes live, it is easiest for the most monitored bots to buy in first. To counter this, Pons V2 has set an anti-sniping tax. Buyers after the launch must pay a tax of up to 99%, which decays to zero in about five seconds, with the rate at about 25% at one second and about 3% at two seconds.
This tax is enough to make it unprofitable for bots, but the rules simultaneously leave a loophole. The token issuance address and the creator's fee address are automatically exempt from tax, and the issuer can additionally specify up to 32 tax-exempt addresses when creating the token. Pons provides the rationale in its documentation that it is to facilitate the team in distributing the launch purchases across multiple wallets.
In other words, as long as the issuer writes their own wallet into the list in advance, they can build positions tax-free during those few seconds when everyone else has to pay high taxes.
In the issuances listed by Wazz, nine since the end of August have shown the same pattern. The creator exempted 15 to 25 wallets from the anti-sniping tax, and then a single transaction concentrated the buying for them, directly buying out the curve and pushing the token into the Uniswap pool. After the launch, the holding ratio of the creator and tax-exempt wallets was between 82% and 86%.
These nine launch purchases also have a common point, all passing through the same unverified contract created on August 28. Wazz stated that this contract belongs to a commercial bundling tool with many unrelated users, and it has been used in 25 of the 53 issuances.
Additionally, he discovered at least two consecutive token issuance groups that could not be directly linked to this case.
On September 28, the security agency GoPlus disclosed the discovery of a high-risk fraudulent Meme factory on Robinhood Chain, with a transaction volume exceeding $9 million in the past 30 days, involving hundreds of fraudulent Memes.
This Meme factory follows a different route, allocating tokens to a large number of new addresses with only 4 to 11 transactions, and then selling them in segments through Pons V2's auxiliary contracts and Uniswap routing, creating the illusion of multiple independent traders.
In the ten samples listed by GoPlus, each token only utilized 3 to 8 new wallets, with a single token extracting 2 to 13 ETH. The individual scales are not large, and the proceeds from sales are similarly pooled into a collection address for funding the next round.
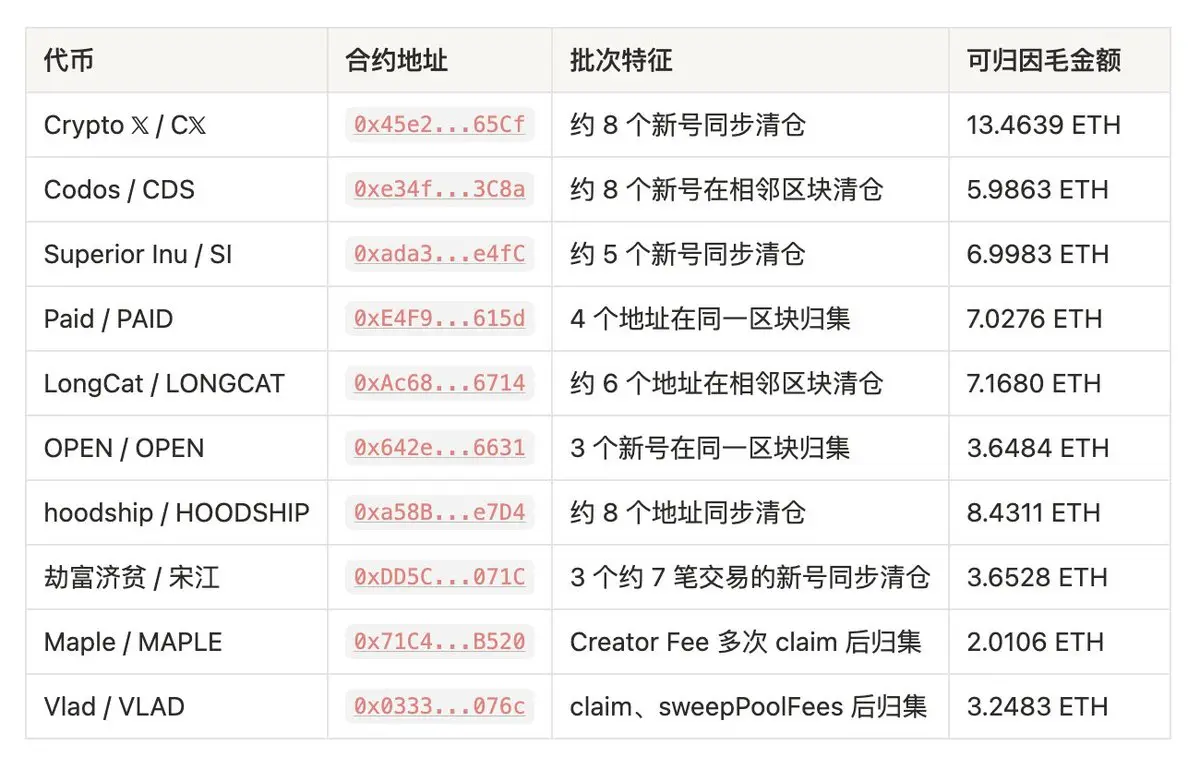
GoPlus statistics show that the total inflow and outflow of the collection address's last 400 transactions is approximately 3,589 ETH, about $9.49 million, which represents a two-way flow and does not indicate net profit. GoPlus pointed out that both cases used a large number of wallets to hide the real concentration of holdings and did not rely on withdrawing liquidity or prohibiting sales. Currently, there is no evidence to suggest that the two are the same group.
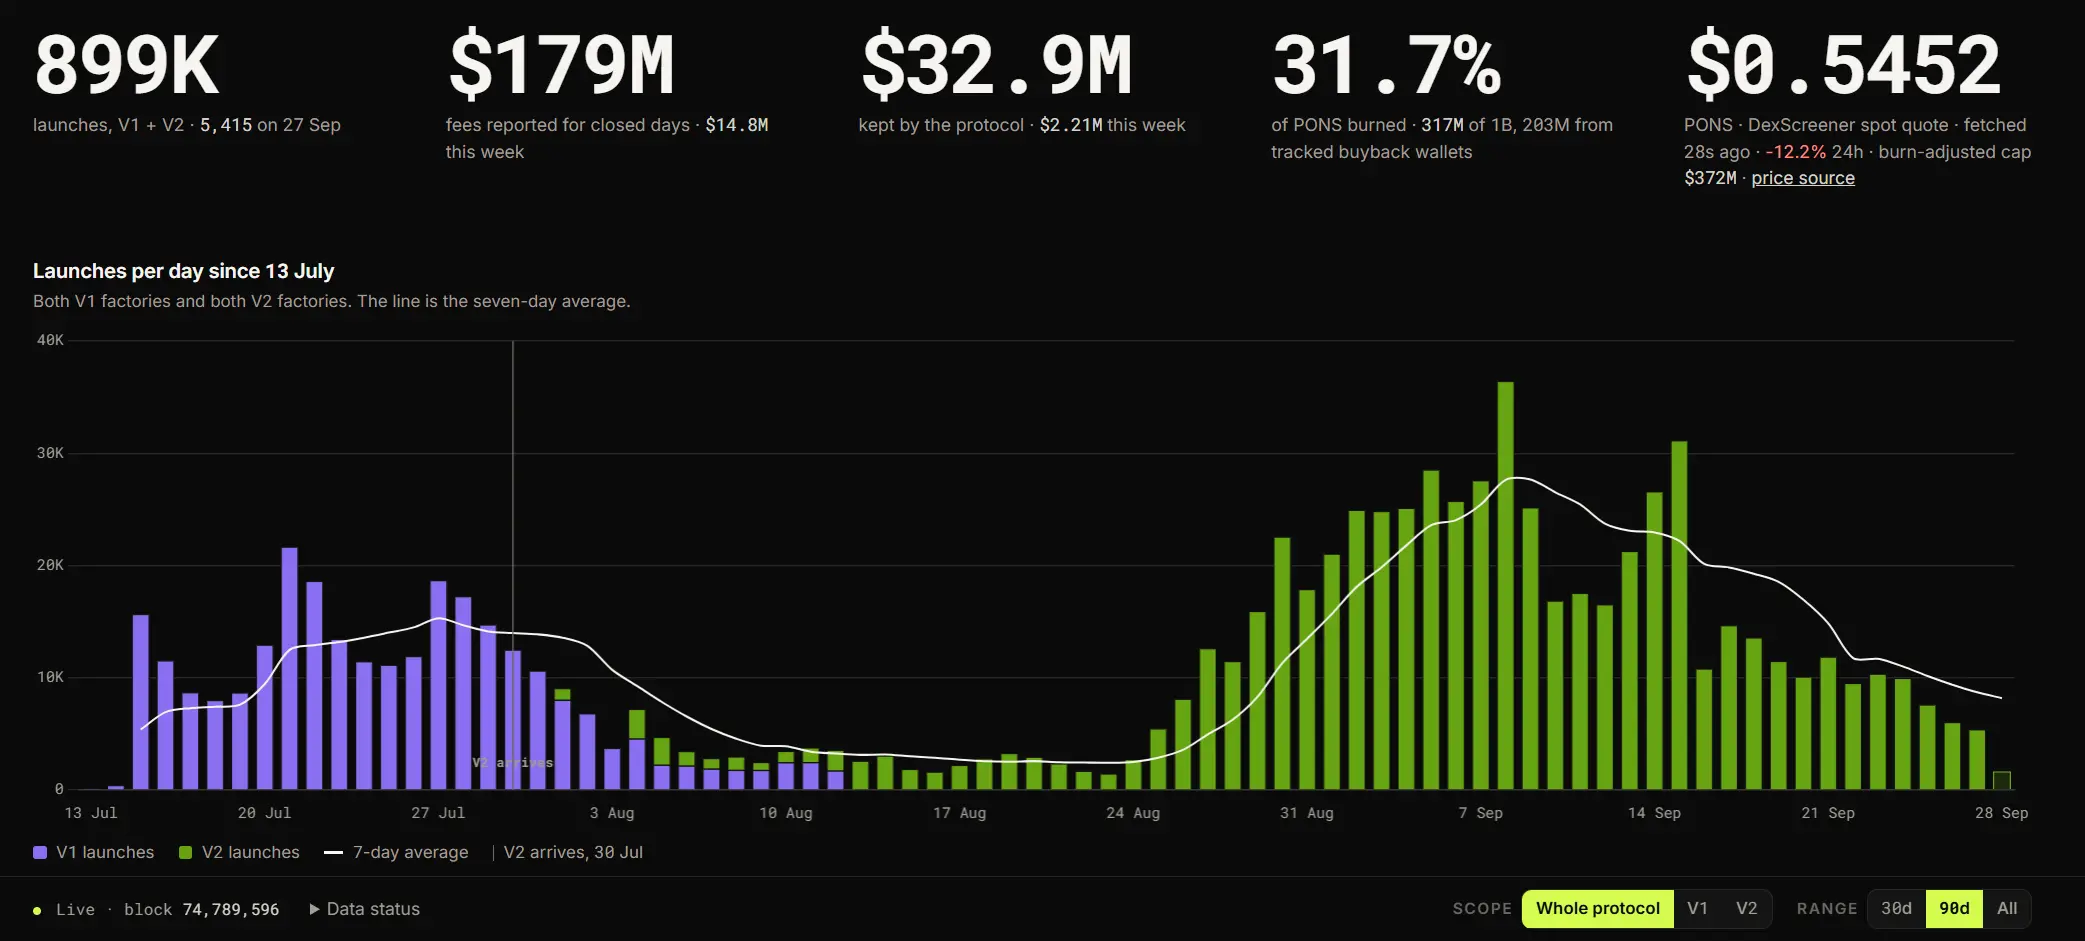
The reason why a large number of new wallets are inconspicuous is related to the token issuance ecology of Robinhood Chain. According to Pons Ledger, from July 13 to September 27, Pons alone issued approximately 899,000 tokens from about 453,000 addresses. Only about 1.5% of V2 tokens sold out the curve and graduated successfully.
On the peak issuance day of September 8, among the approximately 27,000 addresses participating in token issuance, about 90% had never issued a token before. In a daily influx of tens of thousands of new tokens and new addresses, dozens of one-time wallets are difficult for ordinary buyers to identify.
3. Stock disguise and creator revenue sharing make token issuance a business
Looking back at DEED's apartment vault, this type of packaging is not uncommon among the group's tokens.
Among the tokens listed by Wazz, there are names like Pink Sheets, Stock Miner, Openbell, EQUITY BROKERS, etc., with Pink Sheets being the old term for the U.S. OTC market; the highest extraction amount, CRUMBS, claims to convert shopping receipts into stock token rewards.
This layer of disguise is inseparable from Robinhood Chain's own positioning, which markets tokenized stocks as a selling point, and Pons V2 also allows issuers to directly price new tokens with stock tokens.
GoPlus previously scanned the issuance records of Pons V2 and found that in about 32.4 million issuances within 11 days, 32% were directly priced with official stock tokens. In summary, the combination of Meme coins with stock tokens has become a common play.
JINQIAN has pushed this layer of outerwear to the extreme. In early September, this meme coin was launched on the Robinhood Chain through a private token issuance factory, with a trading pair using the Farmmi stock code FAMI. Farmmi is a mushroom supplier listed on NASDAQ, and the name JINQIAN is derived from the money mushroom mentioned in its annual report.
According to Nansen, this FAMI is not an official stock token and is not associated with Farmmi's shares. However, the name is enough to evoke associations in the market. On September 2, during U.S. stock trading, Farmmi's stock price surged by about 350% at one point.
Previously, GoPlus published a Robinhood Chain Risk Report showing that the entire supply of this FAMI token is held by the operator. JINQIAN can only be traded in pairs with FAMI, and retail investors must first buy FAMI from the operator each time they purchase JINQIAN. After the hype subsided, the operator withdrew about $2.06 million in stablecoin.
The packaging is responsible for bringing buyers in, while the creator's share allows this business to continue in rounds.
On Pons, most of the transaction fees from each trade are distributed to the token creators. According to pons ledger, as of September 27, Pons has accumulated transaction fees of about $180 million, of which about $147 million flowed to the creators.
For groups that continuously issue tokens, this is another source of income beyond selling chips. In the samples listed by GoPlus, there are two tokens whose earnings come from collecting creator fees multiple times. The cost of issuing a token is very low, and once a token becomes popular, the proceeds from selling and the creator fees are enough to cover the costs of many previous attempts.
Conclusion
Data shows that the craze for issuing tokens is waning. According to pons ledger, the daily token issuance on Pons dropped from about 36,000 on September 8 to about 5,400 on September 27. Revenue and expenses are also significantly declining.
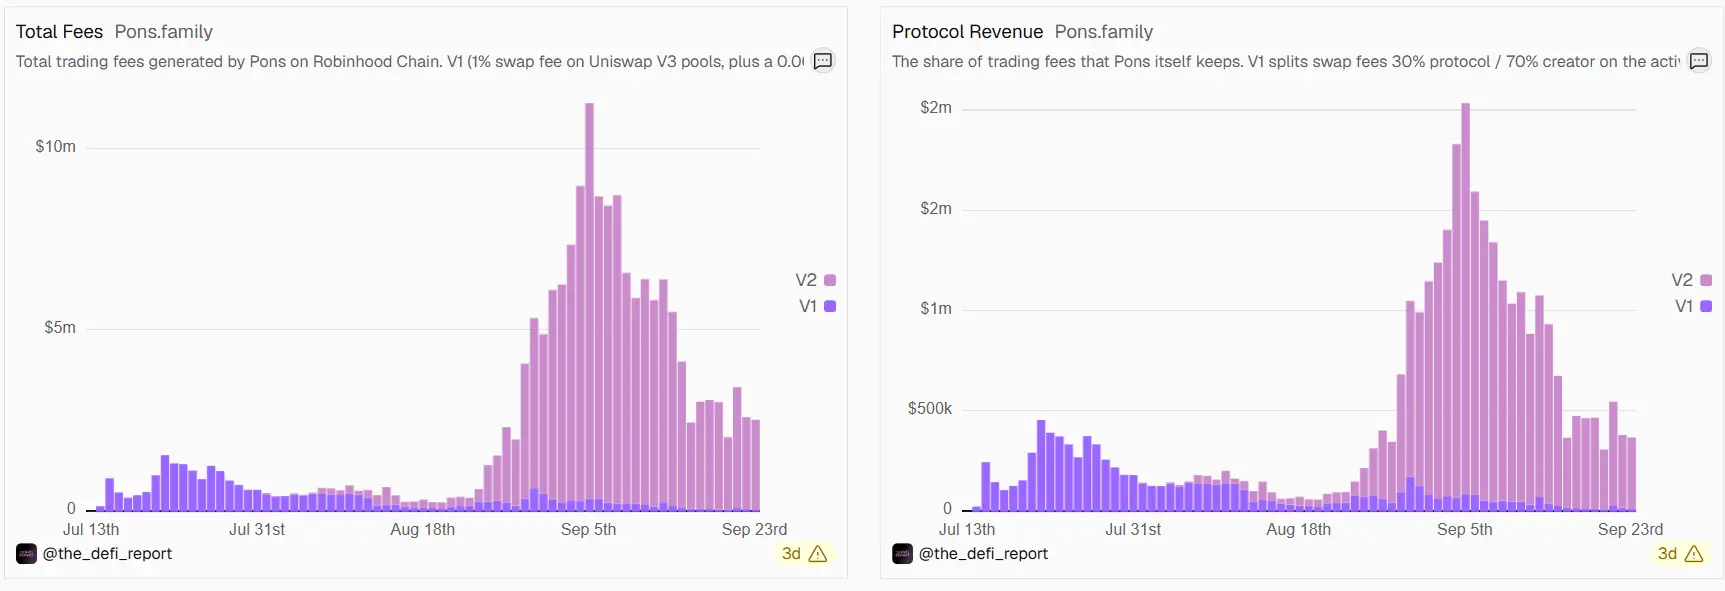
In the coming days, the Robinhood Chain may enter a testing period. On September 29, the gas subsidy provided by Robinhood Wallet for on-chain exchanges will expire. If user retention and trading volume can be maintained after the subsidy ends, then these data will truly be meaningful.
On September 30, Robinhood's annual conference HOOD Summit will launch new products aimed at active traders. As for Pons, the market is also waiting for the rollout of its next-generation version. The market expects that the new version will likely adjust the token issuance mechanism, fees, and graduation rules based on V2.
Overall, the original intention of the Robinhood Chain is to bring stocks onto the chain. The methods of continuous token issuance and concentrated control of opening positions are not uncommon across various chains; here, they have donned the guise of stocks and real estate. As more ordinary investors follow stock tokens to this chain, it may still face those old problems.
 Risk warning