Rethinking Neobank Emerging Bank
 Core Viewpoint

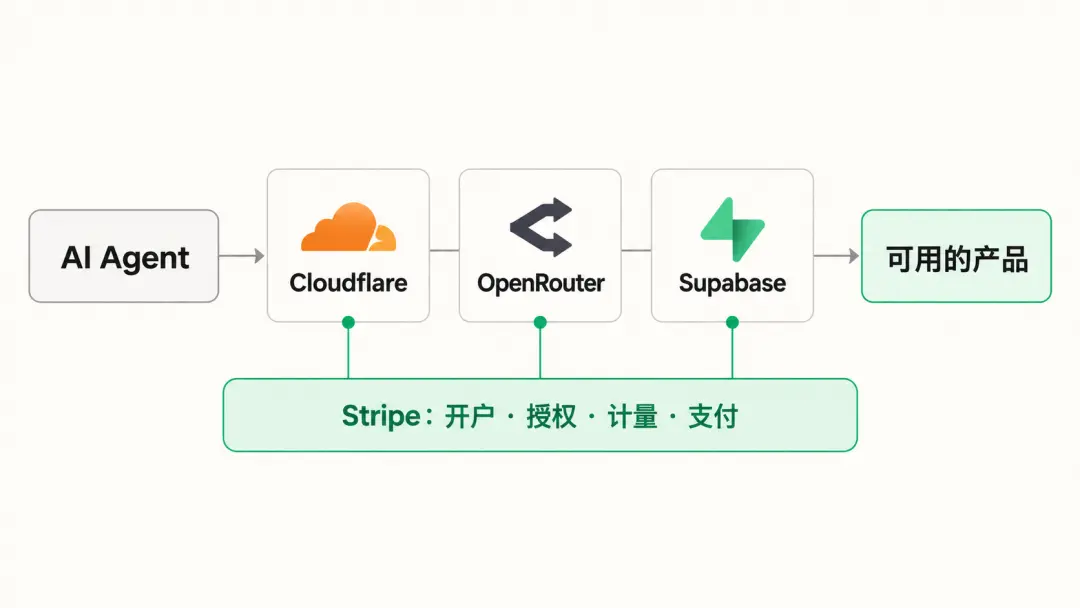
 Seven lines of code connect to payment, eight APIs break down the bank.
Author: Will Awang, Doke Fintech
On September 29, 2026, Stripe published a lengthy article outlining its stablecoin product stack, breaking down what a bank can do into eight product modules, from card issuance, payment collection, and fund management, all the way to issuing dollars themselves. A few days later, it appointed the founder of the crypto wallet company Privy to take over the entire crypto and stablecoin business.
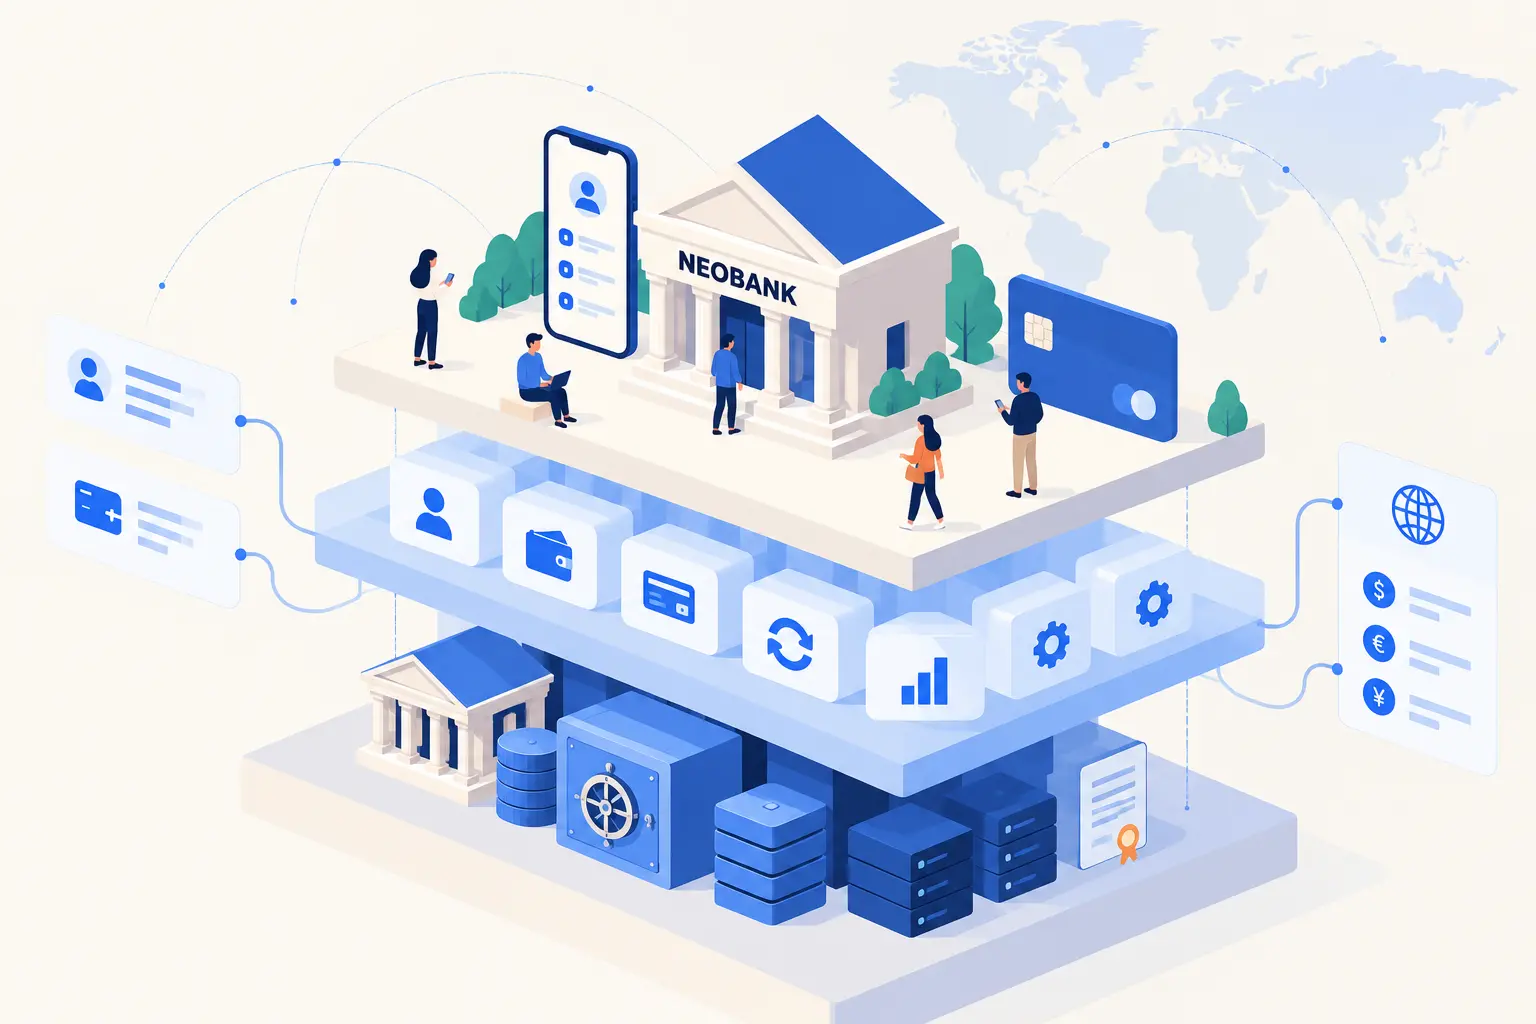
The neobanks we were previously familiar with split banking into front-end and back-end, doing the front-end themselves and outsourcing the back-end to partner banks; now, in the era of blockchain and AI, Stripe has further broken down the back-end into individual modules, allowing anyone to assemble a bank with the help of blockchain.
On September 25, the creator platform Whop launched a neobank template, claiming it could be set up in just 15 minutes; Nubank acted even earlier, entering the U.S. market on September 10 before its own license was approved, using the stablecoin from partner banks Lead Bank and Circle to get started. Previously, Nubank took thirteen years to obtain a banking license in Brazil after its establishment.
In the blockchain and AI era, anyone can assemble a bank. However, our observation is: no one is born a neobank; it is either built from the ground up (Nubank started with local credit), or from the top down (Crypto is born global and then penetrates regions).
The real question to consider is: where exactly has the threshold for neobanks been lowered? After breaking it down, how does each layer of the stack make money? At what stage should a company position itself on which layer? In the future, when agents begin to trade on behalf of others, will value capture fall into the hands of neobanks?
I. Banks Are Becoming Assembleable Businesses
There is a paradox in economics known as Jevons Paradox: the more efficient something becomes, the more it is used. Neobanks are following this path, from requiring customers to visit physical branches to open accounts, to only doing front-end operations while outsourcing deposits and clearing to partner banks through an app. Each time the cost of serving an individual decreases, another group of people who were previously outside the banking service range comes in.
Currently, the two most successful companies have each captured a unique customer segment:
Nubank entered the market in 2013 targeting individuals in Brazil without credit histories, initially offering no-fee credit cards, then gradually adding accounts and loans, only obtaining its banking license thirteen years later.
Revolut started in 2015 with cross-border currency exchange and prepaid cards, initially covering Europe with a Lithuanian license, taking eleven years to secure a full license in the UK. One entered through credit, the other through cross-border services, both following a path of starting light and then getting heavier, doing and supplementing as they go.
Neobanks built on blockchain and stablecoins are also referred to as crypto neobanks. The change brought by stablecoins is not in the path of renting first and supplementing later, but in the range that can be rented:
Expanding from a local bank to a complete set of global, programmable financial capabilities.
In April 2026, a16z crypto provided a classification of the stablecoin market: the previous wave of Banking as a Service involved fintech companies renting banking licenses and accessing core banking systems; this wave allows companies to build directly on blockchain infrastructure and self-custody wallets, combining accounts, payments, wealth management, currency exchange, and credit into complete products.
The changes occur in two areas:
The USDC that users place in stablecoin neobanks is a liability of Circle, not a deposit of the neobank; the heaviest burdens of deposit licenses and capital adequacy remain with the issuer.
Accounts are recorded on public chains, denominated in dollars, allowing for cross-border circulation and not being restricted by traditional bank operating hours, with only the fiat currency inflow and outflow requiring local partners.
The role of stablecoins and Stripe for neobanks is akin to that of AWS for internet companies: transforming infrastructure that previously had to be built in-house into on-demand services. When Stripe started, it allowed merchants to integrate payments with just seven lines of code; now it disassembles banks with eight APIs.
AI reduces another type of cost. Félix moved cross-border remittances into WhatsApp, eliminating the need for users to download an app; Nubank uses financial behavior data from approximately 135 million users to train models that predict defaults. Going a step further, software begins to initiate transactions on behalf of customers, creating a new authorization relationship.
According to Jevons' logic, the outcome is predictable: neobanks will proliferate, covering an increasingly broader population. However, as the number of potential customers increases, the challenge shifts from whether it can be done to where money can be made.
II. The Bottom Layer Relies on Qualifications, the Middle Layer on Accounts, and the Upper Layer on Customers
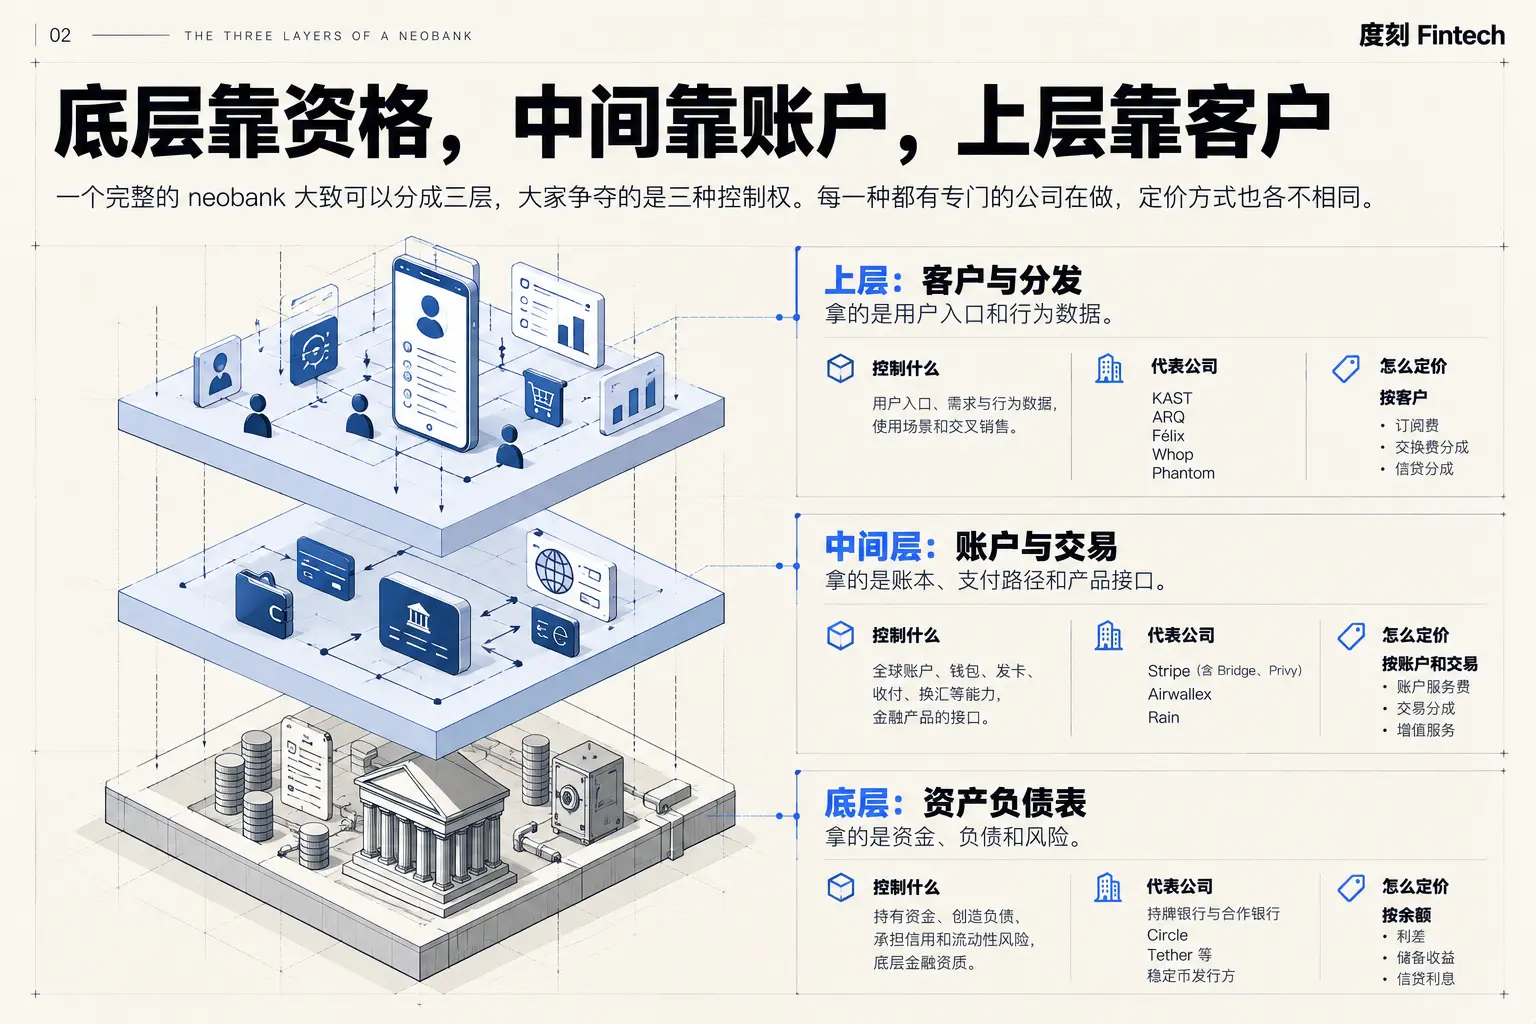
A complete neobank can be roughly divided into three layers, with competition over three types of control.
The bottom layer holds the balance sheet: who holds the funds, creates liabilities, and bears credit and liquidity risks. The middle layer controls accounts and transactions: who manages the ledgers, wallets, payment paths, and product interfaces. The upper layer controls customers and distribution: who holds user entry points, demand and behavior data, usage scenarios, and cross-selling opportunities.
Nubank and Revolut spent a decade consolidating these three types of control; now, there are specialized companies operating at each layer, with different pricing models. How much value a company can capture depends on how many types of control it holds and whether others can easily replace it.
Revolut's profit statement shows what it looks like when one company holds all three types of control. In 2025, it generated £4.5 billion in revenue and £1.7 billion in pre-tax profit; it can capture funds from balances, transactions, and cross-selling from the same customer. Many traditional banks derive over 70% of their income from interest, while Revolut earns three-quarters from fee-based income. Nubank is more focused on the bottom layer, with $16.3 billion in revenue and $2.9 billion in net profit in 2025, supported by a $41.9 billion deposit base backing a $19 billion credit portfolio.
Having all three layers allows Nubank and Revolut to capture more complete revenue from the same customer, reducing value leakage to partners. Profits, of course, also depend on customer scale, customer acquisition costs, bad debt control, and interest rate spreads in the market. However, once the three layers are divided among different companies, each layer takes a cut, with intermediaries profiting from the price differences.
Let’s compare the same revenues; in the case of stablecoin neobanks, they flow to different layers:
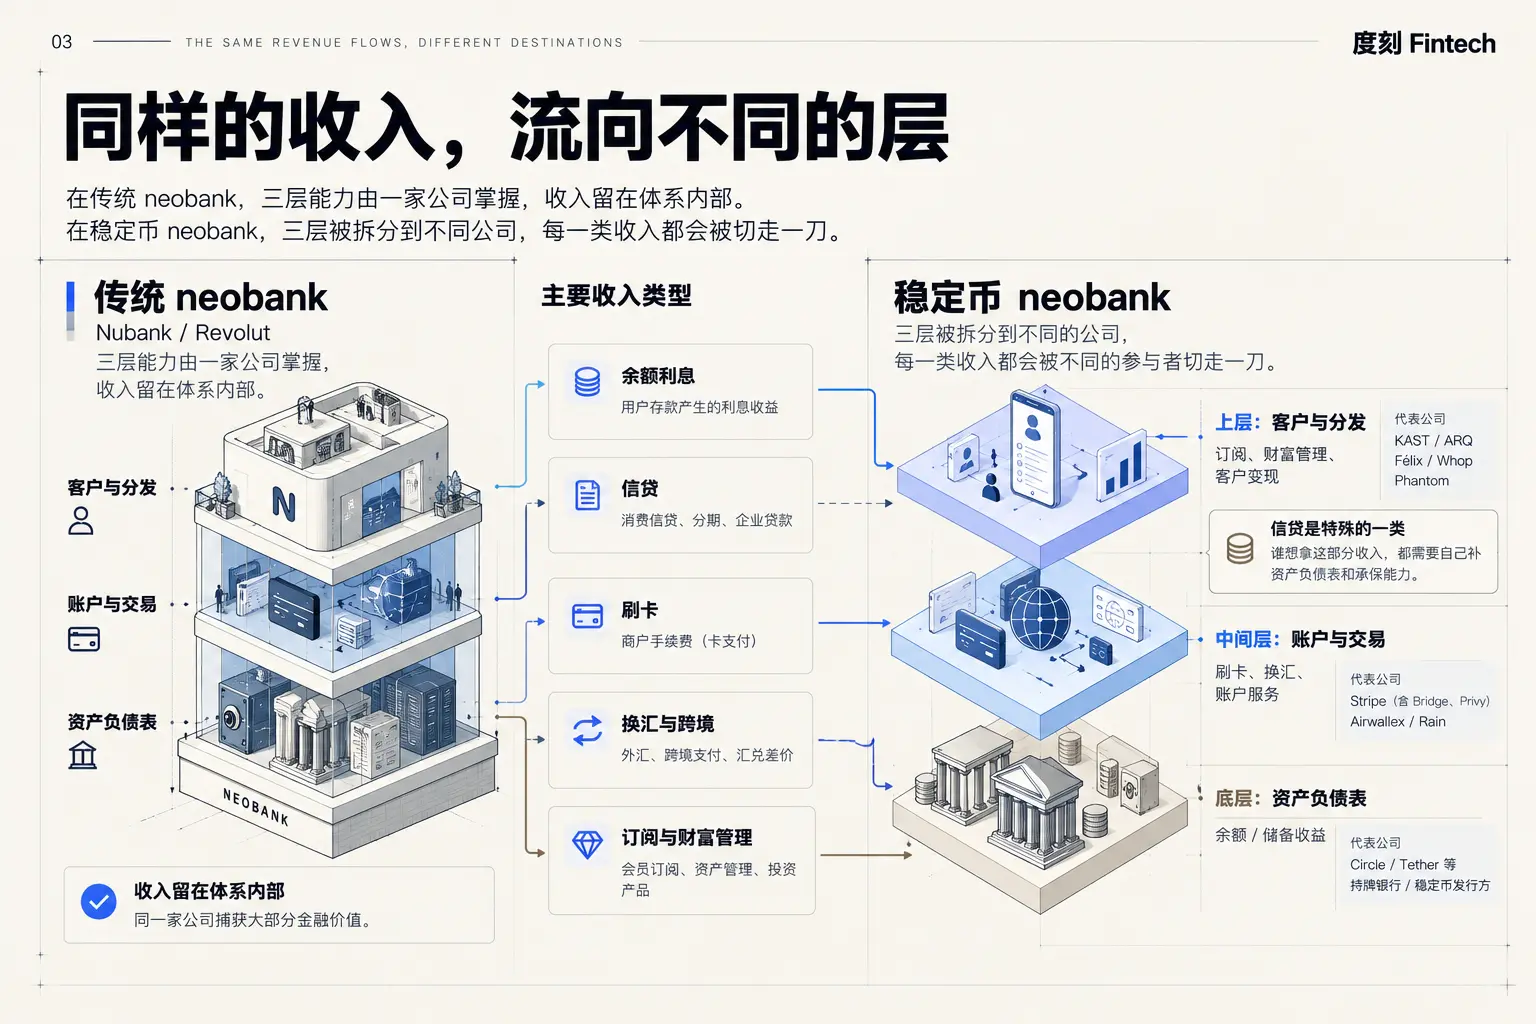
It is important to note: the threshold for assembling banking capabilities has significantly decreased, but the threshold for managing financial risks has not decreased alongside it. The burdens of funds, credit, compliance, and redemption have not disappeared; they have simply been transferred to issuers, partner banks, and various service providers.
Issuers must bear redemption and reserve management, the middle layer faces price competition after scaling, and the upper layer bears customer acquisition, customer service, and fraud losses, while credit must account for funding costs, bad debts, and capital occupation. Revenue attribution does not equal final profit; it is essential to consider who bears the costs and risks, as well as who ultimately has the final say.
2.1 Bottom Layer: Qualifications of Local Fiat Currency and Issuance of Stablecoins
The bottom layer controls where funds first land. It has two sides: one is fiat banks, and the other is stablecoin issuers.
On the fiat side are licensed banks that accept deposits, connect directly to local clearing, and are protected by deposit insurance; Lead Bank and Cross River, which stand behind many crypto neobanks, fall into this category, as do Nubank and Revolut's own banking licenses. Over the past decade, partner banks have been the biggest vulnerability for crypto companies, difficult to establish and easy to lose; now, a number of crypto-friendly banks are filling this gap.
On the stablecoin side are issuers like Circle and Tether, which accept dollars, issue stablecoin accounts instead of bank accounts, and build a dollar ecosystem on the blockchain, effectively serving as banks for on-chain dollars.
Both sides earn from the interest spread between deposits and loans or similar arrangements. The lowered threshold has not harmed this layer; Simon Taylor, head of market expansion at Tempo, wrote in the 2025 annual report "State of Fintech 2026":
In 2025, when stablecoins and agentic commerce were at their peak, banks were not disrupted; instead, they experienced a record year.
However, balances are not all the same; fiat deposits, customer funds held in custody, stablecoin reserves, and user assets in wallets have different legal attributes, and only a portion of these can be lent out.
But the two sides are converging. On the issuer side, Stripe's Bridge received conditional approval from the OCC for a national trust bank in February 2026, and once fully approved, it can custody digital assets, issue stablecoins, and manage reserves. Although trust licenses cannot accept custodial deposits, they allow issuers to step into the banking system. According to a16z, this licensing race is about which position one will occupy in the payment system in the future: if regulations allow licensed entities to connect directly to the Federal Reserve's clearing system, issuers that obtained licenses earlier will enter the core of the financial system.
Banks are also moving towards stablecoins. SoFi, holding a banking license, issued SoFiUSD in December 2025, claiming to be the first stablecoin issued on a public chain by a U.S. national bank.
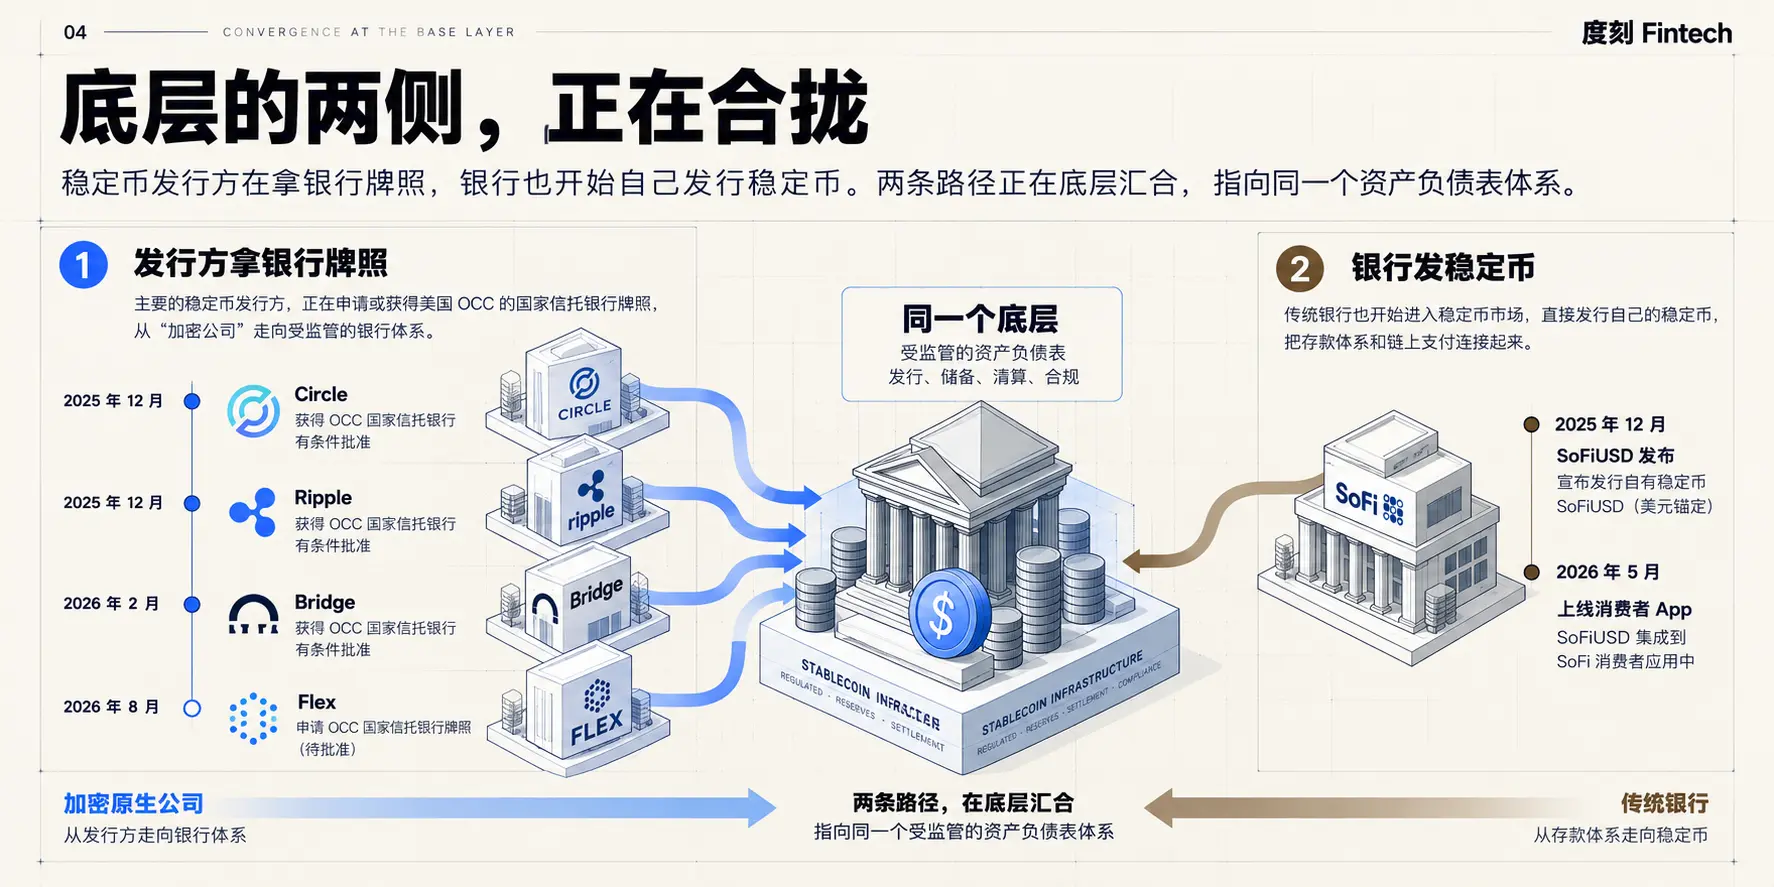
The boundary between the bottom and middle layers lies in whose balance sheet the money is recorded on: the bottom layer is the holder of the money, while the middle layer organizes these capabilities into accounts and sells them through APIs. What is difficult to replace at the bottom layer are licenses, clearing qualifications, and low-cost sources of liabilities.
2.2 Middle Layer: Global Accounts and the Money Deposited in Accounts
The middle layer competes for global accounts. An account that can store money, make payments, receive payments, and exchange currencies can also stack wealth management, consumption, and lending on top.
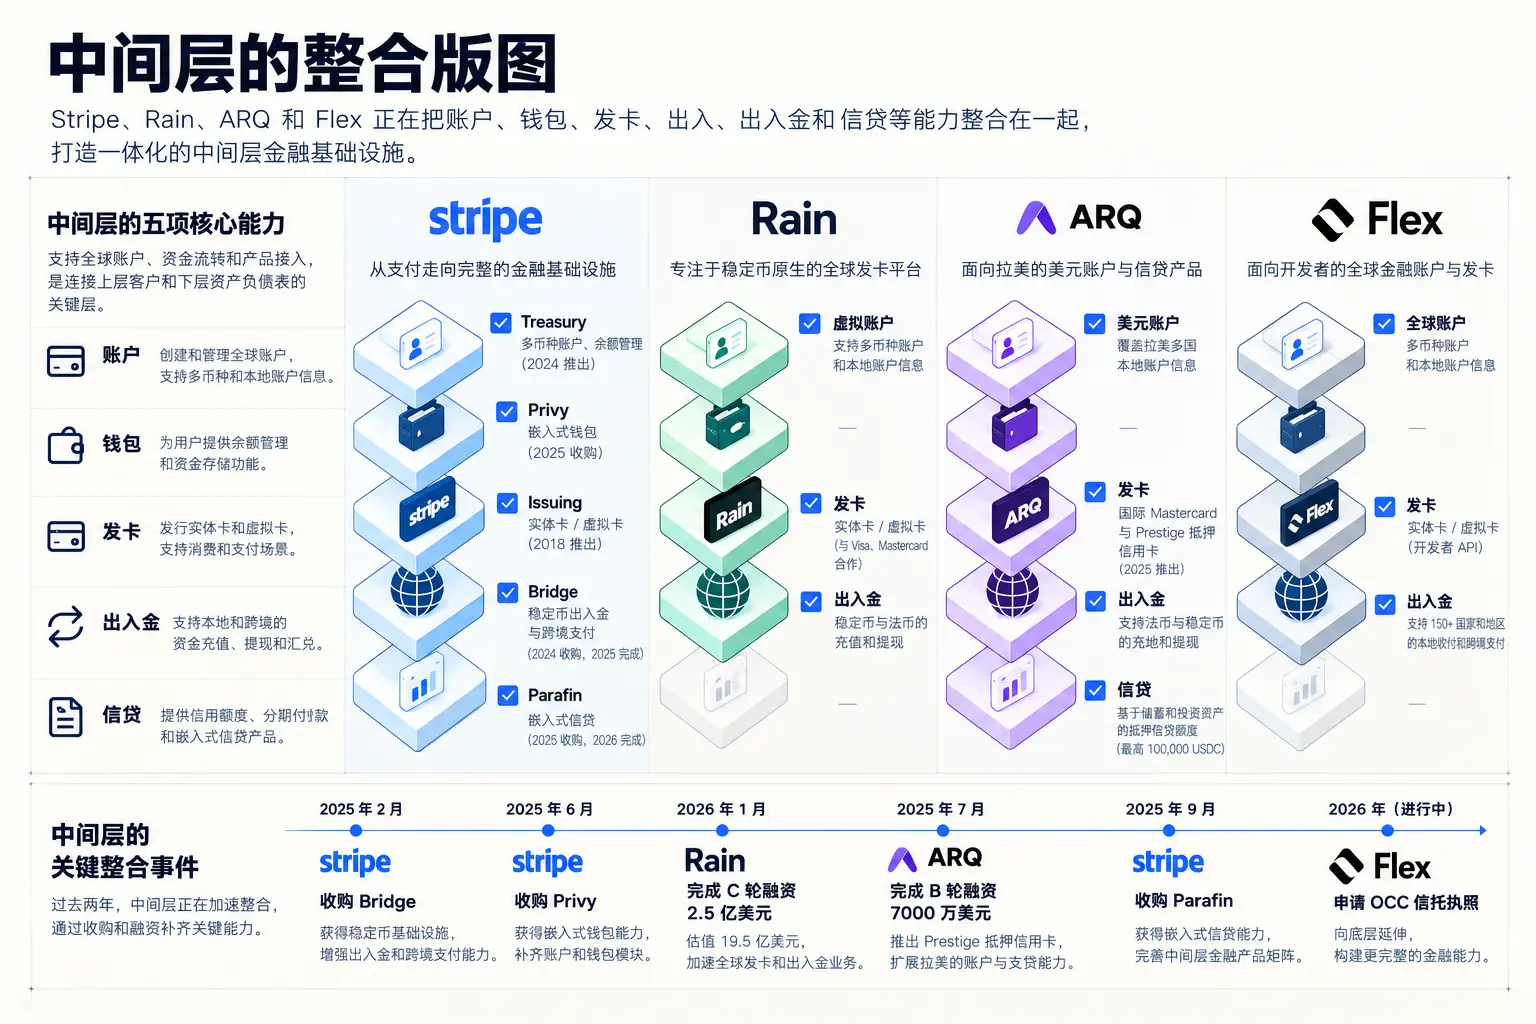
Stripe has already placed accounts at the strategic center. Henri Stern, the founder of Privy mentioned at the beginning, took over Stripe's crypto and stablecoin business on October 5, stating that wallets are the center of digital ownership, but they need to be integrated with orchestration, card issuance, and asset issuance to be powerful. Stripe now refers to Treasury as the account layer of global financial products, allowing businesses to hold fiat and stablecoins in one account and make payments to 160 countries using just an email address.
Once the account is in hand, the middle layer begins to compete on both ends. Upwards, it competes with the upper layer for cross-selling. On September 30, Stripe announced the acquisition of Parafin, which allows platforms like DoorDash and Gusto to lend to merchants in their backend, having lent over $3 billion. Ironically, Parafin's past selling point was not being tied to payment processors.
Downwards, it competes with the lower layer for balances. Rain started with issuing stablecoins, then added virtual accounts and deposits/withdrawals, and is attempting to connect directly with ACH and SEPA. It is pushing card-issuing banks, project managers, and processors into the same infrastructure to capture more interchange fees, currency exchange spreads, and reserve income.
The more platforms the middle layer connects to, and the more comprehensive the services linked to the account, the harder it is for customers to migrate. It wants to share in the upper layer's cross-selling while also capturing the lower layer's balance income.
2.3 Upper Layer: Financial Products or Embedding Finance in Products
The business of the upper layer is about who can acquire customers first. It has taken two paths: companies like KAST and ARQ treat finance as a product directly; platforms like Whop embed finance into their existing businesses. Simon Taylor's report mentions that Robinhood, Klarna, and Affirm are also using cards as growth drivers, with everyone wanting to become a neobank.
Among the former, the fastest runners are KAST, ARQ, and Félix. For example, Félix serves Latin American immigrants in the U.S., completing remittances via WhatsApp, with backend settlements using USDC; after obtaining credit limits, it has begun to extend into savings and consumer loans. KAST started with stablecoin accounts and cards, while ARQ began with dollar accounts in Latin America, both extending into credit and wealth management.
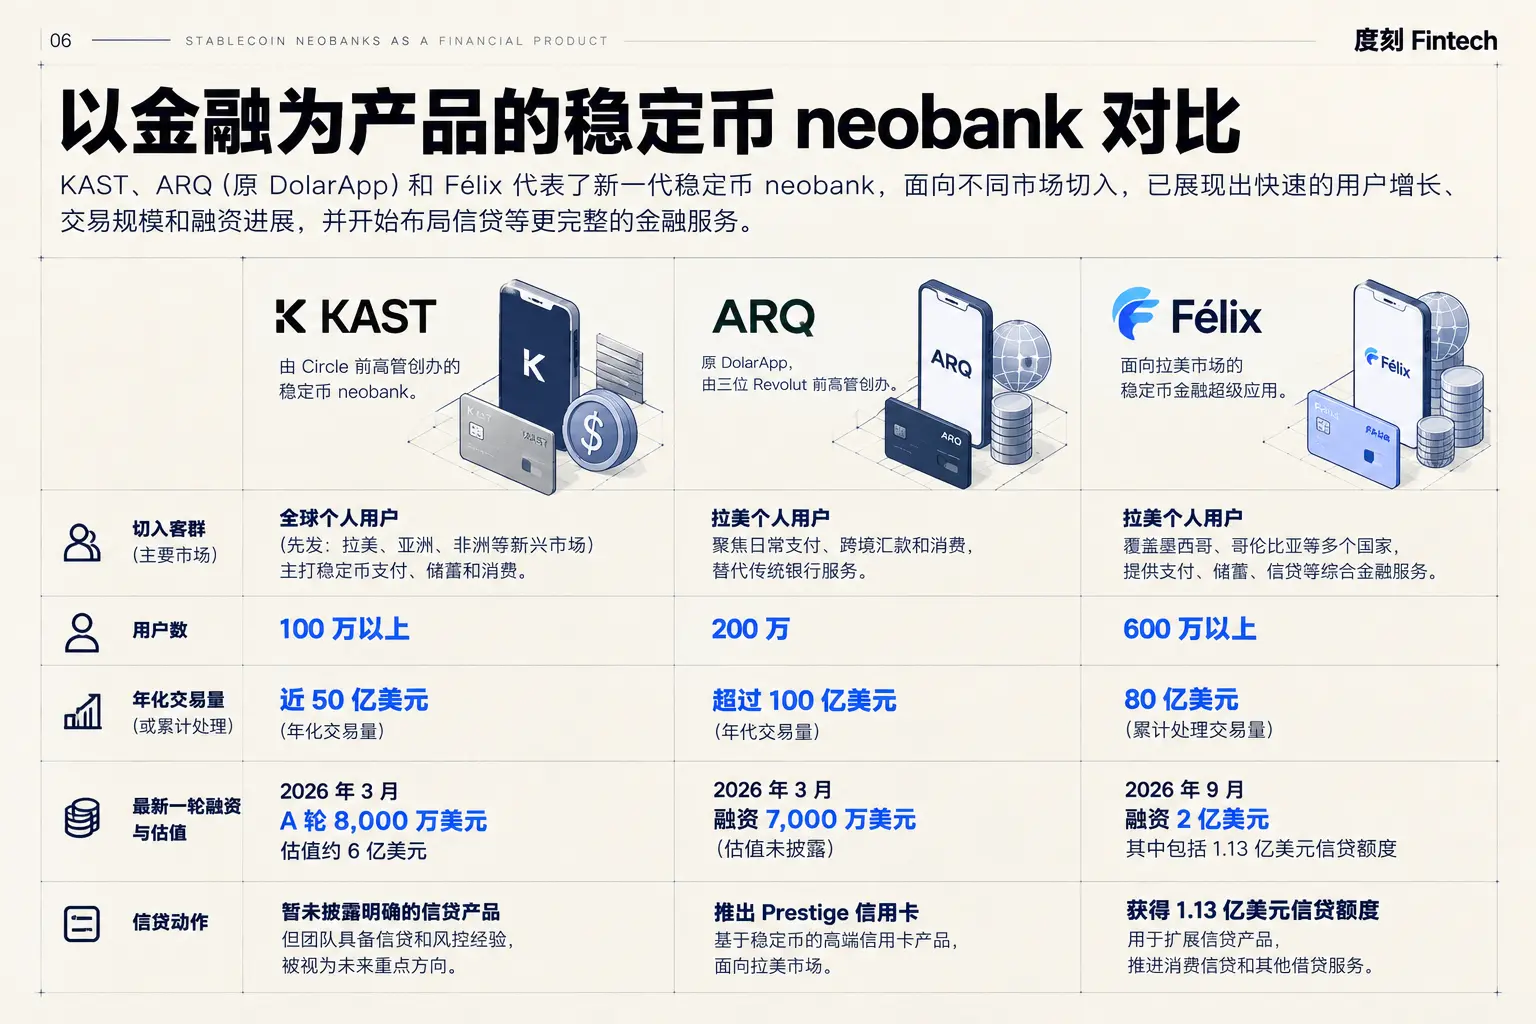
Dollar accounts are just the entry point; money needs to be earned after the account is opened. Once users have a stable dollar balance, credit, investment, wealth management, and insurance can all be connected.
The three companies are on the same path: acquiring customers through global accounts and monetizing through financial services, with local credit being the most valuable. The main components of global dollar accounts are already highly rentable, but local deposits/withdrawals, compliance, and clearing are not yet standardized; capital can also be rented in stages, with credit limits, securitization, and partner banks as methods; what cannot be rented is the local underwriting capacity validated through a complete credit cycle, as well as low-cost, sustainable customer relationships. Lending is not difficult; making a profit across cycles is what is challenging.
a16z's judgment points here: payments are the first act, and credit is likely the second act. Once the floating supply of stablecoins reaches trillions of dollars, this money will need a place to be used, and a new credit market will eventually emerge on-chain.
The latter type is represented by Whop. Originally a digital goods marketplace for creators, it settles about $3 billion for sellers each year. By turning the settlement endpoint into a platform account, the money stays on the platform, can be exchanged for stablecoins, invested, and then spent via card, allowing Whop to profit from the stay and flow of funds. Phantom, Remote, and Shopify are also embedding finance into their existing products; in Latin America and Southeast Asia, MercadoPago and Grab have already taken similar paths.
Although functional neobanks are fast, the costs are written into the terms. Lex Sokolin from Fintech Blueprint has dissected Whop's service terms: it is not a bank, and the compensation liability limit is either 12 months of fees or $100; the wallet comes from Privy, the card is issued by Third National and managed by Rain, and the balance is deposited in Aave for interest via Veda's treasury; fiat funds are held in a mixed custody account at partner banks, not covered by FDIC insurance, and are of the same structure that caused issues during the Synapse bankruptcy in 2024.
Lex Sokolin's conclusion is straightforward: the positioning is cool but could also be dangerous. Banking is ultimately a business of managing risk.
Regulators have also noticed this structure. A Federal Reserve study from April 2026 pointed out that when the operational chain of a stablecoin consists of multiple third parties, it may be difficult for the market to identify where the pressure comes from when problems arise, potentially amplifying panic during a crisis.
What is irreplaceable in the upper layer is customer trust, scenarios, data, and low-cost distribution.
Three, Which Layer You Are In Depends on the Stage
There is no unified answer for which layer a company should stand on.
At the start, rent as much as possible to prove that you can capture customers; once you scale up, bring back the most impactful segments on profit, data, and survival.
Startups rent the lower and middle layers, only operating in the upper layer, opening once they capture a customer group. Today's stablecoin neobanks are mostly here, just as neobanks started years ago. Chime still does not have its own banking license, keeping accounts at partner banks and primarily earning through interchange fees from card transactions. The profit margins are thin, but the startup speed is fast.
As for which layer to reclaim, it depends on where the company's advantages lie. How much profit the partners take is one calculation; whether the company can survive if the partner cuts off supply is another. For companies that profit from credit, the answer is usually the lower layer; for distribution platforms like Whop, a banking license may not be necessary; whether the middle layer should lend itself also needs to be calculated separately. Reclaiming key segments does not mean that being fully stacked is better; only when the benefits in profit, data, and stability exceed capital and regulatory costs is cross-layer worth it.
SoFi is the clearest example. In 2022, it acquired the small bank Golden Pacific, and after obtaining a national banking license, it began lending with its own deposits, increasing its deposit scale by more than thirty times. Nubank followed the same path by acquiring Banco Porto Real in 2026.
Reinforcing the lower layer has varying depths. Renting product capabilities, renting capital, and then owning stable, low-cost sources of liabilities are three different depths of integration. Félix has reached the second step, while SoFi and Nubank have reached the third step.
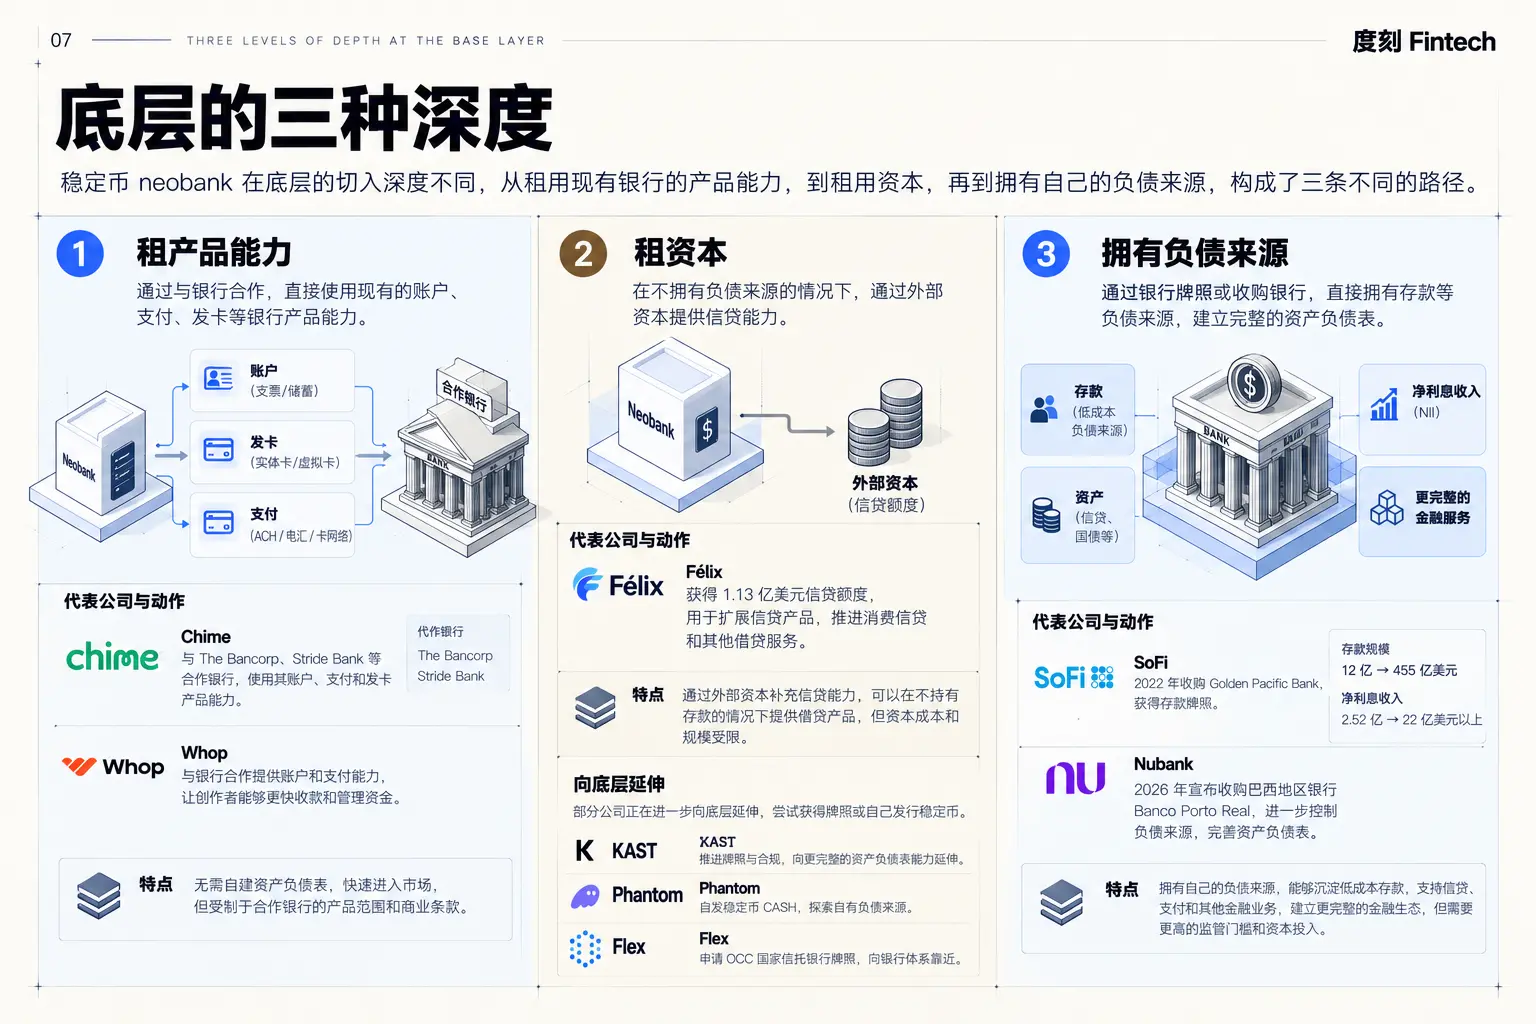
Nubank and Revolut have reached maturity, holding all three types of control in their core markets. However, upon entering new markets, they must choose again. Nubank's choices this year illustrate the issue: quickly opening in the U.S. by borrowing from Lead Bank and Circle; acquiring only the missing banking license in Brazil; and in the UK, abandoning negotiations to acquire Monzo for £8 billion to £10 billion in September, while Monzo is a fully stacked digital bank.
Nubank's most valuable asset is the customer base and underwriting capacity accumulated in Brazil, which may not be replicable in the UK. Entering a new market, even mature companies must recalculate: which capabilities to continue renting and which are worth buying.
There is also an unavoidable question: Nubank and Revolut can also add stablecoin accounts; Revolut launched the euro stablecoin EURR issued by Bridge in August 2026, and Nubank created Nu Global. Why would the new generation still have opportunities?
The answer lies in the customer base. The phenomenon we observe is that mature neobanks are moving upwards, increasing customer value, and extending into wealth management and high-end services; stablecoin neobanks are entering from the groups with the strongest cross-border dollar demand and the worst service from the old system, with ARQ serving dollar savings in Latin America, Félix serving immigrant remittances, and KAST targeting those lacking usable dollar accounts. The two sides will gradually converge, but new players start much cheaper, and the time licensed neobanks take to enter a new market may be the time they have already completed their startup phase.
The boundaries are not static. Stripe is extending downwards with trust licenses, Bridge, and Parafin while leveraging over 300 million Link users to reach customers upwards.
Four, In the Agent Era, What Are We Competing For?
As the threshold lowers further, initiators of transactions are no longer just people. As personal AI begins to shop, book services, and pay per use on behalf of people, the financial system must accommodate a new agency relationship: accounts still belong to individuals or businesses, and agents initiate transactions within the scope of authorization, but they are not new legal entities.
This agency relationship spans three types of control. User intentions arise from AI products, are translated into permissions and transaction instructions at intermediaries like Stripe and Link, and are ultimately decided by banks or issuers whether to accept and settle. When problems arise, responsibility still returns to law and contracts. Authorization is likely to become a new control point contested between the middle and upper layers: AI companies want to hold user intentions and long-term authorizations, while Stripe, Link, and Catena want to turn authorizations into verifiable, executable, and accountable financial credentials.
Simon Taylor from Tempo says every AI company will become a payment company. This statement may be somewhat exaggerated, but the direction is correct: as long as AI begins to act on behalf of users, it cannot avoid payments; whether to do it personally is another matter. Meta Muse uses Stripe Link and one-time virtual cards to check out for users, then connects with Shop Pay and PayPal; Stripe and Tempo have launched machine payment protocols that allow agents to pay directly for data, computing power, and software tools. AI companies grasp user intentions, while payment capabilities are mostly still rented from the middle layer; what Stripe needs to do is provide agents with a secure way to access user funds and payment credentials.
The focus of competition lies in whether AI companies only grasp user intentions or further control identity, payment credentials, and account relationships.
Another path is for licensed institutions to directly undertake identity, authorization, and settlement in agent transactions. Catena Labs aims to establish a financial identity binding each agent to the underlying individual or business, allowing them to set spending limits, payees, and balance limits before handing execution over to the agent. On September 18, 2026, the OCC granted Catena Trust Bank preliminary conditional approval. What it aims to build is a financial agency system that encompasses subject identity, authorization scope, strategic limitations, transaction execution, and accountability records. Whoever controls identity, permissions, and transaction credentials may become a new value node in the agent era.
The banking industry is also calculating this equation; Oliver Wyman believes that by 2030, agents will become the dominant customer acquisition channel.
When agents begin to spend money on behalf of individuals, who holds the funds, payment credentials, and authorization rules? Is it the AI companies, Stripe's Link, or financial institutions like Catena?
This competition is about who can safely transform human authorization into transactions that machines can execute and hold accountable afterward. Simply providing an agent with a wallet does not count as a win.
5. What Can Be Rented and What Cannot Be Rented
What blockchain and AI have lowered is the cost of assembling financial capabilities and serving customers, but they have not simultaneously lowered the threshold for managing financial risks. As a result, value has fallen into three types of control: balance sheets, accounts and transactions, customers and distribution.
At the beginning, rent what can be rented; after scaling up, reclaim the parts that determine profits, data, and life and death. When entering a new market, a new selection must be made. The agent has turned authorization into a new point of contention: whoever holds the user's intent, payment credentials, and account relationships may become the new entry point between people and the financial system.
Reconsidering neobanks, in the end, this term may even become obsolete. Ten years ago, it referred to a type of company: banks without physical branches, relying solely on apps. Today, creator platforms, social companies, payment companies, and even AIs that spend money for people are all doing what neobanks do. When every product with users can sprout a bank, neobanks are no longer an industry but a capability.
Everyone is a neobank, but ultimately, neobanks may disappear within products.
 Risk warning