IOSG: Papertrade's daily revenue is second only to Tether, a casino that refunds 90% of the rake to the losers
 Core Viewpoint

 Papertrade's daily income is second only to Tether, with a synthetic perpetual protocol that refunds 90% of the fees to losers, achieving a transaction volume of $13.6 trillion in just nine days, while traders suffered a net loss of $63.2 million, and the price of the PAPER token doubled.
Author | Mario Chow @IOSG
Data as of October 19, 2026, UTC 10:00, 212 hours after opening.
Summary
Papertrade is a synthetic perpetual contract on HyperEVM, launched on October 10, only trading BTC and ETH, with a maximum leverage of 1000 times. The team consists of Jez (Colin Hong, former risk partner at Standard Crypto) and anonymous developer Blurr. There is no funding, no pre-mining, and the team has not retained any shares. The only way to obtain the token PAPER is to lose money on the platform.
The headline trading volume is currently $13.61 billion, all inflated by the maximum 1000 times leverage; at the same time, the entire Hyperliquid 24-hour perpetual trading volume is $5.2 billion. The real money is much smaller: about 23,000 addresses deposited $335 million, with losses closing at $249 million, resulting in a net loss of $63.2 million for traders.
The core of this article lies here. Of the net loss of $63.2 million for traders, $54.1 million (86%) is distributed to PAPER stakers. There is also $4.7 million in the LP, and developers receive about $4.5 million (7%). The ones receiving dividends are the ones losing money: the top 1000 wallets hold 88% of PAPER, bearing 81% of the total losses and taking 91% of the dividends. In simple terms, this is a casino that returns the rake to the gamblers.
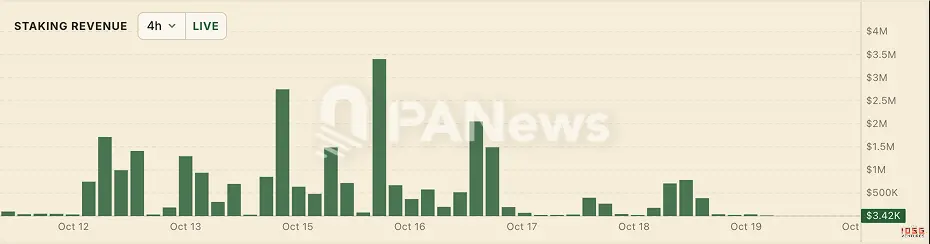
Staking income comes in waves, following the mining rewards. In the first ten hours, stakers received $24 million, and from the 12th to the 16th, the second wave generated another $24.9 million, dropping to $800,000 on the 17th. Additionally, PAPER has a price now. Paragon launched HIP-3 perpetual para:PAPER on Hyperliquid on October 18, opening at $0.012, spiking to $0.035 within two hours, and then hovering around $0.024. Based on 8.69 billion tokens, the market cap is $211 million, about twice the cost of mining one PAPER. PAPER itself still cannot be transferred.
Key Findings
A cashback cycle. 86% of the net losses are given to stakers, who are the wallets losing money: the top 1000 wallets hold 88% of PAPER, bear 81% of the losses, and take 91% of the dividends.
Income comes in waves following the trading volume. $24 million in the first ten hours, $24.9 million from the 12th to the 16th, dropping to $800,000 on the 17th when the mining rate fell to about 12 tokens per dollar, and $2.1 million after the perpetual launch on the 18th.
PAPER has a price now, but it is thin. para:PAPER is quoted at $0.024, about twice the cost of mining; this is a pre-market perpetual with a leverage of 3 times, with a position of about $5 million, and the underlying is still a token that no one can settle.
Solvency has been maintained. There has never been a queue of winners; now BTC and ETH need to rise 3.7% together to empty the pool, while on the first day it only required 0.7%.
How to Play
Where the Price Comes From
Open and close positions read the price once: the contract uses HyperCore to pre-compile and takes the mid-price of the bid and ask on Hyperliquid. The orders themselves do not execute on Hyperliquid. There is no order book, and individual positions are capped at $10 million, with no slippage regardless of the size of the position, and no funding rate. You are betting against a pool.
The Pool is a Water Tank
This pool (LP) is the only counterparty, and there is no one backing it. It starts from 0, outsiders cannot deposit, and you can think of it as a water tank with an overflow:
Losers pour in. Losses from closing positions or liquidations, 98% of the losses go into the pool.
Winners take from inside. Profits from closing positions are paid regardless of how much is left in the pool, first deducting the discounts mentioned later. If the pool runs dry, unpaid profits (margins remain unaffected) go into a first-come-first-served queue, waiting for future losers to fill. There are no other guarantees.
The overflow goes to stakers. Any amount over $5 million in the pool is pushed to PAPER stakers. The team announced on October 17 to raise this line to $10 million, but as of October 19, it remains $5 million on-chain, and we found no explanation for the delay.
Each closing position, regardless of profit or loss, incurs a 2% fee, with stakers and developers each receiving 1%. When losing, it is deducted from the loss, so 98% goes into the pool; when winning, it is deducted from the profit. Some are exempt from fees during the queue.
These are the rules. The money in the pool is not promised to anyone; how much ends up in the hands of winners and how much goes to stakers depends entirely on how the trades go.
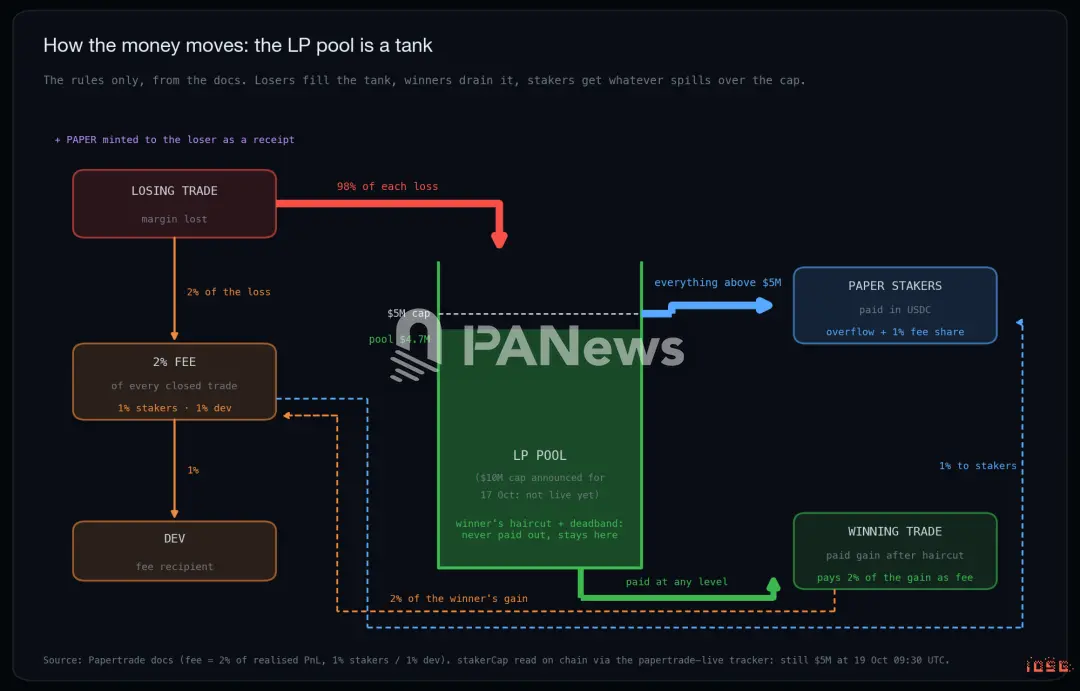
▲ How funds flow: The LP pool is a water tank
The most important point is this: this casino does not guarantee that winners will get their money. In ordinary exchanges, there is always a capital provider to pay the winners, such as market makers, insurance funds, or the house's own balance sheet. Papertrade has none of these. The pool only contains the money left by losers, and the cap is intentionally set; any excess portion once allocated to stakers cannot be retrieved. The portion exceeding the pool for winners is equivalent to asking "those who haven't lost money yet" for payment, and there is nothing in the contract that can force these people to enter the market.
Strictly speaking, this is not a Ponzi scheme; no one has promised returns, and the house edge is real. But from the perspective of the queued winners, it is no different from a Ponzi scheme: new money must continually come in for them to receive their payouts.
The real risk lies with the long-tail winners. A single position cannot breach the pool: with a position cap of $10 million nominal amount, even if a 1000 times long position is extraordinarily lucky, it would need to rise about 57% to owe $5 million. The problem is that there are no rules limiting a wallet from opening dozens of positions. 0x2025 has had about 30 ETH short positions, each worth $9.9 million, totaling $297 million; under this scale, if the market moves against them by 2%, the owed amount would exceed all the money in the pool. On the first night, 0x2025 was pushing the mid-price on Hyperliquid, and in 35 minutes, winners withdrew $2.4 million from the pool; at UTC 21:45, there was still $4.91 million, but by 22:20, only $2.48 million remained. This situation has not occurred again since.
How PAPER is Issued
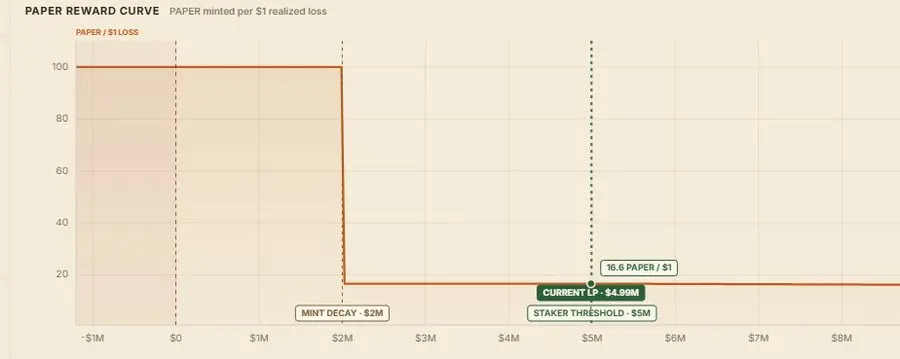
When the LP is below $2 million, losing $1 mines 100 PAPER. Above $2 million, the mining rate is 100 × (120M / (120M + H))², where H is a high water level that only rises, essentially the cumulative inflow of LP above $2 million. Currently, H is $243 million, and losing $1 can only mine 10.9 tokens, down from 100 tokens at launch.
The total supply will eventually approach about 12.7 billion: 12 billion on the curve (100 × $120 million), plus 660 million mined in the first hour when the pool was still below $2 million at the rate of 100 tokens. So far, 8.69 billion tokens have been issued, accounting for 69% of the cap.
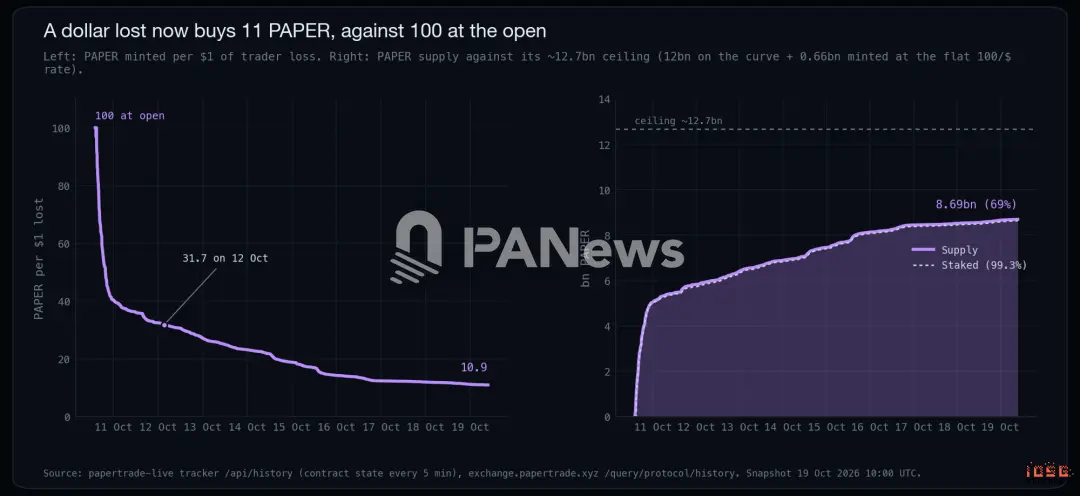
▲ PAPER mining rate and supply
Staking
Staking does not produce new coins. The threshold is 100 PAPER, with no lock-up, allowing deposits and withdrawals at any time. PAPER still cannot be transferred, with 99.3% currently staked. Dividends are distributed in USDC, allocated proportionally based on the amount staked, with no acceleration or tiers.
As for when stakers can actually receive money, the document outlines three rules:
Winners in the queue always take priority. When the pool cannot pay a certain winner, the shortfall goes into a first-come-first-served queue, and the pool's available cash for others becomes 0, halting fee distributions on both sides. New losses are recorded in a separate bucket specifically for repaying the queue. Until the queue is cleared, stakers will not receive a penny. This has not occurred yet.
Overflows are swept away in batches, not in real-time. The keeper calls pushStakerFees(), transferring amounts over $5 million into the staking contract. The swept money leaves the pool, and any future winners cannot retrieve it.
Between two sweeps, whoever arrives first gets it. The money from the winning closing transaction is credited immediately, while overflows must wait for the next sweep to be processed.
Where the Rake is Hidden
In addition to the 2% fee, the platform does not charge based on nominal amounts. The rake is hidden in the liquidation rules and on the profit side:
The liquidation line is set 5 basis points in advance. With 1000 times leverage, the margin can withstand a 0.1% fluctuation, but it will be forcibly liquidated at around 0.052%, with the entire margin collected.
Profits first encounter a 0.2 basis point dead zone, followed by an "asymmetric impact" discount, which becomes harsher the smaller the market movement. According to the upper limit parameters, BTC winners can take at most 90% of the original profit; with a 1% market movement, they receive about 88%, and with a 0.1% movement, they only get about 74%.
The remaining profits incur a further 2% fee.
The deducted money is not given to anyone; it stays in the pool and overflows to stakers once the pool is full. Let's do the math: $100, BTC, 1000 times. A reverse movement of 5.2 basis points results in $100 disappearing. A forward movement of 5 basis points, at fair value, should earn $50, but the actual amount received is $30.4. Since launch, no parameter adjustments have been announced.
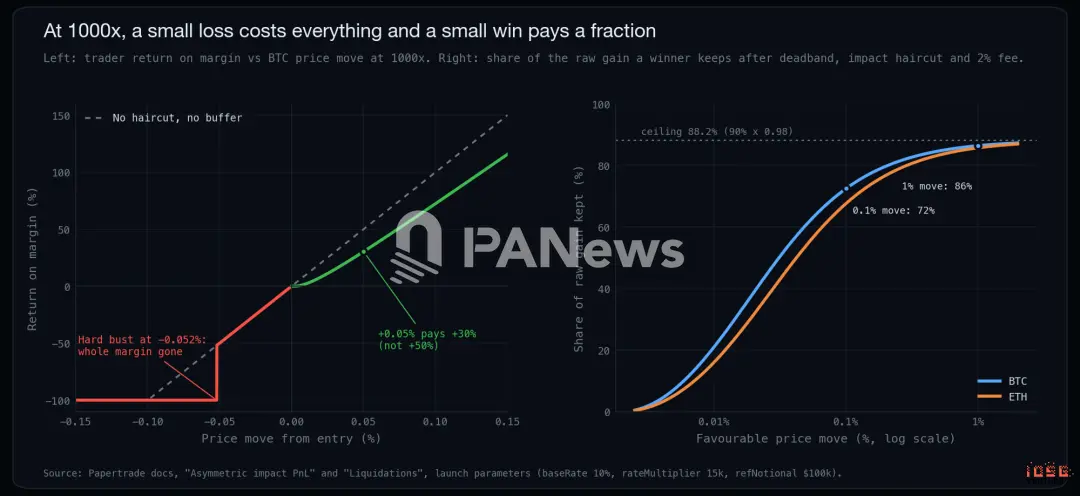
▲ Profit and loss under 1000 times leverage and profit retention ratio
Who Can Move the Switch
Opening positions, closing positions, and staking all go through Papertrade's relayer; withdrawals do not require this, and users can directly withdraw their money at any time. A 2/3 multi-signature can pause opening positions, delist markets, change position limits, minimum margin, and minimum order sizes, and can also adjust impact curves and fee parameters. Contract upgrades have a 7-day time lock. The relayer's sorting is "adaptive," prioritizing large orders.
Account Numbers
Unless otherwise noted, data is taken from October 19, UTC 10:00, which is 212 hours after opening.
How much real money is in the $13.61 billion trading volume
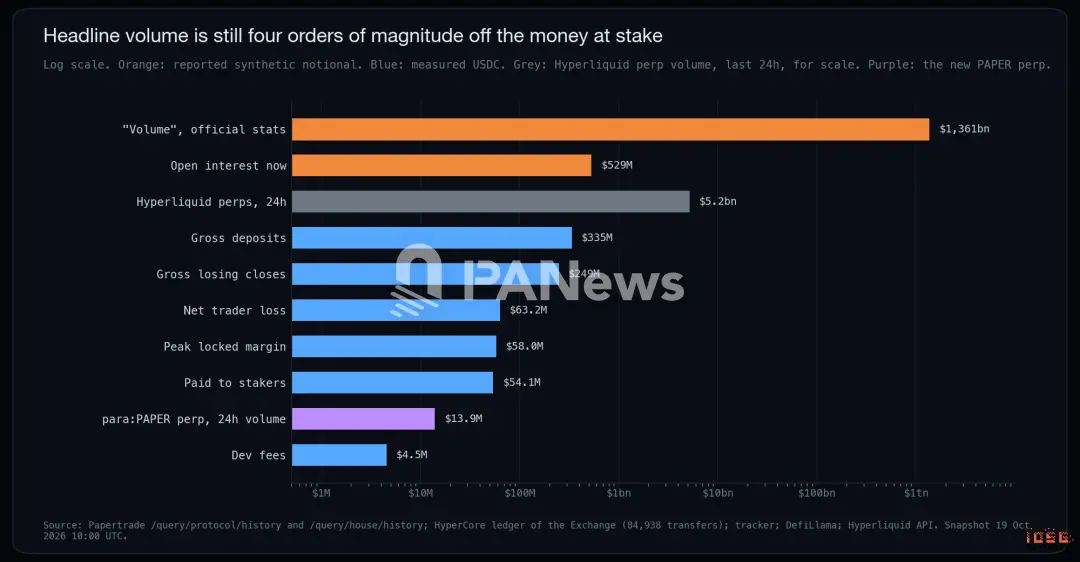
▲ Headline trading volume vs actual USDC
Peeling layer by layer:
$13.61 billion, trading volume on the platform. It seems that both opening and closing positions were counted once.
$529 million in positions, corresponding to $10.7 million in margin, averaging about 50 times. The average on the first day was about 160 times.
$335 million, the actual money that came in, from about 23,000 addresses; $271 million was withdrawn. The highest locked margin was $58 million, which appeared on the first day.
$249 million, losses from closing positions, the actual money that changed hands.
$63.2 million, net loss for traders, which is also the only portion that can be distributed to stakers.
The net loss accounts for about 0.46 basis points of the trading volume on the platform. The team earned about $4.5 million in fees.
Where Did the $249 Million Loss Go
The cumulative losses from positions contributed about $249 million to the pool. This is the gross amount, including all losses from closing positions, including the leg that lost in the wash trading; PAPER was extracted based on this figure. There are four destinations:
$185 million (75%) was paid to profitable positions, most of which were the other leg of the same batch of wash trades.
$54.1 million (22%) was distributed to stakers.
$4.7 million is still in the pool, just shy of the limit.
About $4.5 million (2%) belongs to the developers.
After deducting the portion for winners, traders had a net loss of $63.2 million, of which 86% went to stakers.
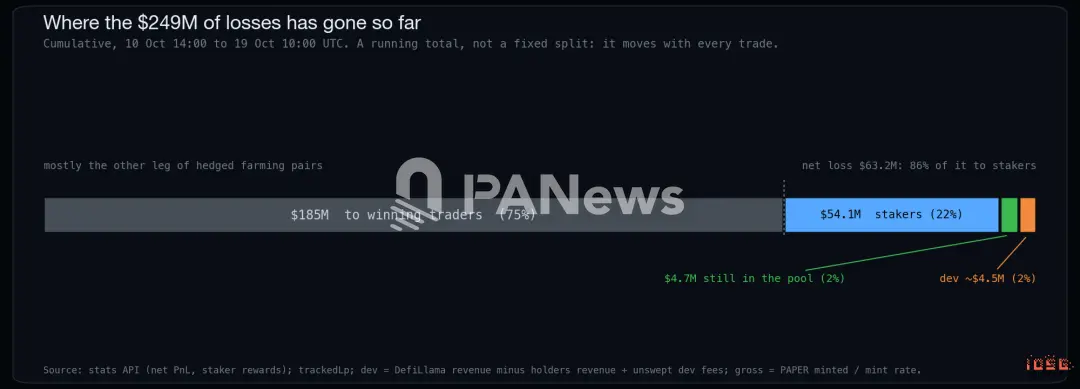
▲ Where the $249 Million Loss Went
Who Holds PAPER
16,198 wallets hold PAPER, of which 13,291 meet the staking threshold of 1,000 coins. The holdings are very concentrated, and the holders are the customers: the top 10 wallets hold 15%, the top 100 hold 52%, and the top 1,000 hold 88%. Similarly, these 1,000 wallets bear 81% of the losses from all losing wallets and took 91% of the dividends.
On average, each holder lost $0.0073 per PAPER, and after deducting dividends, only $0.0016. Based on a perpetual price of $0.0243, 97% of the supply is profitable after deducting dividends. Overall, traders lost $63.2 million, recovered $54.1 million in cash, and the PAPER they hold is valued at $211 million based on perpetual value. This valuation only turns into cash when someone buys, and currently, no one can buy PAPER itself.
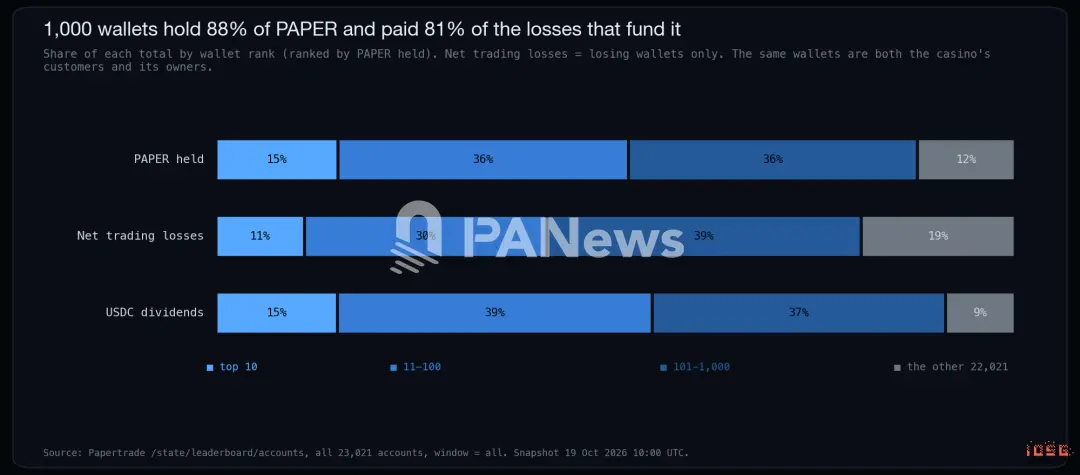
▲ Who Holds PAPER
The Treasury and LP Are Not the Same Thing
The money in the treasury does not belong to the market makers. It is the total USDC held by the Exchange contract, totaling $63.1 million: traders have an available balance of about $47.6 million, locked margin of $10.7 million, LP $4.7 million, and there is still $100,000 in developer fees that hasn't been taken. Only the LP belongs to the market makers, accounting for about 7% of the treasury. The treasury dropped from $138 million to around $60 million in the first two days, then remained between $58 million and $69 million. Since October 12, the LP has been between $4.3 million and $5.2 million, with daily deposits and withdrawals roughly offsetting each other, each direction between $5 million and $26 million.
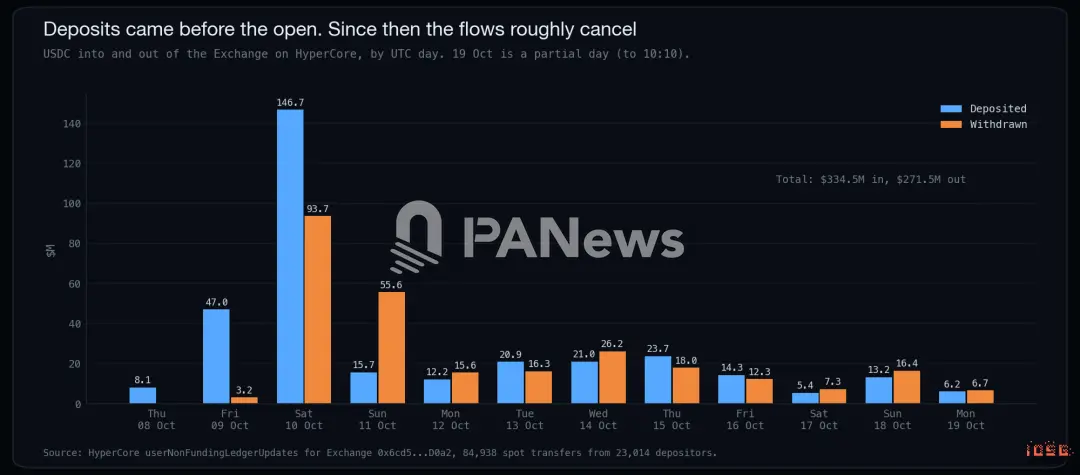
▲ Daily USDC Deposits and Withdrawals
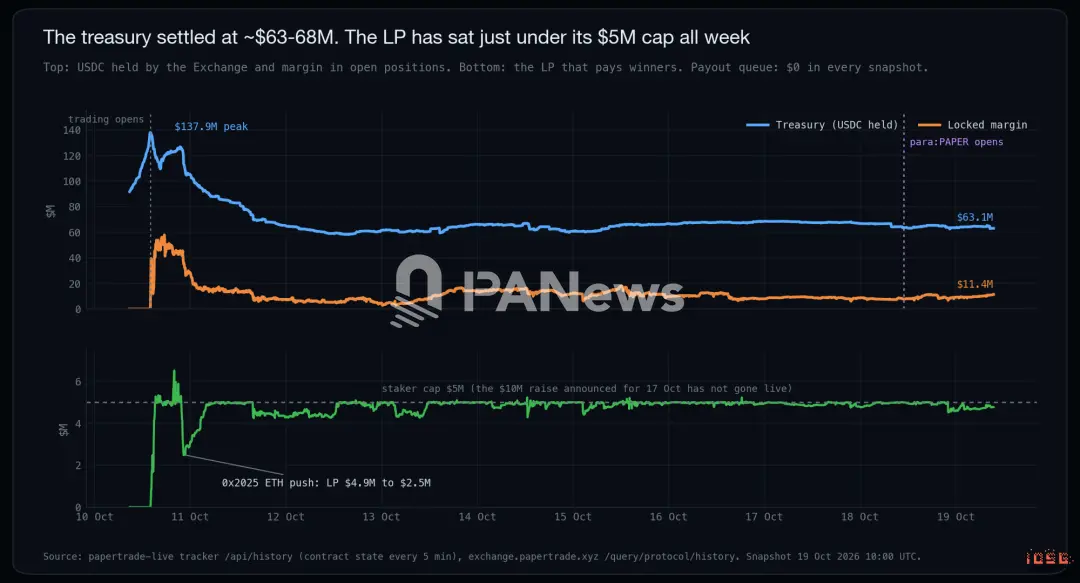
▲ Treasury, Locked Margin, and LP
Daily Losses
On the first day: losses from closing positions were $75 million, net loss was $28.4 million. On the 11th and 12th: daily gross losses were about $20 million, net losses about $4 million. Then came the second wave: gross losses rose to $27 million on the 14th, $41 million on the 15th, with daily net losses from the 13th to the 16th ranging from $4.5 million to $7.4 million. On the 17th, there was a cliff-like drop, with gross losses of $6 million and net losses of $700,000. On the 18th, gross losses returned to $11.9 million, net losses of $2.2 million, most occurring after the perpetual opening.
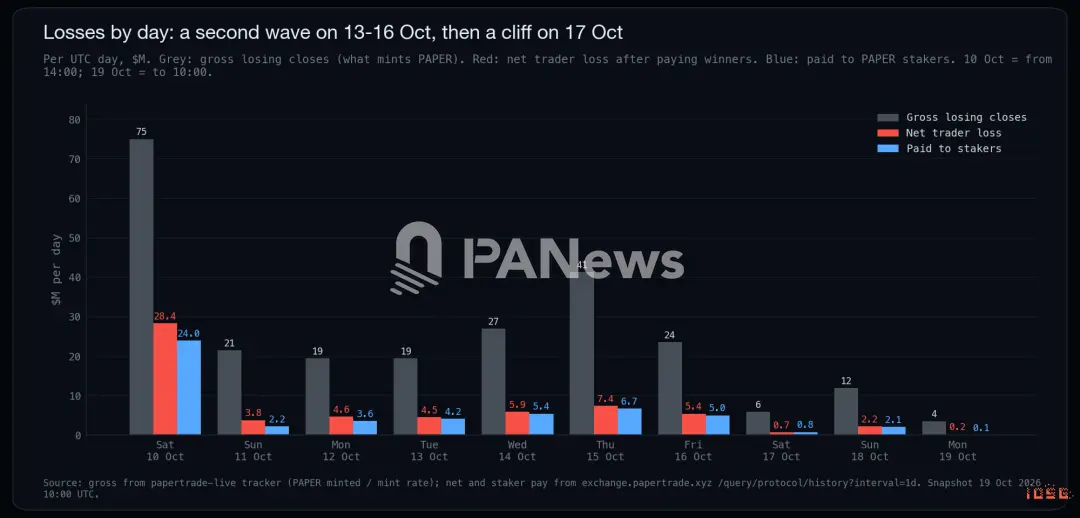
▲ Gross vs Net Trader Losses by Hour
The Stakers' Accounts
How to Distribute the Overflow
About 70 minutes after opening, the pool first hit the $5 million limit. After the overflow at 15:45 on October 11, the pool stayed below the limit for most of the day, and on the 12th it surged past the limit again, then net losses kept it there until the 16th. Stakers received $3.6 million on the 12th, $4.2 million on the 13th, $5.4 million on the 14th, $6.7 million on the 15th, and $5 million on the 16th. After that, on the 17th it was $800,000, on the 18th $2.1 million, and in the first ten hours of the 19th, $70,000.
The limit is an unresolved issue. The team announced on October 17 that it would double to $10 million. The tracker reads the stakerCap from the contract every five minutes, and each time it reads $5 million, including at 09:30 on the 19th. If it really goes up, the pool would need to incur about $5.3 million in net losses before it overflows again; at the rate from the 17th to the 19th, it would take four to five days without an overflow.
Yield, now there is a price for comparison
Currently, directly losing money to mine 1,000 PAPER costs $91, while at the opening it was $10. For those involved in wash trading, a set of positions lost about 13.7% of the accounting loss, with a cost of about $12.5. The perpetual pricing for 1,000 PAPER is $24.3.
The annualized dividend for the last 24 hours is $0.086 per coin: based on perpetual pricing, that’s 352%, and based on the direct loss cost, it’s 94%. For the last 7 days (including the tail end of the second wave), the annualized amount is $0.197 per coin, which equates to 812%. This means that the perpetual price is equivalent to about 100 days of dividends from the last day or 45 days from last week's dividends. This gap reflects the market's judgment on the speed of income decay.
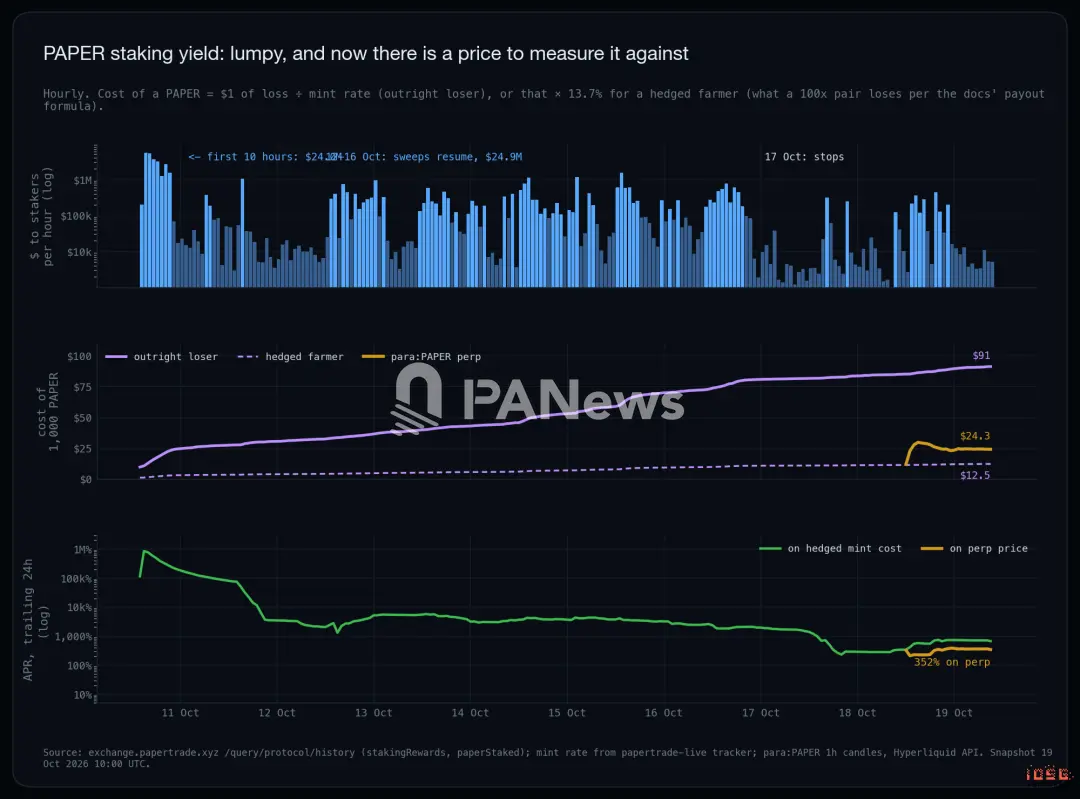
▲ PAPER Staking Yield: Comparing Mining Costs and Perpetual Price
How Long to Break Even
Looking only at cash, no one who entered on any day has broken even: those who lost money on the first day got back 0.58 times, and every batch after the 11th is at 0.15 times or below. When considering PAPER at perpetual price, the situation changes: those from the first day reached 2.2 times, and those from the 11th reached 1.0 times. After the 12th, those who directly lost money have not broken even, dropping from 0.83 times to 0.27 times. For those involved in wash trading, the break-even line is about 0.14 times, and every batch has crossed the line. Based on $0.024, the cheapest mining method can still make a profit, which is what the fourth part will discuss.
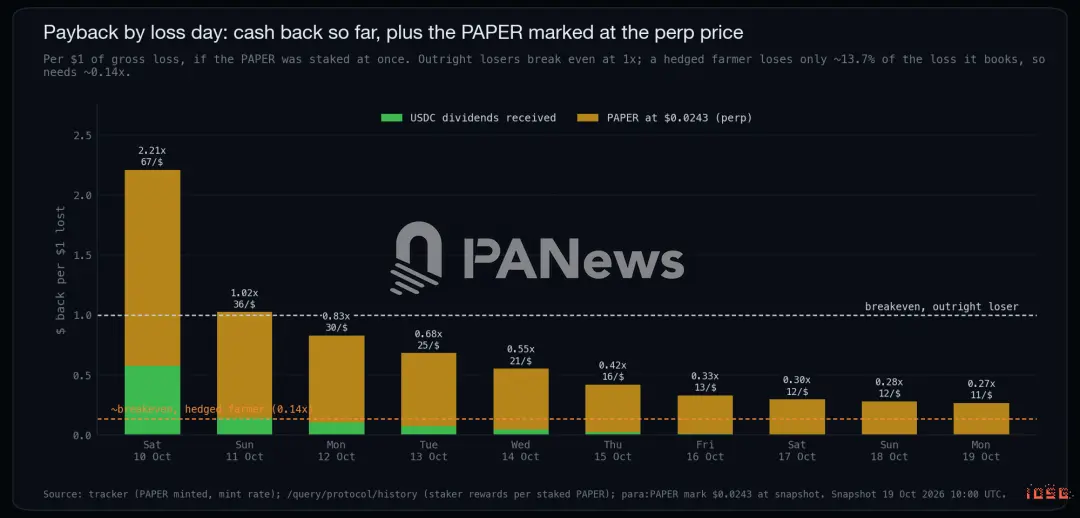
▲ Break-even Multiples by Loss Date
Reduction in Production and Activity
Activity follows mining returns. Hourly trading volume was $56 billion in the first ten hours, $7.5 billion on the 11th and 12th, $3.6 billion from the 13th to the 16th, and $2.3 billion on the 17th. Each turning point corresponds to changes in mining returns: the second wave occurred when the mining rate dropped from about 26 to 13, just before the limit was about to increase; the drop on the 17th was exactly on the day the limit was supposed to double; on the 18th, when the perpetual price rose above the mining cost, the volume increased.
The fee left per dollar traded also changed: on the first day it was 0.50 basis points, on the 11th and 12th it was between 0.21 and 0.34 basis points, from the 13th to the 15th it was between 0.61 and 0.76 basis points, on the 17th it was 0.13 basis points, and on the 18th it was 0.37 basis points. This aligns with the mechanism of wash trading: in a set of wash trades, one leg always loses completely, while the other leg has to be discounted, so the more aggressively it is traded, the higher the fee left per dollar.
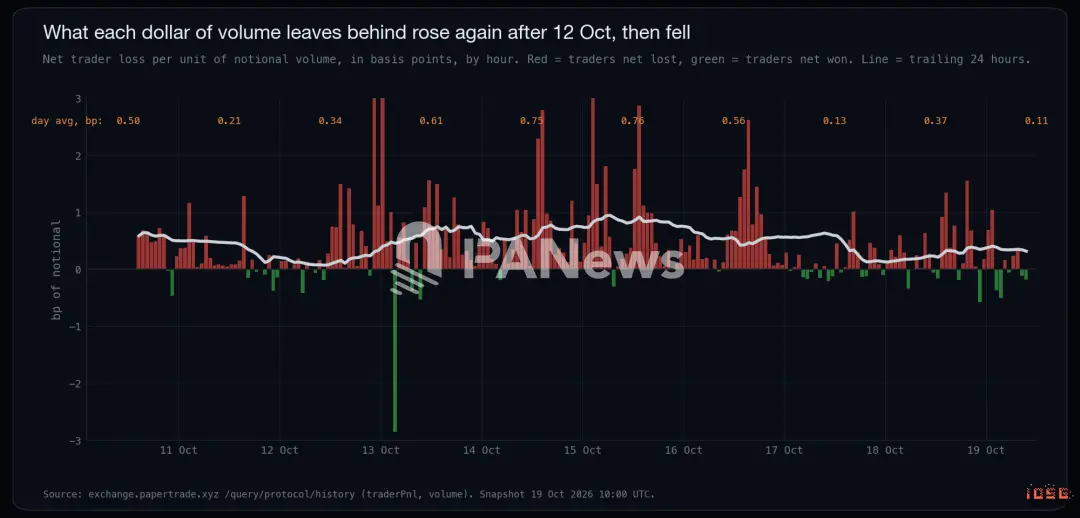
▲ Net Loss per Unit of Trading Volume
Launching Hyperliquid
What is Being Launched
para:PAPER is the perpetual contract of Paragon. Paragon is the HIP-3 deployer on Hyperliquid (the DEX named para), and this market was not opened by Papertrade nor by Hyperliquid officially. Paragon spent 570.98 HYPE (about $45,000) in the HIP-3 auction to acquire the PAPER code.
This is a pre-market: up to 3 times, only isolated positions, which will later convert to standard perpetual contracts.
The oracle uses its own marked price's 8-hour EMA, with an initial value set by Paragon at a reference price of $0.012.
There is no connection between it and Papertrade. PAPER cannot be transferred, no one can settle, and there is no spot to arbitrage.
Opened at 11:00 UTC on October 18, with positions of about $30,000.
Trends
After opening, it stayed at the reference price of $0.012 for an hour, just near the wash trading mining cost ($0.0125). Then it started to rise: at 13:00 it reached $0.023, peaking at $0.0352 in the hour at 13:00, dropping to $0.0198 at 19:00, and then remained around $0.0243. The 24-hour trading volume was $13.9 million, accounting for 70% of Paragon's total trading. Positions totaled 203.5 million coins, about $5 million. The funding rate is close to zero.
Based on $0.0243, 8.69 billion coins correspond to a market value of $211 million, and the limit of 12.7 billion coins corresponds to $308 million.
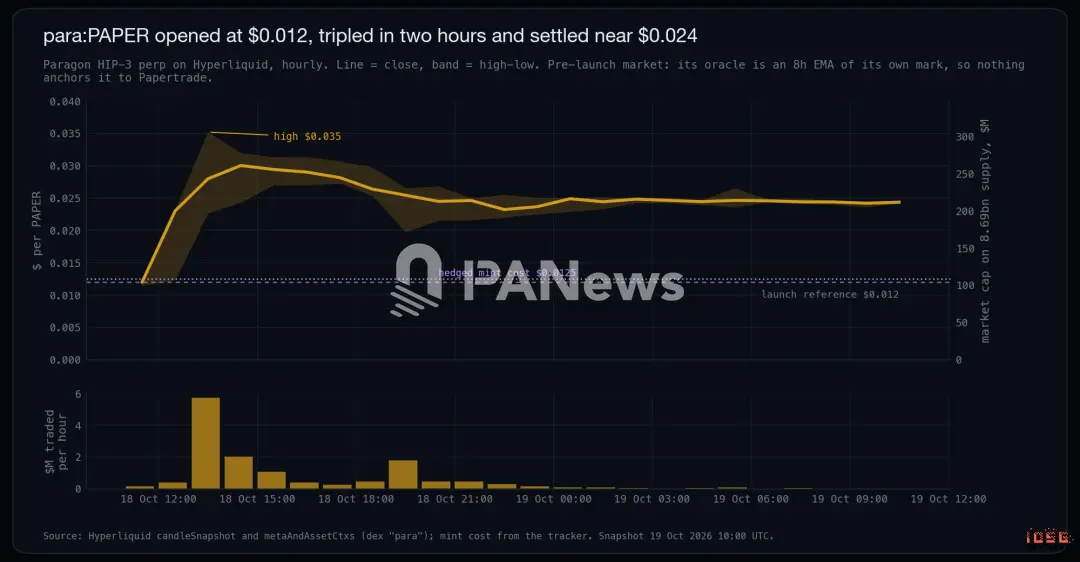
▲ para:PAPER Price and Trading Volume
Impact of Price on Mining
At $0.024, those who engage in arbitrage spend $0.0125 to mine PAPER, and the price given by perpetual contracts is almost double, making mining profitable again. In the 24 hours before launch, the gross loss was $300,000 per hour, which rose to $800,000 per hour 11 hours after launch. Stakers received $800,000 on the 17th and $2.1 million on the 18th. By the 19th, the excitement had dropped back to $350,000 per hour.
This arbitrage cannot be balanced out. You can mine PAPER cheaply and short it on perpetual contracts, but there are only about $5 million in positions on perpetuals, with a maximum of 3x leverage, and it can never be settled. Holders did not use it for hedging, at least not with the same wallet. Among the top 300 holders (accounting for 71% of the supply), only 6 opened short positions on para:PAPER, totaling 20 million tokens, which is about 0.3% of their holdings; another 5 opened long positions.
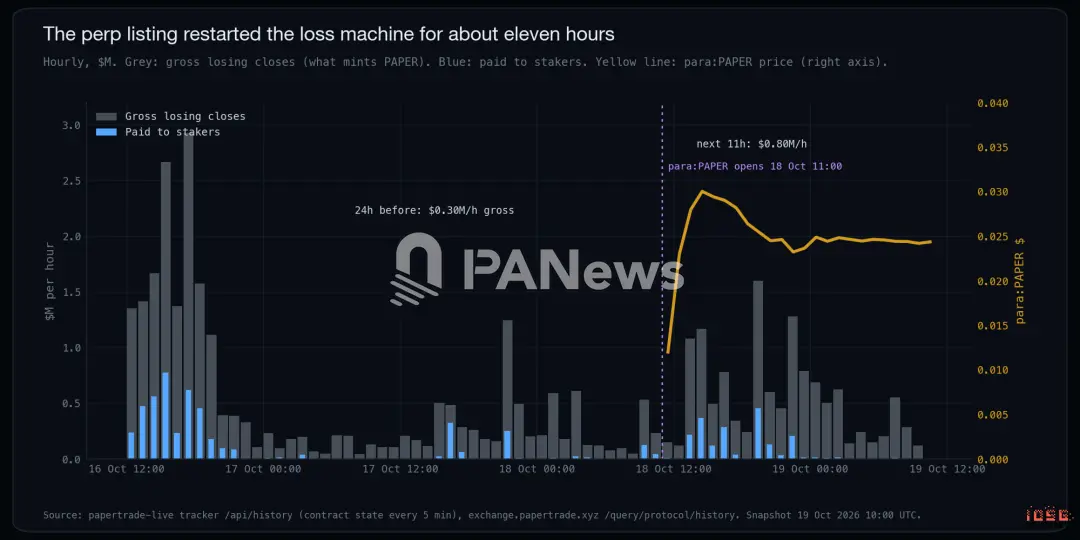
▲ Gross Loss and Staking Rewards Before and After Perpetual Launch
What This Price Means
· This is the first number that can price PAPER, indicating that PAPER is worth about twice the cost of arbitrage.
· It is thin and self-reinforcing: the oracle is the market's own EMA, with 3x leverage, and a $5 million position is pricing a $211 million token.
· It has an additional feedback loop: the higher the perpetual price, the more profitable mining becomes; the more mined, the greater the losses and staking rewards; the rewards further support the price. This loop will weaken itself because as H increases, the amount of PAPER mined for every dollar lost decreases.
Bullish: Liquidity Without Capital
First, acknowledge where it has done well. This design is new, and it has continued to operate as stated for nine days. The market maker did not raise a penny and withstood a $2.5 million withdrawal on the first day. Concerns about trapping winners did not materialize in the snapshots taken every five minutes, and the fair launch can be verified on-chain.
The strongest bullish argument lies in the structure. All rules lean in the same direction: losses are total losses, profits are discounted, and liquidations happen early. With increased trading, traders as a whole will inevitably lose more than they win, and the pool will fill up by itself. The data supports this: in the 212 hours since opening, traders as a whole have only had 41 hours of net profits, totaling $3.7 million, while the other 171 hours were losses.
From another perspective, this is a form of liquidity that grows out of trading. Other methods of launching perpetual contracts require upfront capital: order books need market makers; oracle-priced pools like GMX's GLP or Jupiter's JLP require depositors to take every counterparty trade, and they need to earn; opening a HIP-3 market on Hyperliquid requires staking 500,000 HYPE, and then you have to find a market maker yourself. The Papertrade pool started from zero, hitting the $5 million cap about 70 minutes after opening, and since the 12th, it has never exceeded $800,000 from the cap, with no seed funding and no LP incentives.
Thinking one step further, it can become a template for permissionless perpetual issuance. A market only needs two things: a readable price and a pool. The documentation already states that any Hyperliquid perpetual can be launched, including HIP-3. Once deployment tools are available, with each market having its own pool, anyone can issue a perpetual just like issuing tokens on pump.fun.
The ceiling is in the price source. 0x2025 only spent about $52,000 in fees to push ETH by 0.12%; a thinner HIP-3 market is cheaper. To create a permissionless version, the position limit of each market must be linked to the depth of its oracle order book.
Potential Problem Areas
· Tokens are claiming future losses, and losses come in waves, following mining rewards. From the 12th to the 16th, stakers received $24.9 million, but only $800,000 on the 17th. The 17th was the only day we had no reason to mine, and stakers received only about one-sixth of what they got the day before.
· The later you enter, the more expensive it becomes. Currently, losing $1 only exchanges for 10.9 PAPER, while at the opening it was 100 PAPER, and 69% of the cap has already been issued. Arbitrage increases supply but does not bring cash to LPs. Once PAPER can be transferred, for anyone other than those engaging in arbitrage, buying directly will be cheaper than losing money mining.
· The oracle only looks at one number: a single buy and sell midpoint, with no TWAP or deviation circuit breaker, while on Hyperliquid, a few million dollars can push ETH by 10 to 20 basis points. Limxn6 also mentioned that a pair of legs engaging in arbitrage encountered a price gap, equivalent to getting a straddle option for free, with this tail borne by LPs.
· Relayers can be audited. They sort by order size, and external auditing is not possible; relayers and liquidation keepers are run by the same team.
· The most important price signal has no anchor. para:PAPER can change mining incentives and market narratives without any changes from Papertrade. The team’s own announced cap adjustments have not been executed, leaving stakers unable to predict their income based on announcements.
The pool is safer than before. It currently holds $529 million, with a net long of $64 million and a pool of $4.7 million. BTC and ETH need to rise about 3.7% from the opening prices of these positions for the amount owed to winners to exceed the pool plus the losers' margin. On the first day, this number was 0.7%. The closest it has been in the past week was 2.2% on the 15th, with the maximum hourly volatility for BTC/ETH being 4.3%.
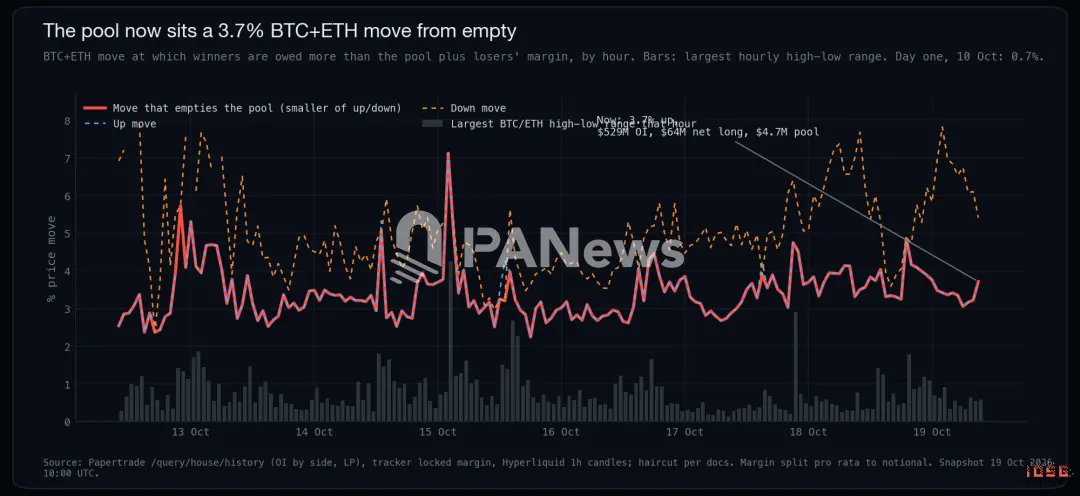
▲ Price Fluctuation Required to Empty the Pool
Conclusion
Mechanically, it has delivered on its promises. The market maker did not raise funds and has been able to pay out for nine days without a single winner queuing up; 86% of the net losses have been returned to stakers, who are essentially the wallets that are losing money.
When looking at yield products, PAPER claims a share that will surge whenever mining is profitable, along with a 1% fee sharing. It now has a price, with the thin perpetual at $0.024, about twice the cost of arbitrage mining.
As long as this price difference exists, the perpetual is paying people to lose, and the losses are fed back to stakers. Once the price difference disappears, income will revert to the level that pure 1000x gambling can leave: the 17th was the only calm day, and stakers received $800,000 that day.
What to watch next:
· PAPER opens for transfers. This is the fourth phase of the roadmap, with no timetable. With spot trading, the perpetual will have an anchor, and those who are inflating volume can also sell.
· $10 million cap. If it is truly raised, the overflow will stop for several days.
· New markets. The documentation states that any Hyperliquid perpetual can be launched. New markets bring new losers, which is the only thing that can add water to the tank.
· Perpetual position volume. $5 million cannot support real hedging. If it rises, it can be expected that holders will go short.
· Mining rate. It is currently 10.9. For every additional $100 million in gross loss, the mining rate will drop by more than one-third; for mining to be profitable, the price of PAPER must keep increasing.
 Risk warning