








The Huang Renxun controversy coincides with earnings report week: Nvidia's channel in China, tightening at both ends?
 The focus of attention is on the ripple effects of personal controversies. Jensen Huang's private relationship incident has brought to light two existing business risk factors for NVIDIA in China: U.S. export controls and Chinese import approvals, just as the timing coincides with the earnings report on November 17. The questions that need to be answered now fall on the revenue side: will this controversy change NVIDIA's revenue trajectory in China for the next few quarters?
I. The Personal Scandal Has Become Corporate, but the Real Danger Is Not the CEO's Ethical Issues
The investigation targets national security risks, and the authority has been transferred to the board of directors.
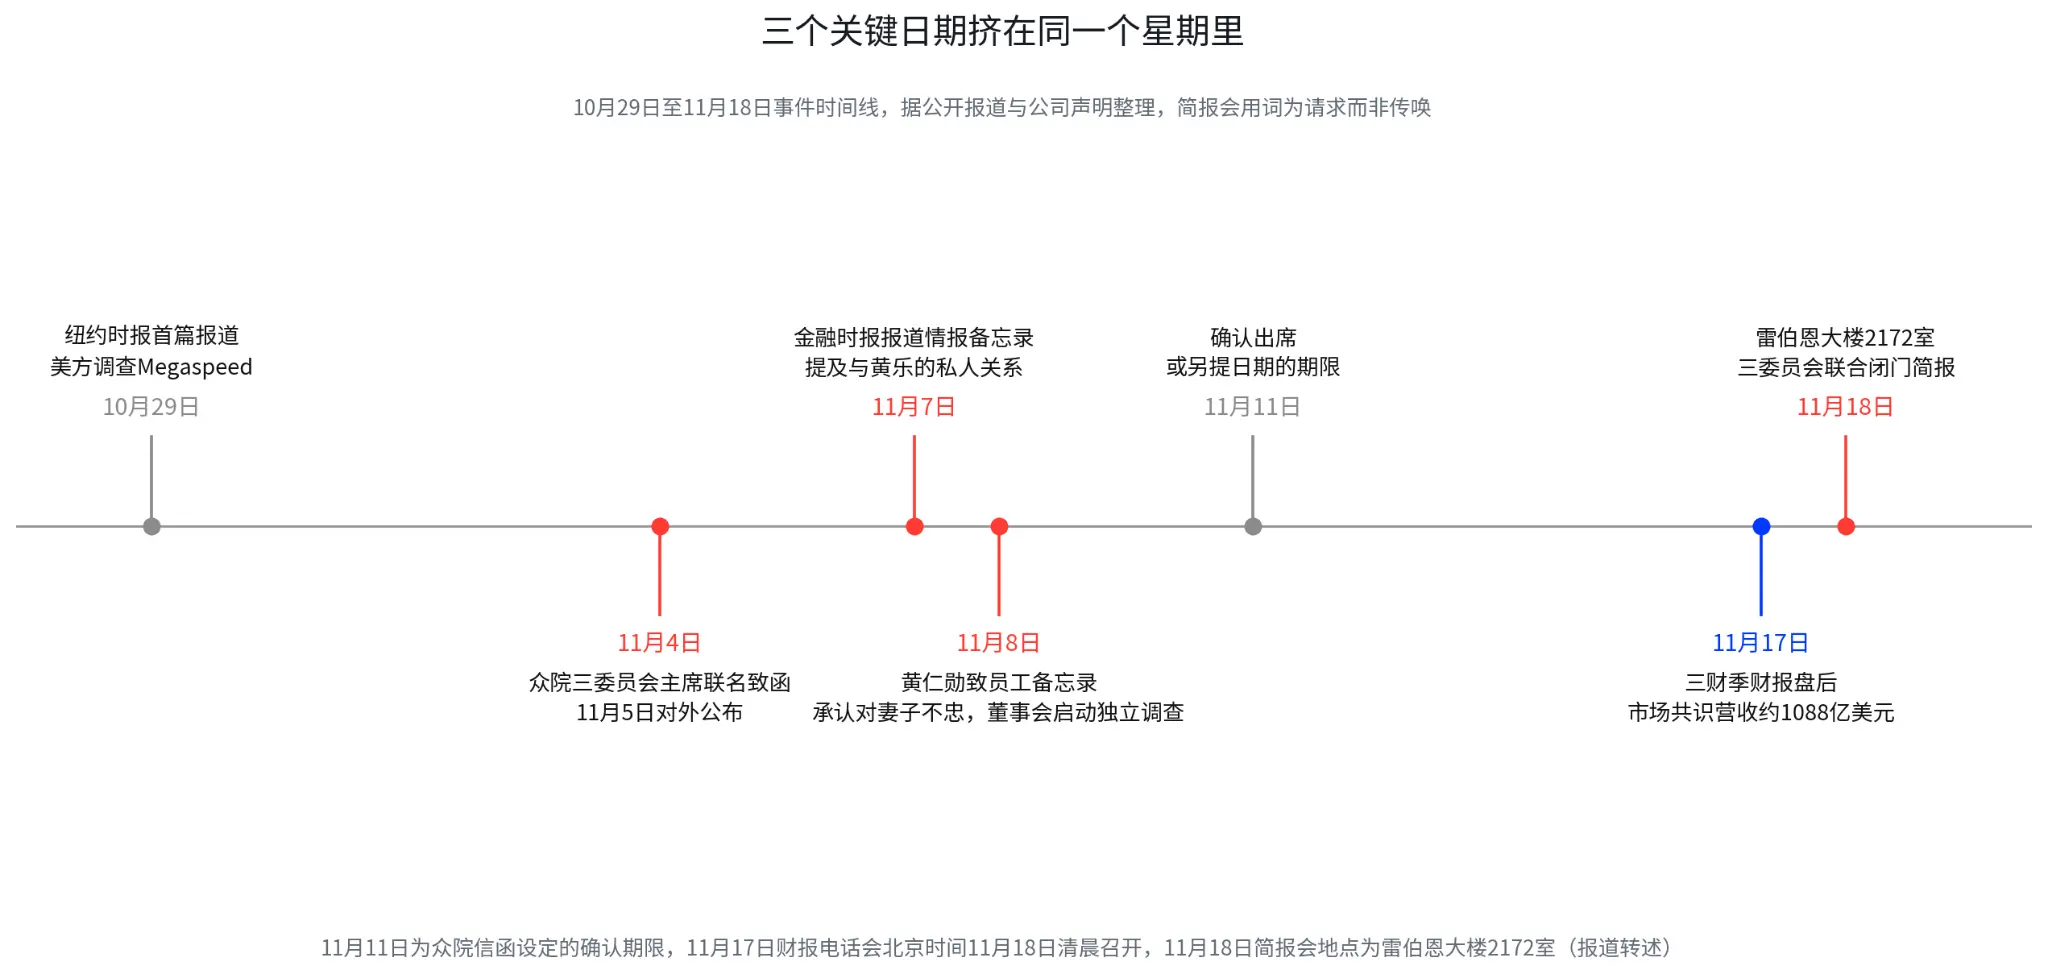
On November 8, Jensen Huang admitted to infidelity and apologized to employees (full text published by Bloomberg). On the same day, the NVIDIA board announced the initiation of an independent investigation, which is directed at foreign intelligence operations mentioned in recent media reports, overseen by the independent director committee with assistance from external independent legal counsel. The board also stated that there is currently no reason to believe that U.S. national security or NVIDIA's confidential information has been compromised, and Jensen Huang himself has committed to cooperating with the investigation (company statement, reported by various media).
This distinction is important. Public information does not indicate that Jensen Huang has been accused of a crime, nor can it be concluded that he participated in any intelligence activities. What the market should really focus on is whether the independent investigation will change the board's judgment on this matter and whether the investigation results will further enter the U.S. Congress and export control system.
Congress has already taken action. On November 4, the chair of the House Foreign Affairs Committee, Michael McCaul, the chair of the China Select Committee, Mike Gallagher, and the chair of the Permanent Select Committee on Intelligence, Eric Crawford, jointly sent a letter, which was publicly announced on November 5, requesting Jensen Huang to attend a closed-door briefing on November 18, focusing on his interactions with Megaspeed executive Alice Huang, as well as the security measures NVIDIA has taken regarding foreign competitors obtaining sensitive technology and information, and to confirm attendance or propose alternative dates by November 11 (statement from the House Foreign Affairs Committee and reported by various media).
Word choice needs to be scrutinized; this letter is not a subpoena in the strict sense but a closed-door briefing request issued by the three committees. The policy risk lies in the next steps; if formal hearings, subpoenas, or amendments to export controls arise after November 18, or if the Department of Commerce imposes new approval restrictions on NVIDIA's business in China, this matter will shift from a corporate governance issue to a revenue issue. November 18 is closer to the starting point of the policy chain, and risk validation follows.
The Democrats are also preparing their ammunition. Chris Coons, who is expected to become the chair of the Senate Foreign Relations Committee, has stated on X that he will investigate the related reports. Elizabeth Warren, who is expected to chair the Senate Banking Committee, has long demanded that Jensen Huang testify publicly about sales in China, which was previously denied. Trump's statement on October 31 was, "I have always thought Jensen Huang is very upright," followed by, "This is a very complicated issue" (reported by various media).
II. $4.8 Billion Procurement and "Every Unit Counted," the Real Controversy Lies in the Compliance Chain
The cases in Congress have names, amounts, and procurement records, with the controversy centered on whether the compliance chain can be independently verified.
Megaspeed is a company building data centers in Southeast Asia, providing computing power services to Chinese clients and is one of NVIDIA's important customers (reported by the Associated Press). Customs records from the trade data platform ImportGenius show that Megaspeed's affiliated company in Malaysia procured at least $4.8 billion worth of AI equipment containing NVIDIA chips and related technologies from June 2024 to February 2026 (reported by The New York Times).
$4.8 billion is the procurement amount, and public information has yet to prove that this batch of equipment illegally entered mainland China. The intelligence clues reported by the media have not reached judicial determination, and neither Huang Le nor anyone from Megaspeed has been formally charged. Jensen Huang's personal relationships with relevant personnel also do not imply NVIDIA's involvement in illegal activities.
NVIDIA has previously denied that Megaspeed shipped NVIDIA AI chips to China, and Jensen Huang stated that the company has verified the deployment of the relevant GPUs, saying, "We have studied the deployment of all their GPUs, and every unit has been counted" (reported by Hong Kong Economic Journal). The board's initiation of an independent investigation effectively hands over the explanations previously made by management to independent directors and external legal counsel for re-examination.
This statement has thus become sensitive. Whether the counting results can withstand independent verification by the U.S. government, Congress, and subsequent investigations is more critical than whether the counting was done. If the final conclusion is that the equipment did not illegally enter China, the impact of this matter will likely remain at the level of political noise and compliance costs. If the investigation finds loopholes in the export control system, or if Congress determines that the existing approval and tracking mechanisms are insufficient, NVIDIA will face stricter customer reviews, GPU flow monitoring, and sales restrictions in China.
NVIDIA's recent actions connect with this background. The company is requiring some Southeast Asian cloud customers to join its Fleet Intelligence monitoring system, disclosing the deployment locations and operational information of accelerators as a condition for obtaining NVIDIA cloud partner status (reported by Bloomberg on November 6). The future costs of the China business will thus exceed merely whether it can sell, but also include to whom it sells, where it is deployed, and whether it can continuously prove that no transshipment has occurred.
III. The Real Revenue Risk Lies in H200: Washington Has Approved, but Beijing Has Not Released on a Large Scale
If this week's political news is compressed into one market variable, it is four words: Chinese revenue.
NVIDIA's earnings announcement for the last quarter made it very clear that the $108 billion revenue guidance for the third quarter does not include revenue from data center computing in China. CFO Colette Kress also disclosed that revenue from data center products shipped to the Chinese market accounted for less than 1% of total data center revenue in the second quarter (company earnings announcement, reported by First Financial, August 27). This means that even if the Chinese market resumes some H200 sales, as long as it is not large-scale and stable commercial shipments, it cannot be interpreted as an upward surprise outside the company's guidance.
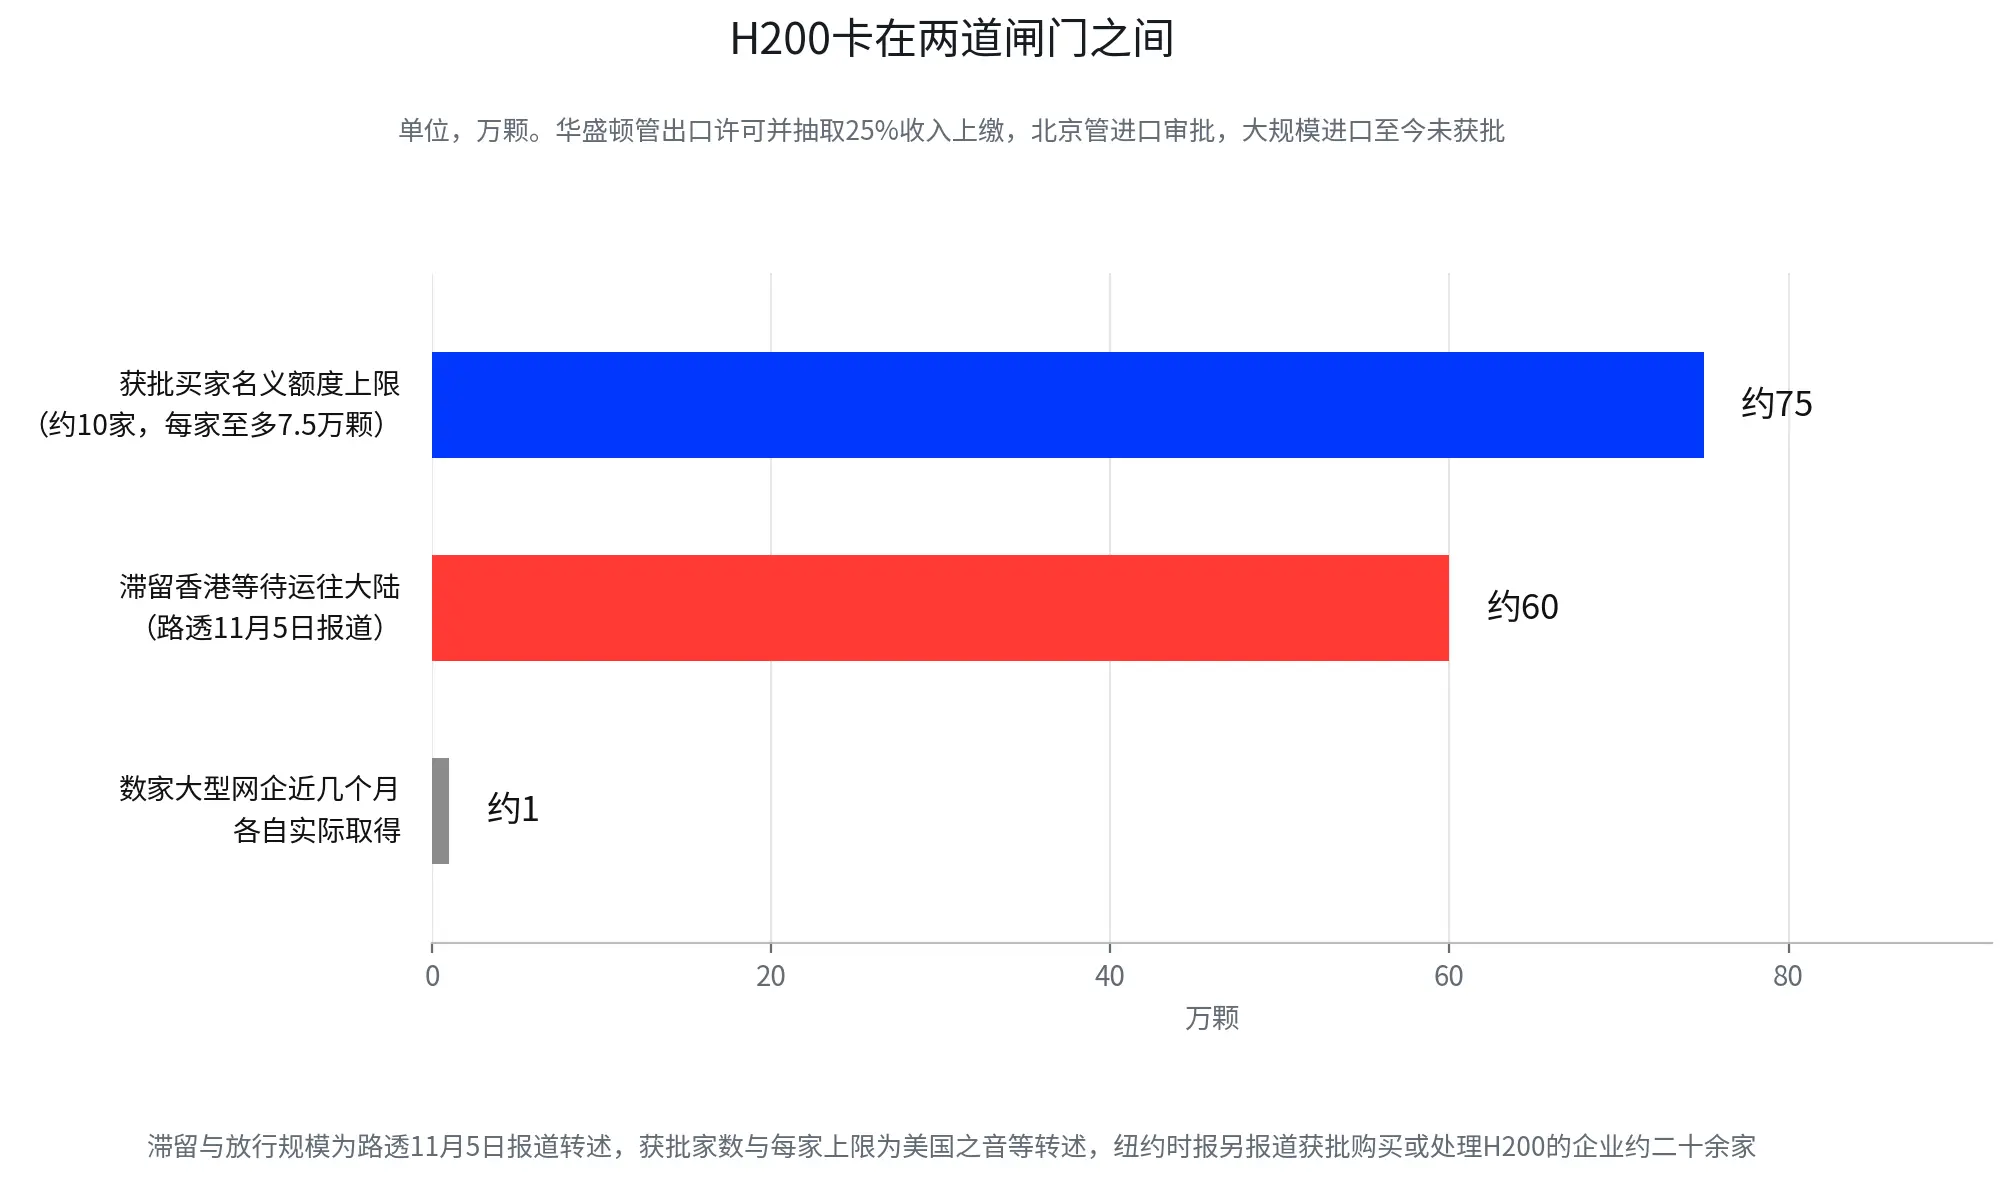
The H200 is currently caught between two regulatory systems. On the U.S. side, the Biden administration has banned H200 exports to China, and Trump overturned the ban on December 8, 2025; the Department of Commerce subsequently approved about ten Chinese companies to purchase up to 75,000 units each, with transactions still subject to the licensing system (reported by Voice of America). On the Chinese side, large-scale entry of H200 into mainland China has not been approved; Reuters reported on November 5 that about 600,000 H200 units are stranded in Hong Kong, with several large Chinese internet companies each obtaining about 10,000 units in recent months, along with a small number entering through intermediaries and indirect channels (reported by Reuters). The New York Times investigation also found that about twenty Chinese companies have been approved to purchase or process H200, with New Matrix's registered address in Beijing being an empty office space (reported by The New York Times).
NVIDIA is facing a unique inventory situation where the goods have arrived in Asia, but revenue has not been realized. This is different from the usual sense of poor demand; Chinese customers have demand, the products have been produced, but approvals have not been completed, preventing normal large-scale sales confirmations. The longer the inventory remains, the higher the policy uncertainty, making it more difficult to judge the customer procurement rhythm.
Prices are speaking for scarcity. A server equipped with eight H200 units in the Chinese market is quoted at over 6 million RMB, about three times the price from a year ago (reported by World News via Reuters). Demand exists, but the channel is blocked by policy; this is an accurate description of the current state of H200. Therefore, the market should not interpret this as NVIDIA losing the Chinese market; a more accurate interpretation is that the potential demand in the Chinese market still exists, and the proportion that can be converted into NVIDIA's reported revenue increasingly depends on the regulatory policies of both countries.
Jensen Huang's congressional briefing is worth monitoring for this reason. It may not immediately reduce revenue for any quarter, but it could change the probability of policies in the coming quarters.
IV. Earnings Reports, Congress, and Stock Prices Collide in the Same Week, a Real Trading Window Has Formed
This round of adjustments occurred before the investigation results, with the market already trading in advance on the dual risks of policy and earnings reports.
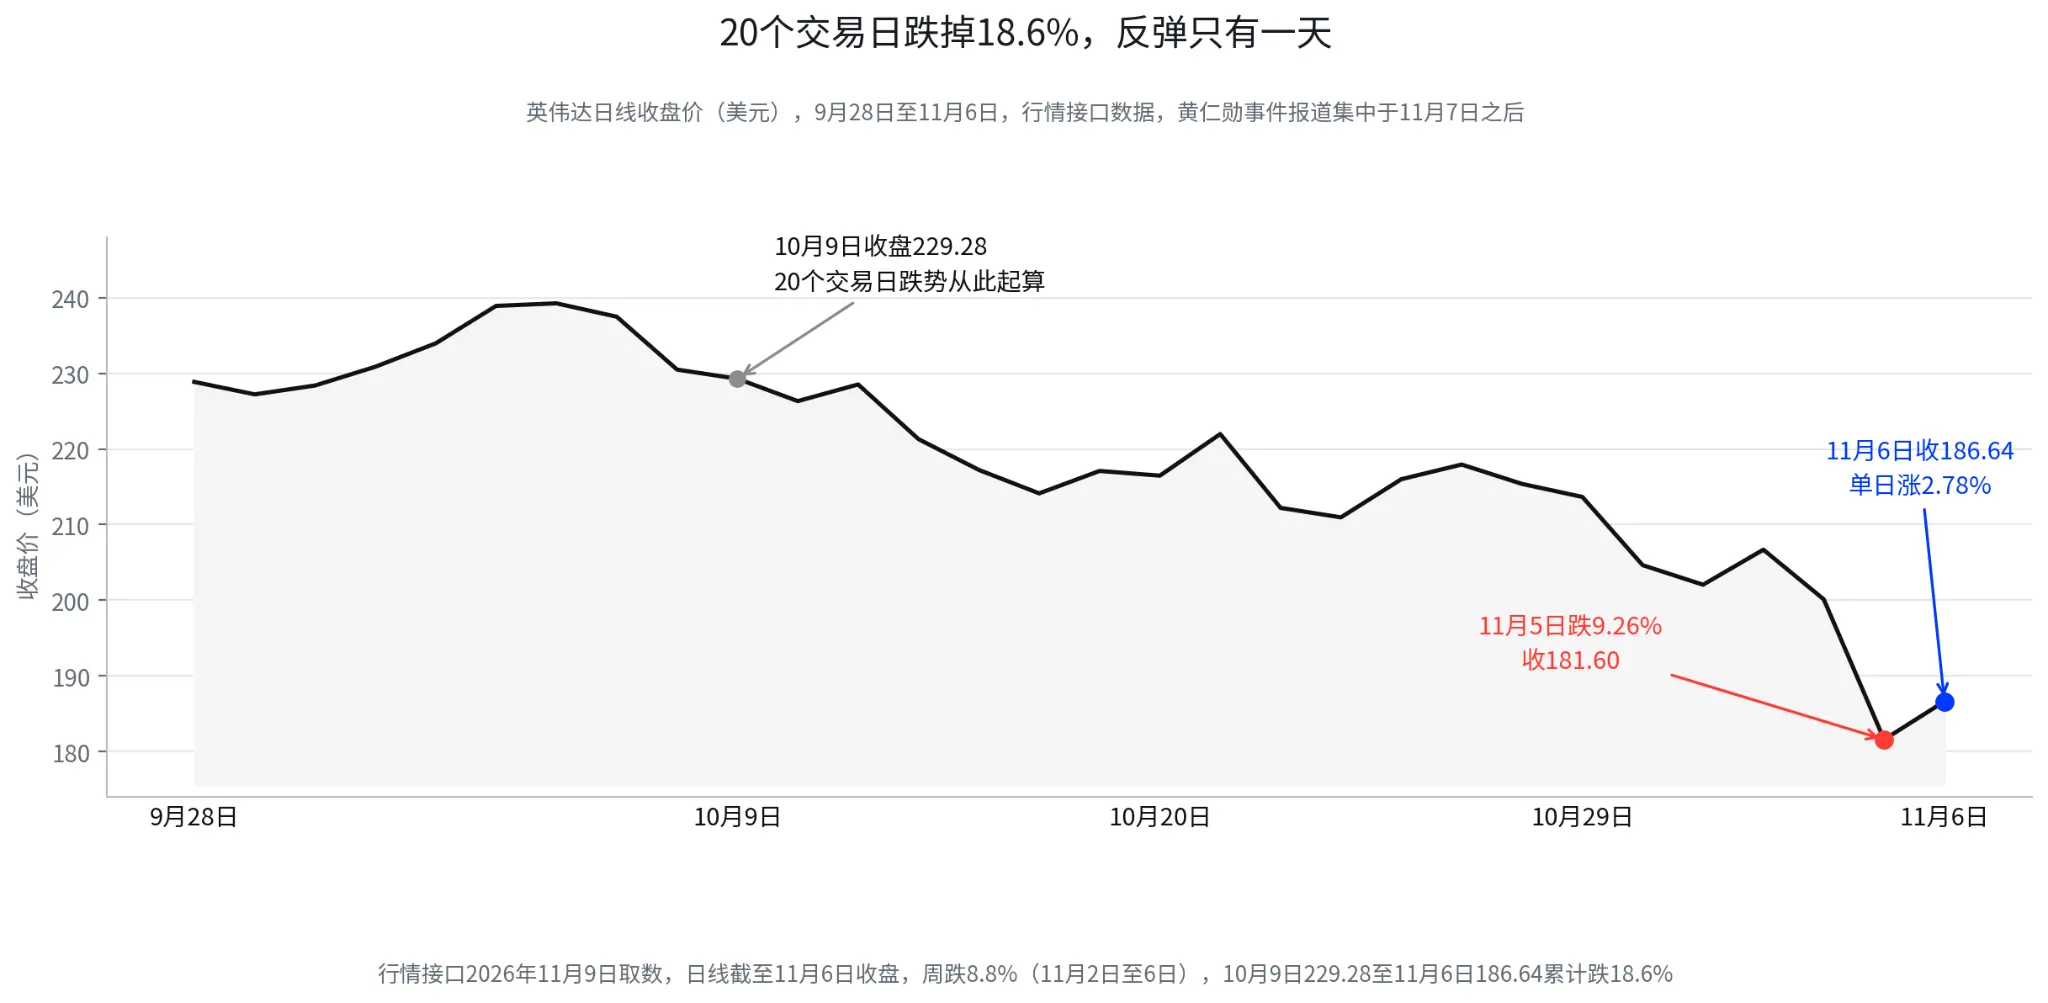
On November 5, NVIDIA fell 9.26% in a single day, closing at $181.60, with a trading volume of 306 million shares. On November 6, it rebounded 2.78%, closing at $186.64. From the closing high of $239.24 on October 6, the current price has dropped about 22%, with an 18.6% cumulative decline over the past 20 trading days (market data interface). It is still unclear whether this round of decline is a risk reassessment or an emotional deleveraging before the earnings report.
The upcoming week is information-dense.
On November 11, the deadline for Jensen Huang to confirm the congressional closed-door briefing request.
On November 17, NVIDIA will release its Q3 earnings report for fiscal year 2027, and the company has confirmed the release and conference call arrangements (company calendar).
On November 18, Jensen Huang will attend the congressional closed-door briefing, provided it proceeds as originally planned.
The checklist for earnings night is clear: whether data center revenue can continue to significantly exceed guidance, whether orders and supply for Blackwell and subsequent platforms remain strong, and whether there are any changes in management's latest statements regarding the China business. The company guidance is $108 billion with a 2% fluctuation, gross margin around 74% with a fluctuation of 50 basis points, and the market consensus is about $108.8 billion (MarketBeat summary, reported). FactSet's records show that in the past 20 quarters, data center revenue has only missed expectations three times, averaging 5.1% above expectations (reported by Economic Daily).
If data center revenue continues to significantly exceed guidance, and management does not further lower expectations for the China business, and no new regulatory actions arise after the November 18 briefing, this round of decline is more likely to be a combination of policy noise and high valuation deleveraging. If there are no issues with the earnings report itself, but new export control amendments, tightening of Department of Commerce approvals, or the company proactively lowers expectations for the China business occur after the briefing, the market will need to recalculate not just one quarter's revenue, but how much revenue NVIDIA can obtain from the Chinese market in the coming quarters, and whether this portion can still be counted towards growth expectations. The impact of these two scenarios on valuation is entirely different.
V. In Conclusion: The Probability of Chinese Policy Implementation, Not Chinese Revenue
Jensen Huang's admission of an extramarital affair does not have direct financial model implications, and the board's independent investigation does not equate to NVIDIA having violated national security. What is worth placing on the trading table is whether this scandal will change the U.S. regulatory attitude towards NVIDIA's business in China.
The current state of the Chinese channel is tightening at both ends: the U.S. controls export licenses, and China controls import approvals. About 600,000 H200 units are stranded in Hong Kong, and the demand from Chinese customers is evident, but what is blocked is the conversion of demand into actual sales.
The signals worth monitoring next, in chronological order, are the gap between data center revenue and guidance in the earnings report on November 17, whether there are legislative texts, subpoena procedures, or Department of Commerce approval restrictions after the briefing on November 18, and when the H200 in the Hong Kong warehouse will be converted into actual shipments. Look at the earnings report on November 17, the policy on November 18, and then see if Chinese revenue can be realized, with the pricing chain unfolding in this order.
Data Explanation
Market: Closed at $181.60 on November 5 (down 9.26%, volume 306 million shares), closed at $186.64 on November 6 (up 2.78%), down about 22% from the high of $239.24 on October 6, with an 18.6% cumulative decline over the past 20 trading days (market data interface, data collected on November 9).
Apology letter and board independent investigation: both on November 8 (Bloomberg, company statement, reported by various media).
Congressional Letter: Sent on November 4, announced on November 5, closed-door briefing on November 18, confirmation before November 11 (statement from the House Foreign Affairs Committee)
Megaspeed Procurement: At least $4.8 billion from June 2024 to February 2026 (New York Times, October 29, citing ImportGenius), $4.8 billion is the procurement amount, not the verified amount for illegal transshipment
Q3 Guidance: $108 billion plus or minus 2%, excluding revenue from data centers in China, revenue from data centers in China accounted for less than 1% in Q2 (company performance announcement on August 26, First Financial, August 27, citing)
H200: Authorized for export on December 8, 2025, about 600,000 units stranded in Hong Kong, large-scale imports not approved, quotes for 8-card servers exceed 6 million yuan, about three times the price from a year ago (Reuters, November 5, etc., citing)
Disclaimer: The content of this article is for general information and market commentary only, compiled based on publicly available information as of the time mentioned in the text. Relevant market data, expectations, and probabilities may change with market conditions. The views and investment strategies of third-party institutions, analysts, or other individuals quoted in the text represent the views of the relevant third parties at a specific time and do not represent the views or recommendations of BIT. This article does not constitute investment advice, investment research, solicitation, or recommendation of any securities, investment products, or trading strategies, nor should it be used as the basis for any investment decision. Financial markets carry risks, and securities prices and market performance may fluctuate; past performance and historical market trends do not represent or guarantee future results. Investors should independently assess the relevant risks based on their own circumstances and seek professional advice when necessary.
 Risk warning Risk warning
Popular articles





