On the first day of the full launch of GPT-6, the Dow Jones Industrial Average fell over 340 points: When AI's "AGI moment" meets "higher and longer."

 Most reports focus on "most officials support another interest rate hike within the year." However, there is a statement in the minutes that has been relatively less mentioned in public reports: some participants believe that the development of artificial intelligence may lead to total demand exceeding supply in the medium term, thereby creating upward pressure on inflation.
On October 7, two events occurred on the same day, with differing directions.
OpenAI fully launched GPT-6 for all ChatGPT users worldwide, with paid users (Plus, Pro, Business, Enterprise) being powered by GPT-6 Sol from that day, while Free and Go users would switch to GPT-6 Luna starting October 8. A new capability called Intelligent UI was introduced, allowing responses to dynamically combine text, charts, and interactive components based on the type of question. According to official data from OpenAI, the weekly active users of ChatGPT exceeded 1.2 billion.
On the same day, the Federal Reserve released the minutes from the September meeting. All 19 officials present unanimously supported the rate hike in September, with most participants believing that further rate increases may be necessary before the end of the year. Participants generally emphasized that inflation remains high and the labor market is close to full employment, with inflation risks skewed to the upside.
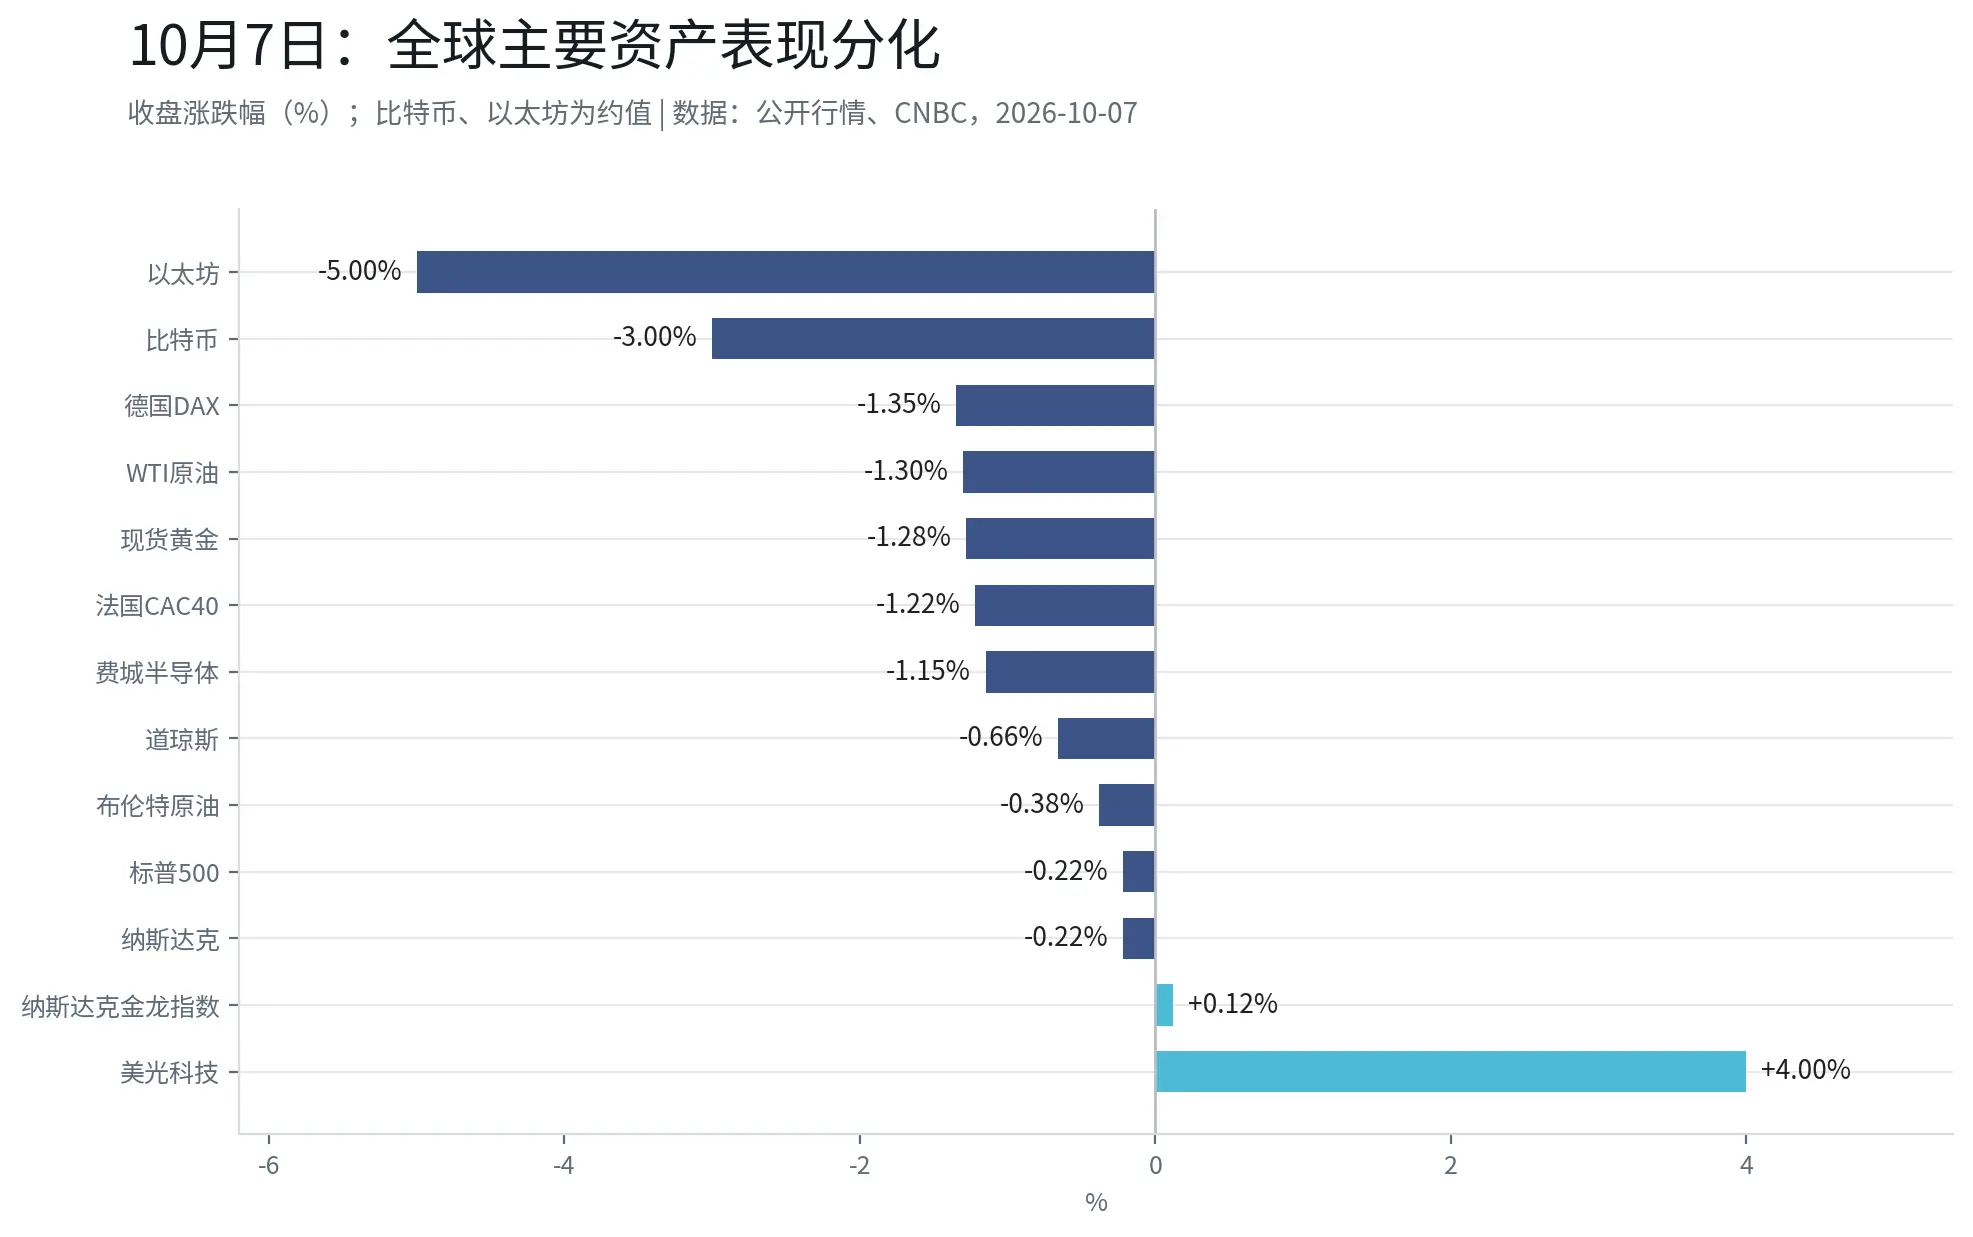
On one side is the market narrative of an "AGI moment," and on the other is the central bank's stance of "higher for longer." That day, the three major U.S. stock indices fell from record highs the previous day: the Dow Jones Industrial Average dropped 341.41 points to 51,179.87 (-0.66%), the S&P 500 fell 0.22% to 7,801.77, and the Nasdaq declined 0.22% to 27,538.69. Europe saw even larger declines—Germany's DAX fell 1.35%, and France's CAC40 dropped 1.22%. Aside from the rise in U.S. Treasury yields, concerns about French finances and high oil prices were also considered reasons for the pressure on European stocks that day.
1. A Noteworthy Sentence in the Minutes
Most reports focused on "the majority of officials supporting another rate hike this year." However, there was a statement in the minutes that has been relatively less mentioned in public reports: some participants believed that the development of artificial intelligence could lead to total demand exceeding supply in the medium term, thereby creating upward pressure on inflation.
The weight of this statement may be comparable to "another rate hike this year." In the Federal Reserve's discussions on inflation, AI capital expenditure itself is listed as one of the variables that could push total demand higher, rather than just a neutral narrative of "technological progress." Based on this inference: if the commercialization of AI and the expansion of computing power continue to accelerate, it could provide additional justification for a "higher for longer" rate path—this is an interpretation based on the original minutes, and directional judgments still carry uncertainty.
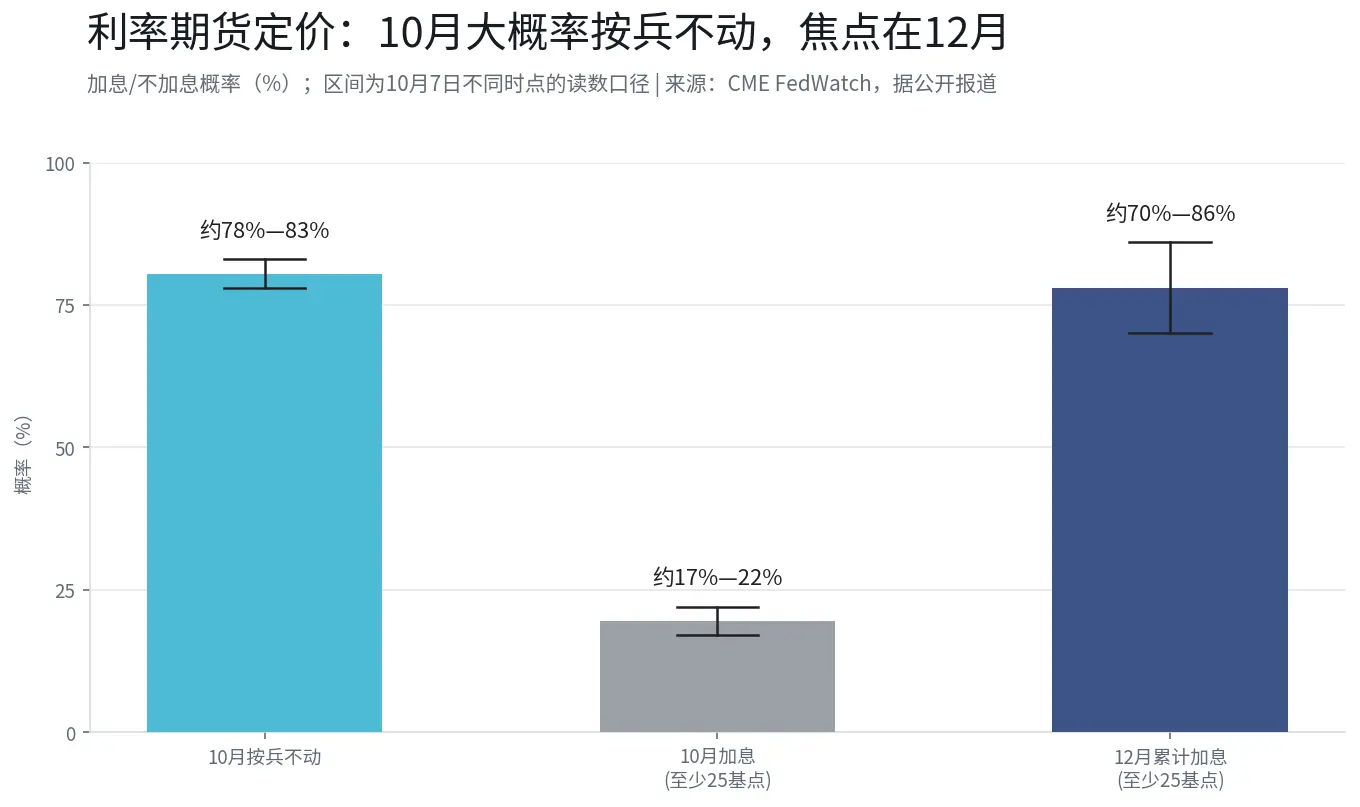
Current market pricing lies between the two. According to CME FedWatch data (with slight variations at different times on October 7), the probability of a rate hike of at least 25 basis points in October has dropped to about 17%—22%, while the probability of a cumulative rate hike of at least 25 basis points by December is around 70%—86%. The signal conveyed by the market is that October is likely to remain unchanged, while the December meeting may be one of the more critical observation points.
2. U.S. Treasuries: 10-Year Auction Demand Exceeds Expectations, but the Real Issue is the Long End
One of the most closely watched asset price movements that day occurred in the bond market.
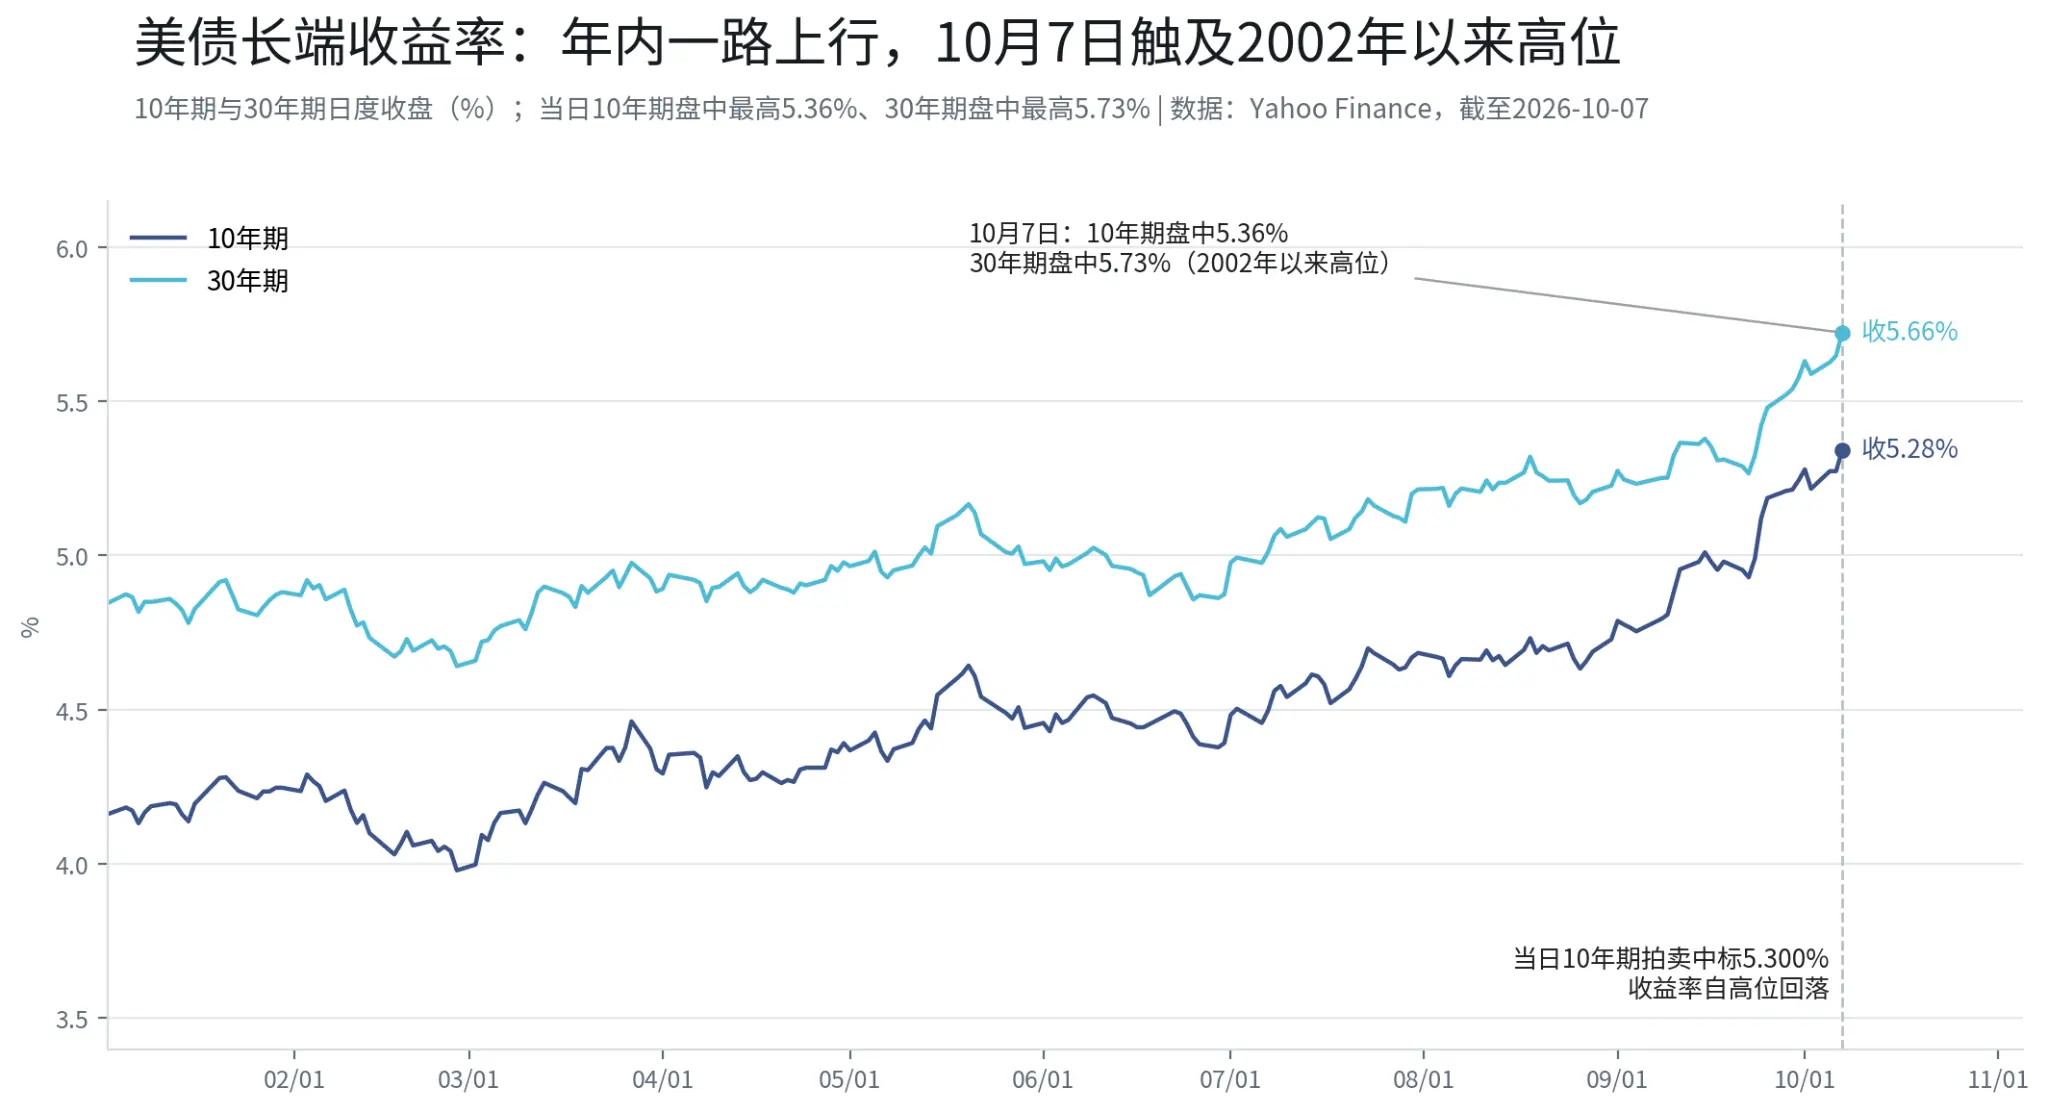
The yield on the U.S. 10-year Treasury bond briefly rose to 5.364% during the day (according to Reuters, the highest since April 2002), while the 30-year bond touched 5.70%—5.73% (the highest since May 2002). By the close, both had retreated to around 5.28% and 5.66%, respectively. According to public reports, U.S. Treasury officials responded that the current round of bond selling is a "global phenomenon"—with long-end rates rising in the U.S., Europe, and Japan, driven by inflation expectations after oil prices surpassed $100, as well as the higher compensation demanded by investors to absorb the large supply of sovereign debt.
However, an important counter-evidence on October 7 was the $39 billion 10-year Treasury auction, which had a bid-to-cover ratio of 2.77, significantly higher than the recent average of 2.54; primary dealers received only about 2.5%, a low since the financial crisis—indicating that about 97.5% of the issuance was taken directly by non-dealers. Indirect bids (including global central banks and other institutions) received 80.3%, higher than the recent average of 72.4%.
One interpretation is that when yields rise above 5.3%, some long-term allocation funds (pension funds, insurance, sovereign wealth funds) may be shifting from "avoiding the long end" to "disciplined allocation to the long end." These funds have internal discipline regarding yield levels; if it is high enough, they will allocate. However, a single auction is not sufficient to confirm a trend—and it should be emphasized that it validates the demand for the 10-year bond.
After the auction results were announced, the 10-year yield fell back to around 5.28%—5.30%. The decline in yields occurred after the auction: the most significant marginal change in the bond market that day may not have been economic data, but rather the emergence of buying interest.
3. 30-Year Bonds: More Worth Watching than 10-Year Bonds
If the 10-year bond was the "pricing anchor" of the day, the 30-year bond may be where the pressure is most concentrated.
In terms of levels, both are actually equally extreme: the 10-year bond's intraday high of 5.364% is the highest since April 2002, while the 30-year bond's intraday high of 5.70%—5.73% is the highest since May 2002; according to market data, both are currently near the 98th percentile of their 52-week range. Looking solely at the increase, the 30-year bond is not steeper than the 10-year bond—since early September, the 10-year yield has risen from about 4.79% to 5.28%, while the 30-year yield has risen from about 5.27% to 5.66%.
What makes the 30-year bond "more astonishing" are three structural reasons.
First, this is the end that the central bank cannot control. Policy rates directly determine the short end, while the pricing power of the 30-year yield lies in the market—it is composed of inflation expectations and term premiums. When the Federal Reserve says "higher for longer," the short end follows the policy path; however, the rise in the 30-year bond seems more like the market voting on fiscal paths and long-term inflation. According to public reports, the pressure on the long end during this round of selling has been greater than on the short end, with the spread between the 10-year and 30-year yields maintaining a positive steep shape of about 35—40 basis points—the market is not pricing according to "recession inversion," but rather according to "inflation and supply premiums."
Second, duration amplifies volatility. The duration of the 30-year bond is about twice that of the 10-year bond; under the same yield increase, the price decline is significantly larger. For pension funds and insurance institutions holding long-duration bonds, the 30-year bond is the segment under the most valuation pressure; for issuers (the U.S. Treasury), it is also the most expensive segment of financing.
Third, the answer from the 10-year auction cannot be automatically extended to the 30-year bond. The October 7 auction showed that allocation funds were willing to take on the 10-year bond at a yield of 5.3%; however, the liability duration for pensions and life insurance primarily falls within the 20—30 year range. Whether there is similar demand for the ultra-long end will need to wait for the October 8 30-year auction to answer. If the 30-year auction is similarly strong, evidence for a "top" in long-end rates will increase; if it is significantly weak, it indicates that allocation funds are only willing to extend to the 10-year bond, and the pressure on the 30-year bond has not yet been relieved.
With oil prices maintaining above $100, the transmission of inflation expectations to the ultra-long end is also more direct. The results of the 30-year auction and subsequent inflation data may explain how far this round of rate increases can go better than the movements of the 10-year bond itself.
4. U.S. Stocks on the Day of GPT-6 Release: Hardware Differentiation, Not a Broad Rally
The full rollout of GPT-6 did not create an "AI broad buy" in the market, but rather led to internal differentiation.
The Philadelphia Semiconductor Index fell 1.15%. The internal performance of storage and semiconductors was split: according to public market data, Micron rose over 4% against the trend, and Advanced Micro Devices rose over 3%; Qualcomm, Arm fell over 2%, TSMC dropped 2.09%, and Western Digital and SK Hynix ADRs weakened.
Micron's relative strength is related to storage supply and demand. Reports indicate that on October 7, an overseas institutional analyst raised Micron's target price from $2,100 to $3,000, with one of the core logics being the demand for high-bandwidth memory (HBM) from AI data centers (this target price only represents the judgment of the relevant institution). One market interpretation suggests that the larger the inference load of models like GPT-6, the more directly the demand for high-bandwidth memory arises, leading to a pricing differentiation between "AI core storage" and "traditional storage" within the storage sector—whether this differentiation can be sustained still needs to be verified by subsequent financial reports and order data.
Large tech stocks had mixed performances: Amazon rose 1.42%, Apple rose 0.91%, Google rose 0.81%, and Microsoft saw a slight increase; Meta fell 2.38%, and Nvidia and Tesla saw slight declines. The differentiation itself is a signal: the release of GPT-6 did not trigger a broad rally, and the market began to distinguish "who truly benefits from inference demand."
5. Gold Falls Below $4,100: Dual Pressure from Holding Costs and the Dollar
Gold was one of the assets that saw significant declines that day.
According to public market data, spot gold closed at about $4,110 per ounce (with different sources reporting between $4,110.68—$4,110.75), down 1.28%, with an intraday low of around $4,066, the lowest since August 5; spot silver closed at about $59.75 per ounce; New York December futures gold fell $46.40 to $4,140.70 per ounce.
The weakness in gold that day may be primarily related to two factors: first, the real interest rate environment—30-year U.S. Treasury yields were above 5.7%, systematically raising the opportunity cost of holding non-interest-bearing assets; when U.S. Treasuries can provide yields above 5.3%, gold's "zero-interest" attribute shifts from background to constraint; second, the strengthening dollar—the dollar index rose above 102.3, suppressing gold prices denominated in dollars. A precious metals analyst stated to the media that the message conveyed by the market is that interest rates may remain elevated for a longer time, providing support for yields and the dollar.
It should be noted that the decline in gold occurred before the results of the 10-year auction were announced, while after the auction, yields fell and gold prices rebounded from their lows—simply attributing the decline to a single event is not accurate; interest rates, the dollar, and positioning factors may have acted together.
6. Crude Oil: Geopolitical Tensions, but Oil Prices Decline
WTI crude oil futures fell 1.30% to $88.28 per barrel, while Brent crude oil fell 0.38% to $100.20 per barrel (according to public market data).
The trend of oil prices does not synchronize with geopolitical news. According to public reports, Iran stated that the Strait of Hormuz is in a "closed state," and the Iranian armed forces have control over it; the conflict between Saudi Arabia and the Houthi forces in Yemen is also ongoing. However, oil prices did not rise as a result, as the hedging power on the supply side may be more critical: G-7 countries have agreed to coordinate the release of about 100 million barrels of crude oil and fuel through the International Energy Agency over the next four months, and on October 7, IEA member countries agreed to accelerate the pace of the announced reserves; according to maritime data agencies, crude oil exports from the Middle East (excluding Iran) have recently even surpassed pre-conflict levels, with some cargo flows rerouted; other reports mention that Saudi Aramco is studying new export channels to cope with short-term disruptions.
The geopolitical risk premium has been partially offset by policy hedges on the supply side, which may be one of the important reasons why oil prices did not rise with the situation in the Middle East that day. However, if supply disruptions continue to escalate, there is a limit to the buffering capacity of reserve releases, and whether this balance can be maintained remains uncertain.
7. Cryptocurrency Synced Correction: Leveraged Longs Under Pressure
Bitcoin briefly fell below $83,000 that day, closing at about $83,100, down over 3%; Ethereum fell nearly 5%, SOL dropped about 3%, HYPE and XRP fell over 4%, and DOGE dropped over 7% (according to public market data).
According to CoinGlass data, the total liquidation amount in the entire market over the past 24 hours was about $700 million, with over 90% being long positions. The correction in crypto assets may be related to multiple factors: rising U.S. Treasury yields and a stronger dollar suppressing the valuation of non-yielding/low-yielding assets, and leveraged longs being passively liquidated during the rapid decline amplified volatility; the morning's geopolitical events that triggered rising oil prices also put pressure on risk appetite.
8. Independent Trend of Chinese Concept Stocks
Against the backdrop of a general decline in U.S. stocks, the Nasdaq Golden Dragon China Index turned positive in the closing hours, with a slight increase (according to public market data, about 0.1% to 0.3%, with slight variations in different data sources); some Chinese concept stocks showed significant gains.
The relatively independent trend of Chinese concept stocks may be related to multiple factors: first, the previous adjustment was substantial, and valuations are at relatively low levels; second, according to a statistical analysis by a major foreign bank on nearly 2,800 global funds, the average allocation of global active long funds to Chinese stocks has risen from "underweight" to "benchmark neutral" since June, ending a four-year period of underweight status, with related funds managing about $562 billion in Chinese stock assets (this view represents only the judgment of the relevant institution). Whether the historical changes in capital behavior can continue remains uncertain, and past performance does not guarantee future results.
### 9. What to Watch Next
First, the results of the 30-year auction. This is a direct test of whether "allocation extends to the ultra-long end": if the 10-year is strong and the 30-year is also strong, long-end interest rate pressure may be close to a phase release; if the 10-year is strong and the 30-year is weak, it indicates that the ultra-long end remains a weak link, and the suppressive factors on high-valuation assets and gold have not been resolved.
Second, whether the 10-year U.S. Treasury yield can return to and stabilize below 5.3%. If the yield continues to operate above 5.3%, the valuation anchor for high-valuation assets will continue to be under pressure; if the buying pressure from allocation-type buyers is sustainable, the top of long-end rates may be closer than currently implied by pricing—this judgment carries uncertainty.
Third, the industrial transmission after the release of GPT-6. The internal differentiation within the storage sector (some AI-related storage assets strengthening, while traditional storage and some semiconductors weakening) is a preliminary signal. If the pricing difference between "AI core storage" and "traditional storage" continues to widen, the pricing logic of the AI industry chain may shift from "buy AI" to "identify the segments truly benefiting from inference demand within the AI chain"—ultimately, this still requires verification through orders and financial reports.
Fourth, the marginal changes in the probability of a rate hike in December. The current market pricing indicates a probability of about 70% to 80% for a cumulative rate hike of at least 25 basis points in December (according to different points of CME FedWatch). If subsequent inflation data shows persistence, this probability may further increase, and the "pause" in October may just be a matter of timing; conversely, any signal of cooling inflation could simultaneously improve the situation for growth stocks and long bonds.
Final Thoughts
Reading October 7 as "AI narrative setbacks" or "market panic" is incomplete. What actually happened is more like: the Federal Reserve's minutes incorporated AI into the inflation framework, putting upward pressure on long-end yields; on the same day, a demand-surprising 10-year auction pushed some yields back down. The full rollout of GPT-6 did not lead to a broad rally but rather a reordering of "benefiting segments"; the corrections in gold and crypto are more a result of holding costs and the dollar environment. Beneath all this, the 30-year yield stands above 5.7% and has not yet undergone demand testing at the same level—it may be the true touchstone for the next few trading days.
Data Sources
Official release from OpenAI
Public market data (U.S. stocks, U.S. Treasuries, gold, crude oil, crypto assets, etc.)
U.S. Treasury auction results
Federal Reserve meeting minutes, CME FedWatch
Reuters, CNBC, FXStreet, CoinGlass
G-7/IEA statements
Research reports and public reports from foreign institutions
Disclaimer: The content of this article is for general information and market commentary purposes only, compiled based on publicly available information as of the time mentioned in the text. Relevant market data, expectations, and probabilities may change with market conditions. The views and investment strategies quoted from third-party institutions, analysts, or other individuals represent only the views of the relevant third parties at a specific time and do not represent the views or recommendations of BIT. This article does not constitute investment advice, investment research, an offer, solicitation, or recommendation of any securities, investment products, or trading strategies, nor should it be the basis for any investment decision. Financial markets carry risks, and securities prices and market performance may fluctuate; past performance and historical market trends do not represent or guarantee future results. Investors should independently assess relevant risks based on their own circumstances and seek professional advice when necessary.
 Risk warning