Bank of America: DRAM remains strong, NAND has quietly weakened, and storage is differentiating
 Core Viewpoint

 Bank of America believes that the logic behind the price increase of DRAM has not yet been broken, while the spot market for NAND has clearly loosened and will become the first variety that needs to be repriced in this round of storage upcycle. The valuation gap and performance elasticity of the two will depend on whether the contract price negotiations for the first quarter of 2027 can be successfully concluded as scheduled.
Author: Xu Chao, Wall Street Journal
The market for storage chips is shifting from "uniform increase" to "differentiation." Bank of America believes that the logic behind DRAM price increases has not been broken, while the NAND spot market has clearly loosened, making it the first category that needs to be repriced in this round of storage upcycle.
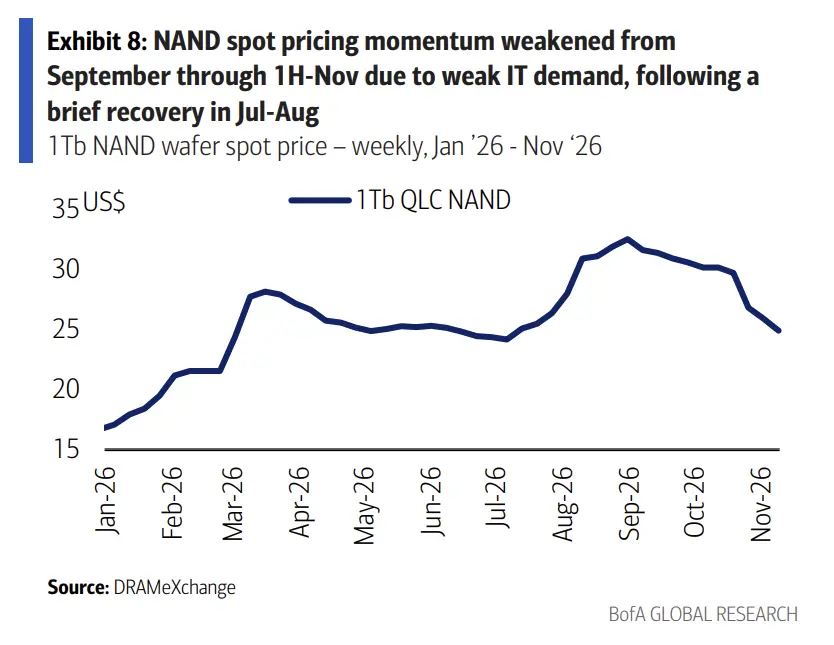
Bank of America's report on November 13 shows that NAND spot prices have dropped significantly, with 512Gb wafers down over 10%, 1Tb down nearly in the single digits, while 16Gb DDR5 spot prices remain flat. Since mid to late October, NAND spot prices have cumulatively corrected about 20%.
Based on this, Bank of America maintains a cautious assumption for the average selling price of NAND in the first quarter of 2027: IT NAND prices are expected to decline by 5% to 10% quarter-on-quarter, while enterprise-level applications are basically flat or slightly up, resulting in an overall low single-digit decline. This judgment contrasts sharply with the market's expectation that NAND prices will rise by more than 10%. Meanwhile, Bank of America still assumes that DRAM price increases will continue into the fourth quarter of 2026 (up 8% quarter-on-quarter) and the first quarter of 2027 (up 5%).
Bank of America stated that after communicating with investors this week, the sentiment for storage stocks has improved compared to last week, and companies with a high weighting in DRAM are considered to have limited downside. Most DRAM targets currently correspond to a price-to-earnings ratio of only 3 to 5 times for earnings in 2026 to 2027, which is significantly lower than their AI semiconductor peers.
Three Signals of Weakness in NAND Spot Prices
Bank of America attributes its concerns about NAND to three points: spot prices have corrected about 20% since mid to late October; orders from PC and smartphone OEMs as well as China's hyperscale cloud vendors have weakened; and negotiations for contract prices in the first quarter of 2027 may be delayed, with no rush orders appearing in the market.
The differentiation in spot data is quite intuitive. According to DRAMeXchange, the spot price for 512Gb wafers is reported at $14.3, down 12% week-on-week and down 32% quarter-on-quarter, but up 121% year-on-year; 1Tb is reported at $24.9, down 4% week-on-week, down 19% quarter-on-quarter, and up 194% year-on-year. In contrast, 16Gb DDR5 is reported at $60.2, flat week-on-week and up 150% year-on-year.
Original manufacturers still emphasize strong demand for enterprise-level SSDs, which can somewhat offset the weakness in IT NAND. However, Bank of America reminds that old production lines account for 20% to 30% of global wafer capacity and are not suitable for producing high-end NAND and eSSD, still needing to be continuously used for IT NAND, which constitutes structural pressure on prices. The price per bit for high-capacity NAND (over 2Tb) and eSSD (over 30TB) has seen a slight adjustment downwards, but Bank of America believes this is more of a proactive promotion by manufacturers to promote the new generation of QLC—most eSSD NAND prices still show a slight upward trend.
Divergence: Contract Prices Remain High, but Negotiations May Be Delayed
Currently, the trends of NAND contract prices and spot prices are diverging.
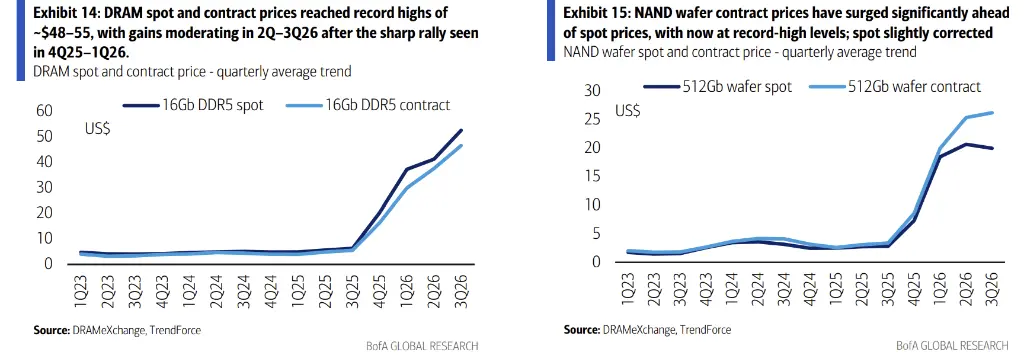
According to TrendForce, the contract price for 1Tb TLC wafers in October remained basically flat month-on-month, continuing the sideways pattern from the second to third quarters; the contract price for 512Gb is about $27, close to historical highs, approximately ten times the low of $2.5 in February 2025.
Bank of America's concern lies in the timing: if downstream orders do not come in urgently, the contract price negotiations for the first quarter of 2027 may be postponed, and manufacturers' bargaining power in the new round of negotiations will be weakened. This judgment directly corresponds to its divergence from market expectations—sellers generally assume that NAND prices will still rise by about 10%, while Bank of America forecasts a low single-digit decline.

On the DRAM side, the picture is different. According to TrendForce, the contract price for 16Gb DDR5 increased by another 5% month-on-month in October, with a year-on-year increase of over 500%; the contract price for 64GB modules of DDR5 and DDR4 on the server side increased by about 15% month-on-month in October, with module prices exceeding $1,000, reaching $1,600 and $1,500 respectively. Based on this, Bank of America maintains its assumption of an 8% quarter-on-quarter increase for DRAM in the fourth quarter of 2026 and a 5% increase in the first quarter of 2027.
Samsung: Optimistic About HBM, But Not Aggressive
Bank of America held an investor communication meeting with Samsung Electronics on November 12, and the three key points obtained were: demand for AI data center chips in the U.S. is strong, and despite concerns, no order reductions have been seen; the market position of HBM has significantly improved compared to a year ago; and the long-term contract prices (LTA) for DRAM business are strongly upward, with high prices and high margins sustainable over the long term.
However, the management's statements are not aggressive, which is also one of the focal points for investors. Samsung's target for HBM market share is around 30% to 40%, rather than over 50%; even by the end of 2027, the profitability of LPDDR5 is still better than that of HBM, so aggressive expansion of HBM capacity is unlikely to avoid encroaching on traditional DRAM market share. In terms of technology, HBM4e will share the same 1c node and 4nm logic chip with HBM4. Bank of America also mentioned that the contract price increase in 2027 is unlikely to reach the levels expected by TrendForce, as prices have already risen in advance in 2026.
It is worth noting that Samsung's guidance on IT NAND is not as optimistic as that for eSSD, which aligns with Bank of America's price judgment.
Sentiment Warms Up, Valuation Remains a Major Support
Storage stocks rebounded this week, with cumulative gains for the year generally exceeding 100%, and SanDisk and Kioxia have returned over 250% since the beginning of the year. Bank of America stated that investors communicated this week generally mentioned limited downside, citing reasons such as the resilience of AIDC chip orders after the U.S. midterm elections, DRAM prices still rising (in contrast to NAND), and low valuation multiples.
The valuation table shows that SK Hynix corresponds to a price-to-earnings ratio of 3.6 times for 2026, Samsung at 4.7 times, Micron at 10.7 times, and Nanya at 5.1 times; in the NAND camp, Sandisk corresponds to a price-to-earnings ratio of 4.3 times for 2027, Western Digital at 13.2 times, SIMO at 16.4 times, and Phison at 7.7 times. Bank of America believes that compared to AI semiconductor peers, the pricing in the storage sector still appears moderate.
Bank of America concludes that the supply and demand dynamics and price trends for DRAM are still supported by AI data centers and HBM squeezing capacity, while the pricing power for NAND is shifting towards buyers. The valuation differences and performance elasticity between the two will depend on whether the contract price negotiations for the first quarter of 2027 can be realized as scheduled.
 Risk warning
 Risk warning
Popular articles