








HIP-4: Hyperliquid's prediction market, why can't it catch up to Polymarket?
 Core Viewpoint

 Building blocks are well assembled, but the market has not arrived yet.
Author: Mario Chow, IOSG
Data as of October 5, 2026. Prices, staking, order books, and transactions come from the Hyperliquid API, individual market transaction volumes are from Liquidiction's published node transaction archives, and transaction volumes from Kalshi and Polymarket come from The Block. The charts are the same as the English version, see above.
Summary
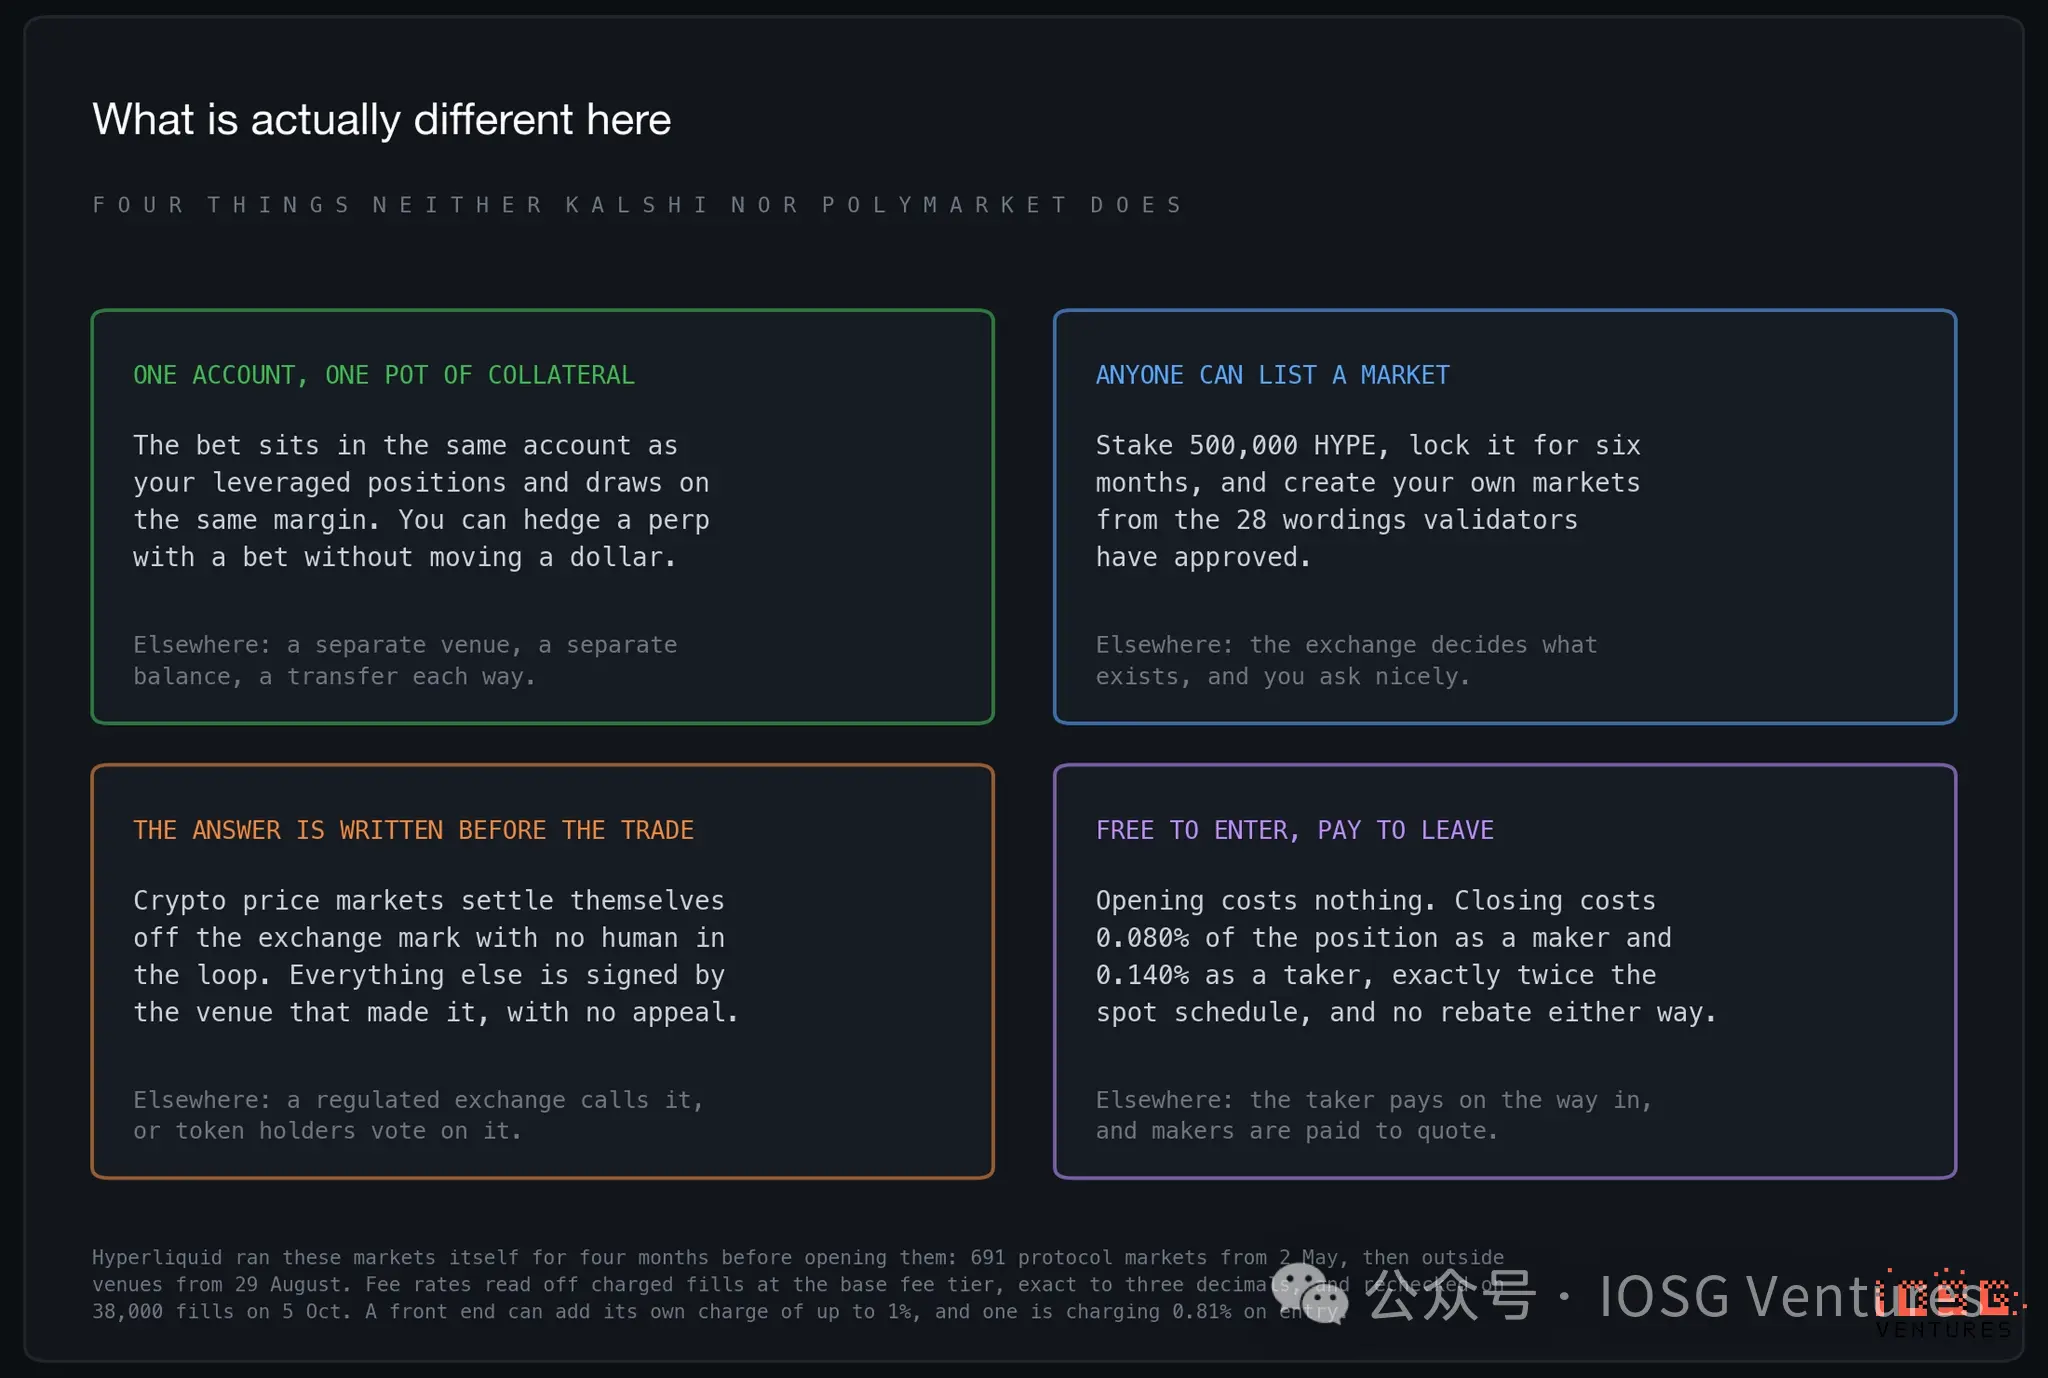
The thing most similar to HIP-4 is not Polymarket, but an options order hanging next to your perpetual position. Yes shares and your leveraged position are in the same account, using the same margin, and transacting on the same matching engine, so a bet and the position it needs to hedge are always on the same interface. The other three points are also different from others: anyone can open a market by staking 500,000 HYPE; the settlement conditions are written in the template before the first transaction; entry is free, and exiting incurs about one-thousandth, which is exactly the opposite of the fee structures of Kalshi and Polymarket.
For the first four months, only Hyperliquid itself was running. When it launched on May 2, 2026, all markets were directly operated by the protocol, totaling 691, and it wasn't until August 29 that it opened to external venues. Since then, three have staked, and there has been no fourth.
Whether you can see it depends on where you are. The prediction market has a separate page at app.hyperliquid.xyz/outcomes, and the frontend decides whether to include it in the trading list alongside perpetuals and spot based on the region. Accessing from a Korean network, this column can be seen in the market list; using the network we tested, it was nowhere to be found in the list or menu, but the page itself could still open and trade. Hyperliquid restricts frontend access in several countries; an entry you can't see here might be visible to someone two time zones away.
From May to now, HIP-4 has accumulated a transaction volume of $317 million, while Kalshi can complete that much in less than four hours. In September, for every $1,000 traded on Kalshi and Polymarket, HIP-4 only traded about 70 cents.
Design is its best aspect, but the issue lies in scale. Over a quarter of HIP-4's historical transactions came from the already concluded FIFA World Cup. The daily Bitcoin market that supported the first four months has dropped 93% from its peak in May. The new venues brought September back to $51 million, flat with July, while the one contributing the most had to pay traders about 0.6 cents for every dollar traded. October started even slower, averaging about $1.25 million per day. The entire market's transaction fees amount to about $1,300 daily, which is less than half of what a venue earns from staking without moving it.
1. Product Design: Different from Kalshi and Polymarket
Based on the basic fee rate tier, the rates derived from actual transaction fees are as follows:
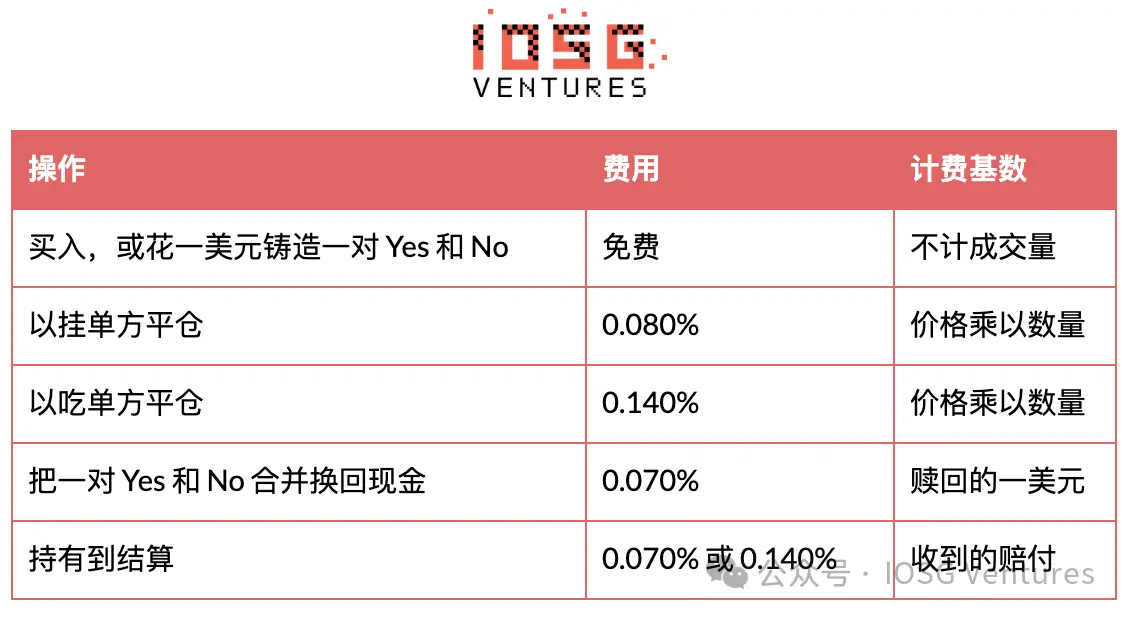
This is exactly double the spot fee rate: the basic spot tier charges 0.070% for market orders and 0.040% for limit orders. One side doubles while the other goes to zero, making the cost of a round trip the same as spot, just all collected upon exit. Common discounts are simply multiplicative: a 4% referral discount reduces 0.140% to 0.1344%, and adding a 10% staking discount gives 0.12096%, with every transaction we verified being accurate to the cent. Limit orders do not have rebates, which is the only disadvantage for market makers here compared to other sectors on the exchange.
Currently, no venue has adjusted its fee coefficient above the default value, so the venue's share comes from the protocol fee, not an additional charge. The only possible fees encountered upon entry come from the frontend application: according to spot rules, the builder fee cap is 1%, and one application charges 0.81% upon entry, which is nearly six times the protocol exit fee.
Settlement deserves a closer look because the venue's risk lies here. Polymarket relies on UMA token holders voting to adjudicate; earlier this year, a $375 million Microstrategy market caused quite a stir. Kalshi, as a regulated exchange, adjudicates itself, with oversight from regulatory bodies. HIP-4 separates this matter: the crypto price market reads the exchange's marked price at the agreed minute for automatic settlement; all other markets are determined by the market creator's signature, with no dispute period and no one else able to sign for them.
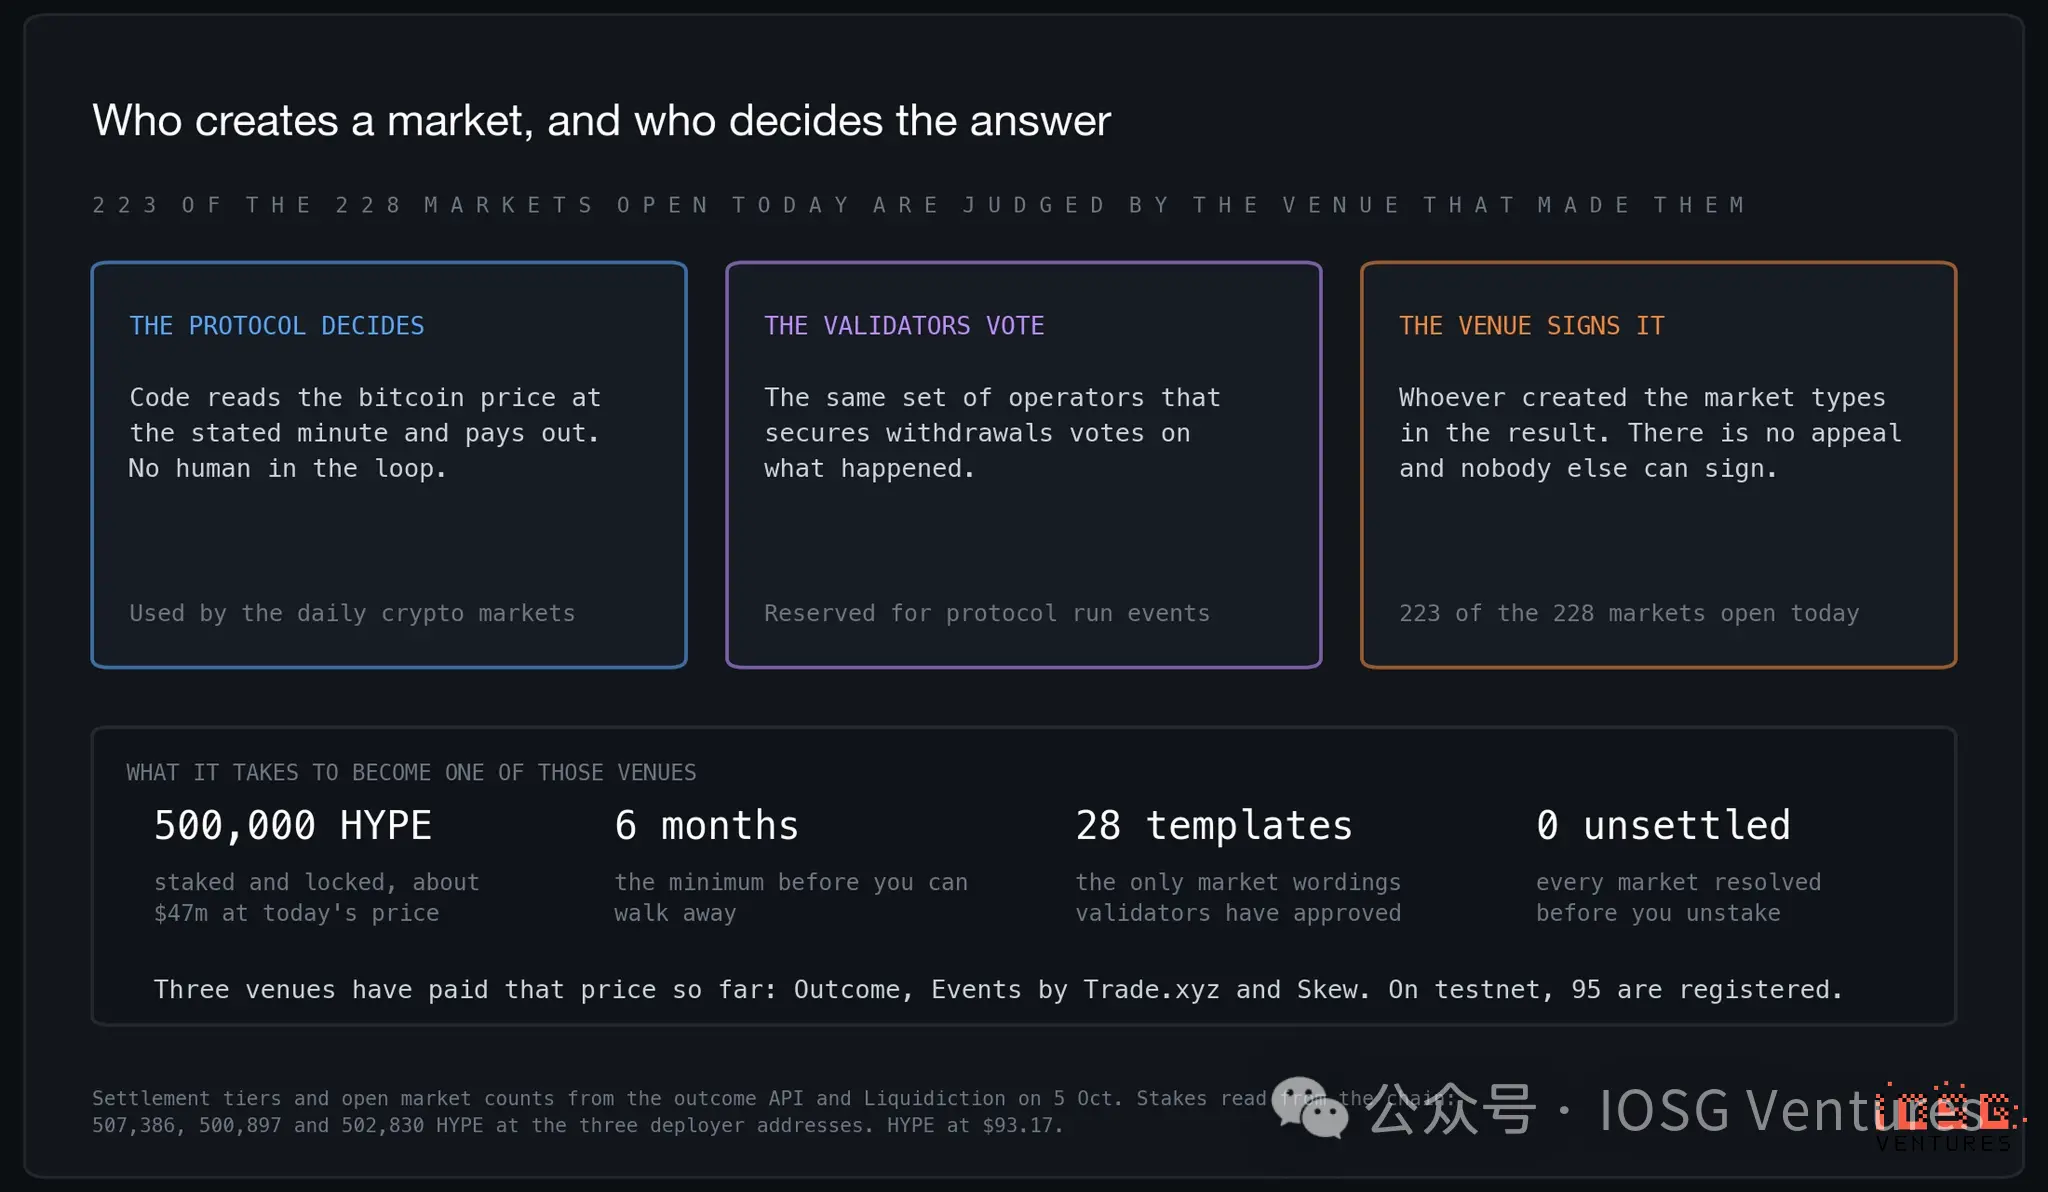
Among the 228 markets currently open, 223 belong to the latter type. Constraints rely on money and time, not procedures. As long as the venue has unsettled markets, the stake remains locked; it cannot be withdrawn within six months; it can only use wording pre-approved by validators. These wordings are deliberately long and meticulous, such as the template for "company listing," which lists an entire page of conditions for what constitutes a listing. Having rules written before trading is better than arguing afterward. Handing the pen to a named party without leaving a channel for appeal is indeed less preferable than having a set procedure, provided that the procedure itself does not malfunction.
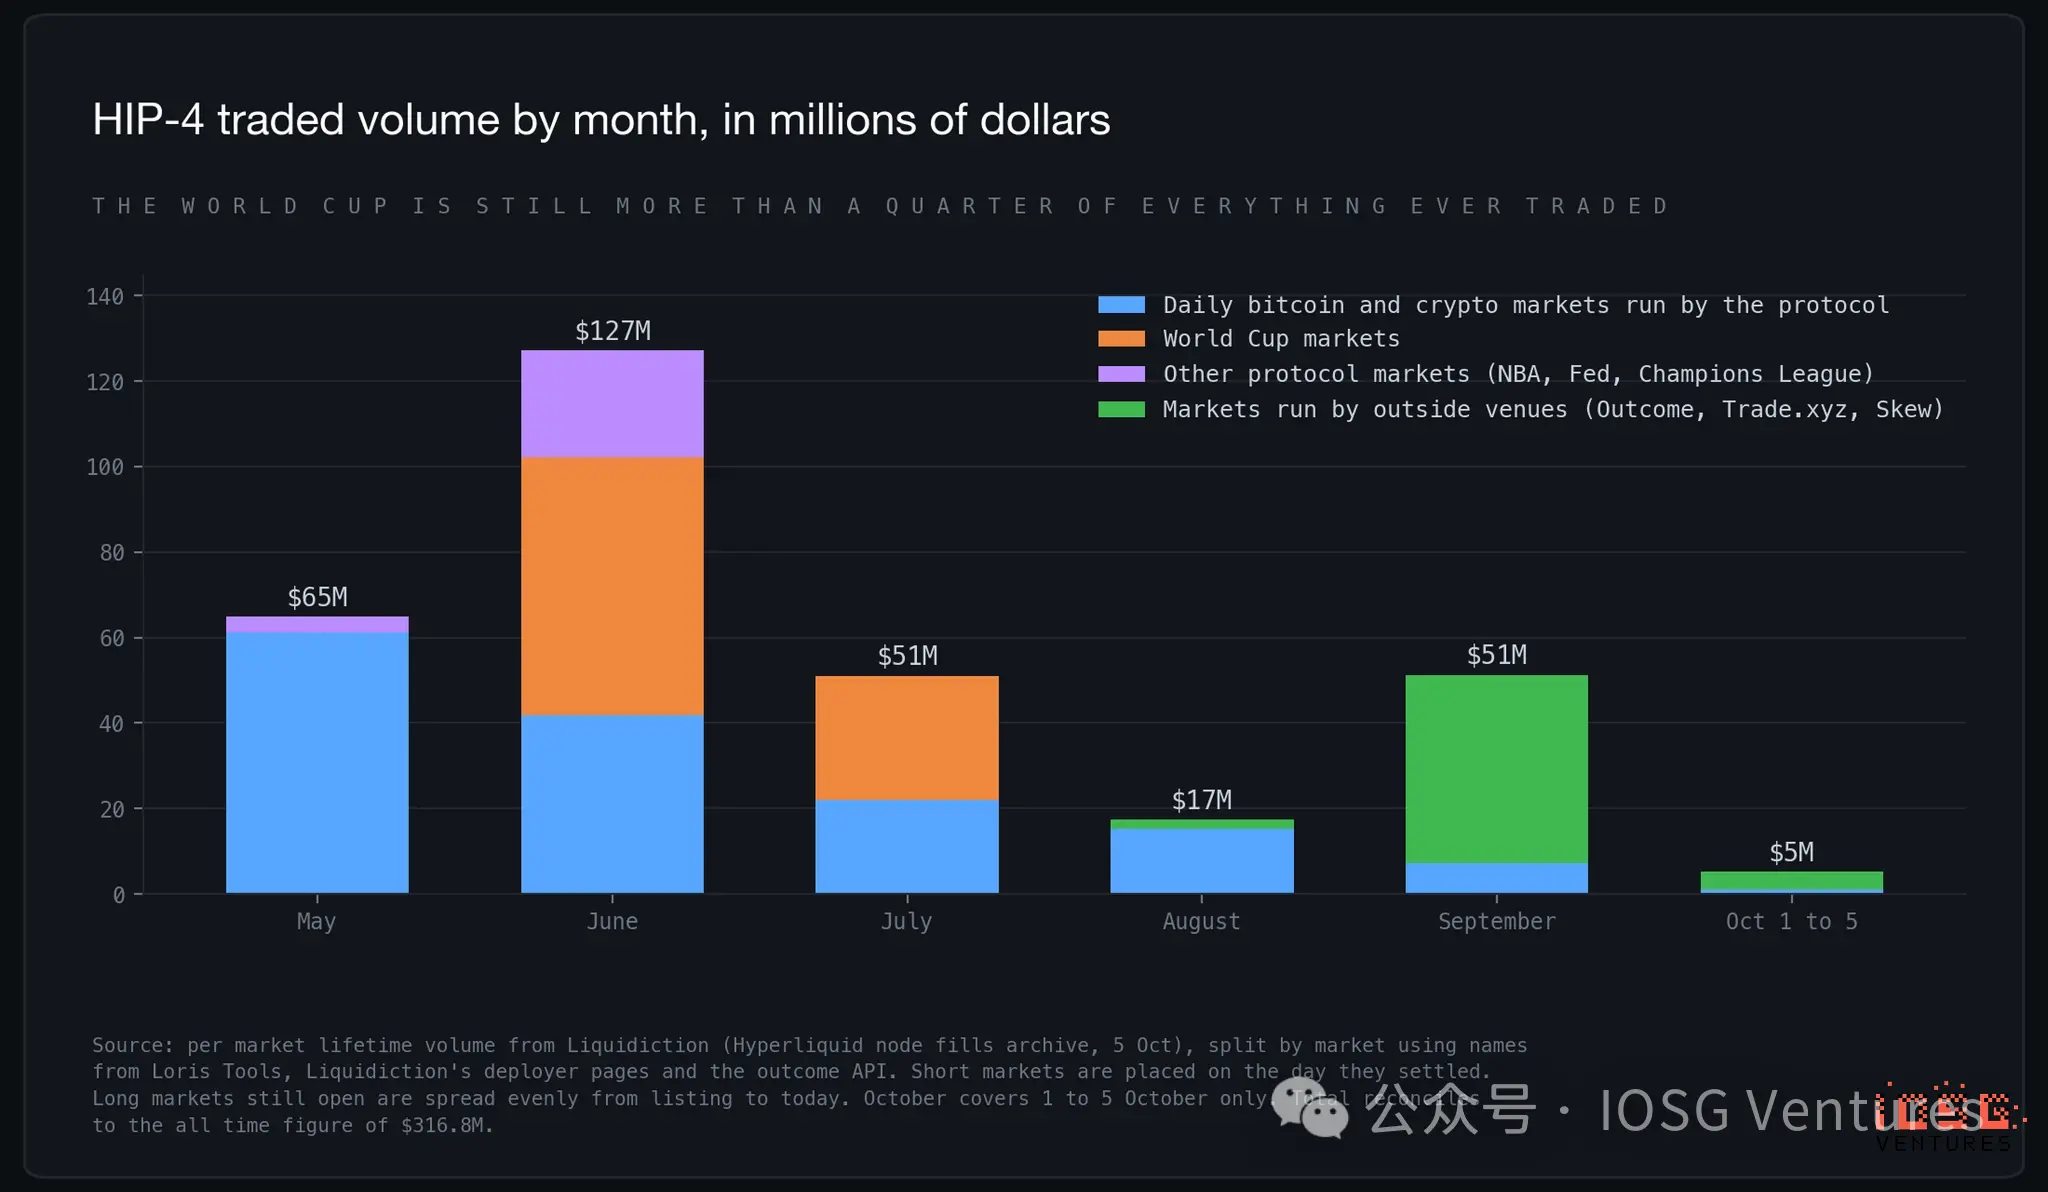
June was a peak, due to the World Cup. The football market alone had a transaction volume of $89.5 million, accounting for 28% of HIP-4's cumulative transactions. Once the World Cup ended, it dropped more than 80% over the next two months. September returned to $51 million, with the recovery entirely coming from external venues; the first five days of October saw $5 million in transactions.
Beneath these events, the protocol has been running the same market daily since May: whether Bitcoin will be above a certain price at six o'clock tomorrow morning. This is probably the product most characteristic of Hyperliquid, which only bottomed out after four months of decline.
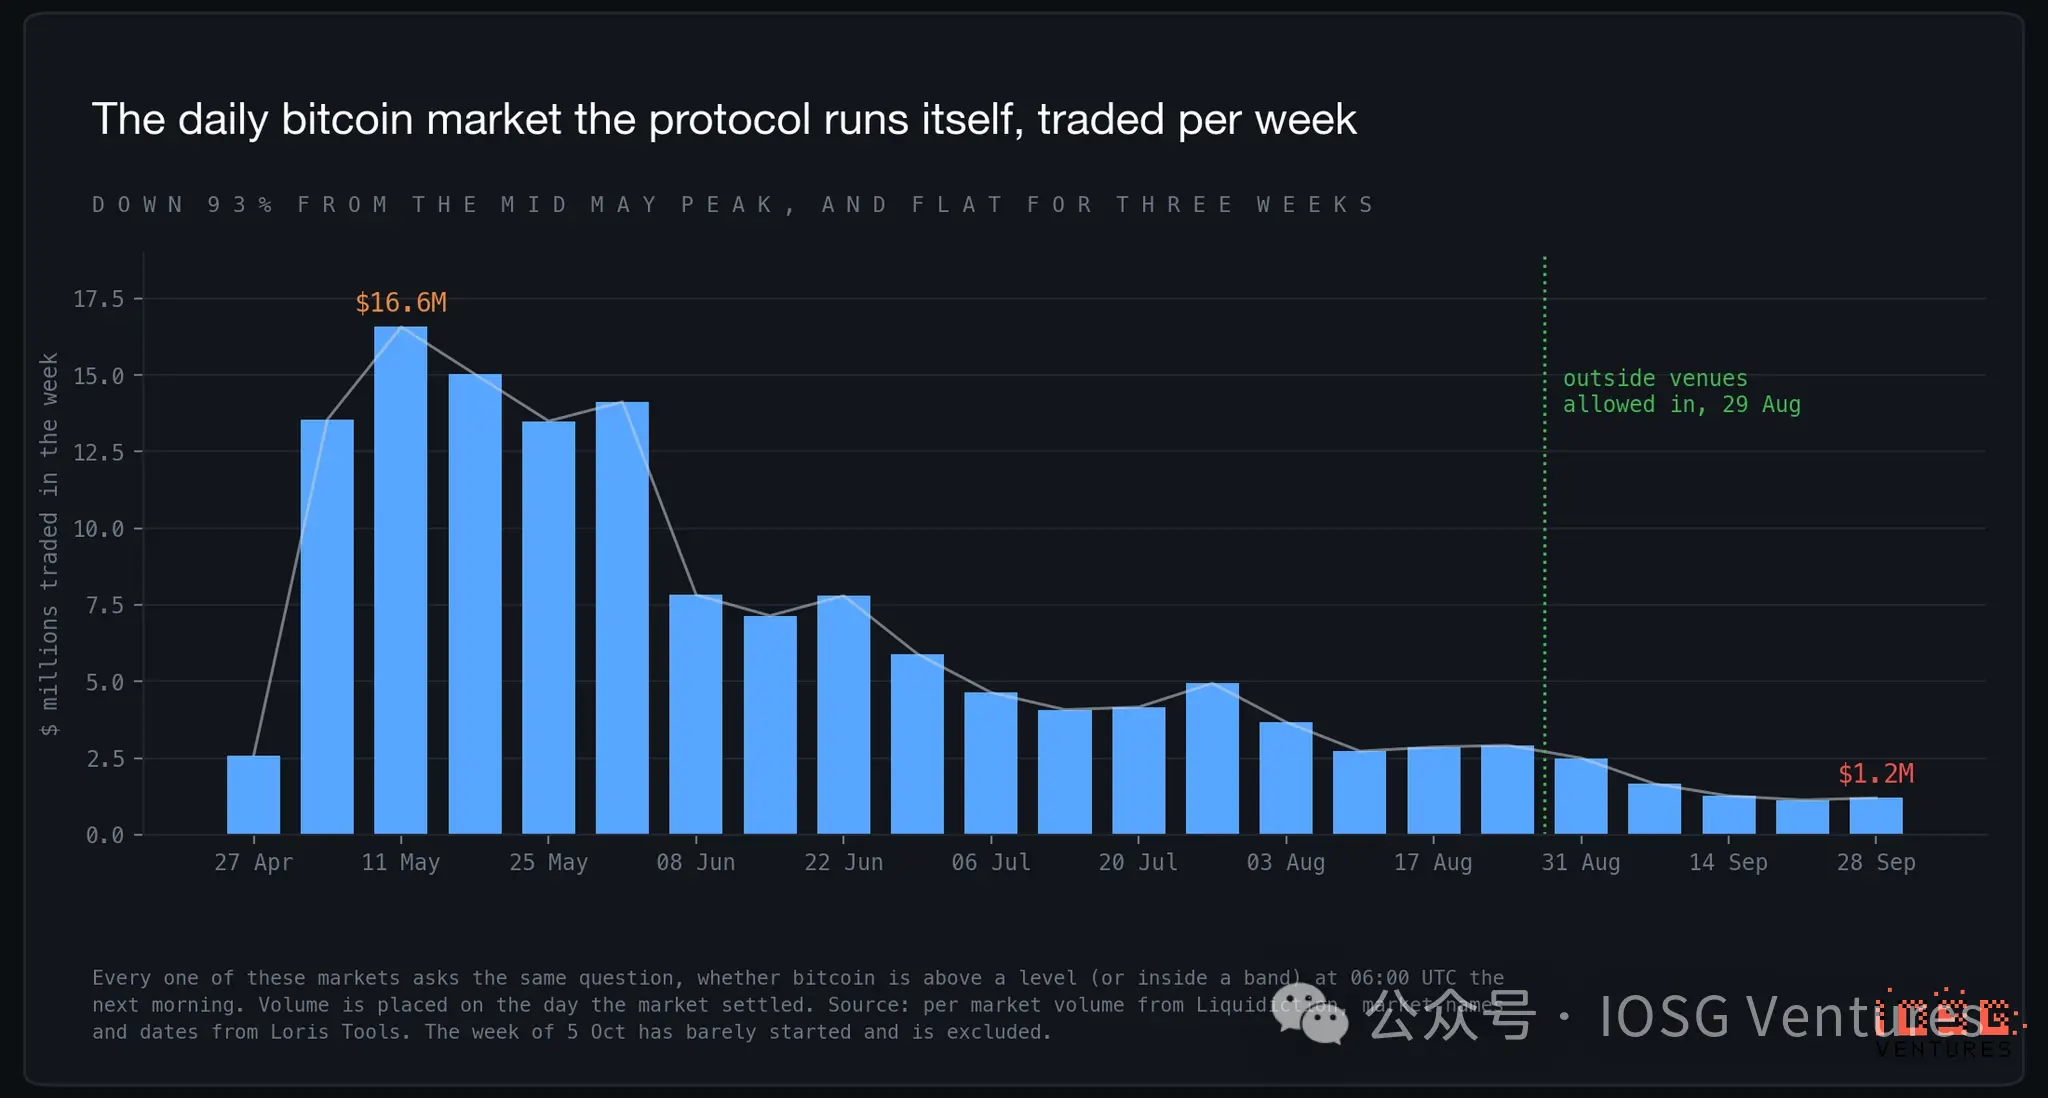
In the week of May 11, the transaction volume was $16.6 million, while in the week of September 28, it was only $1.2 million, with the previous two weeks being similar. Asking the same question every day, the audience has dwindled to almost none before it stopped. No matter what HIP-4 becomes in the future, it will not be like this.
2. Five Weeks of Open Deployment: Subsidized Transactions and Repeated Markets
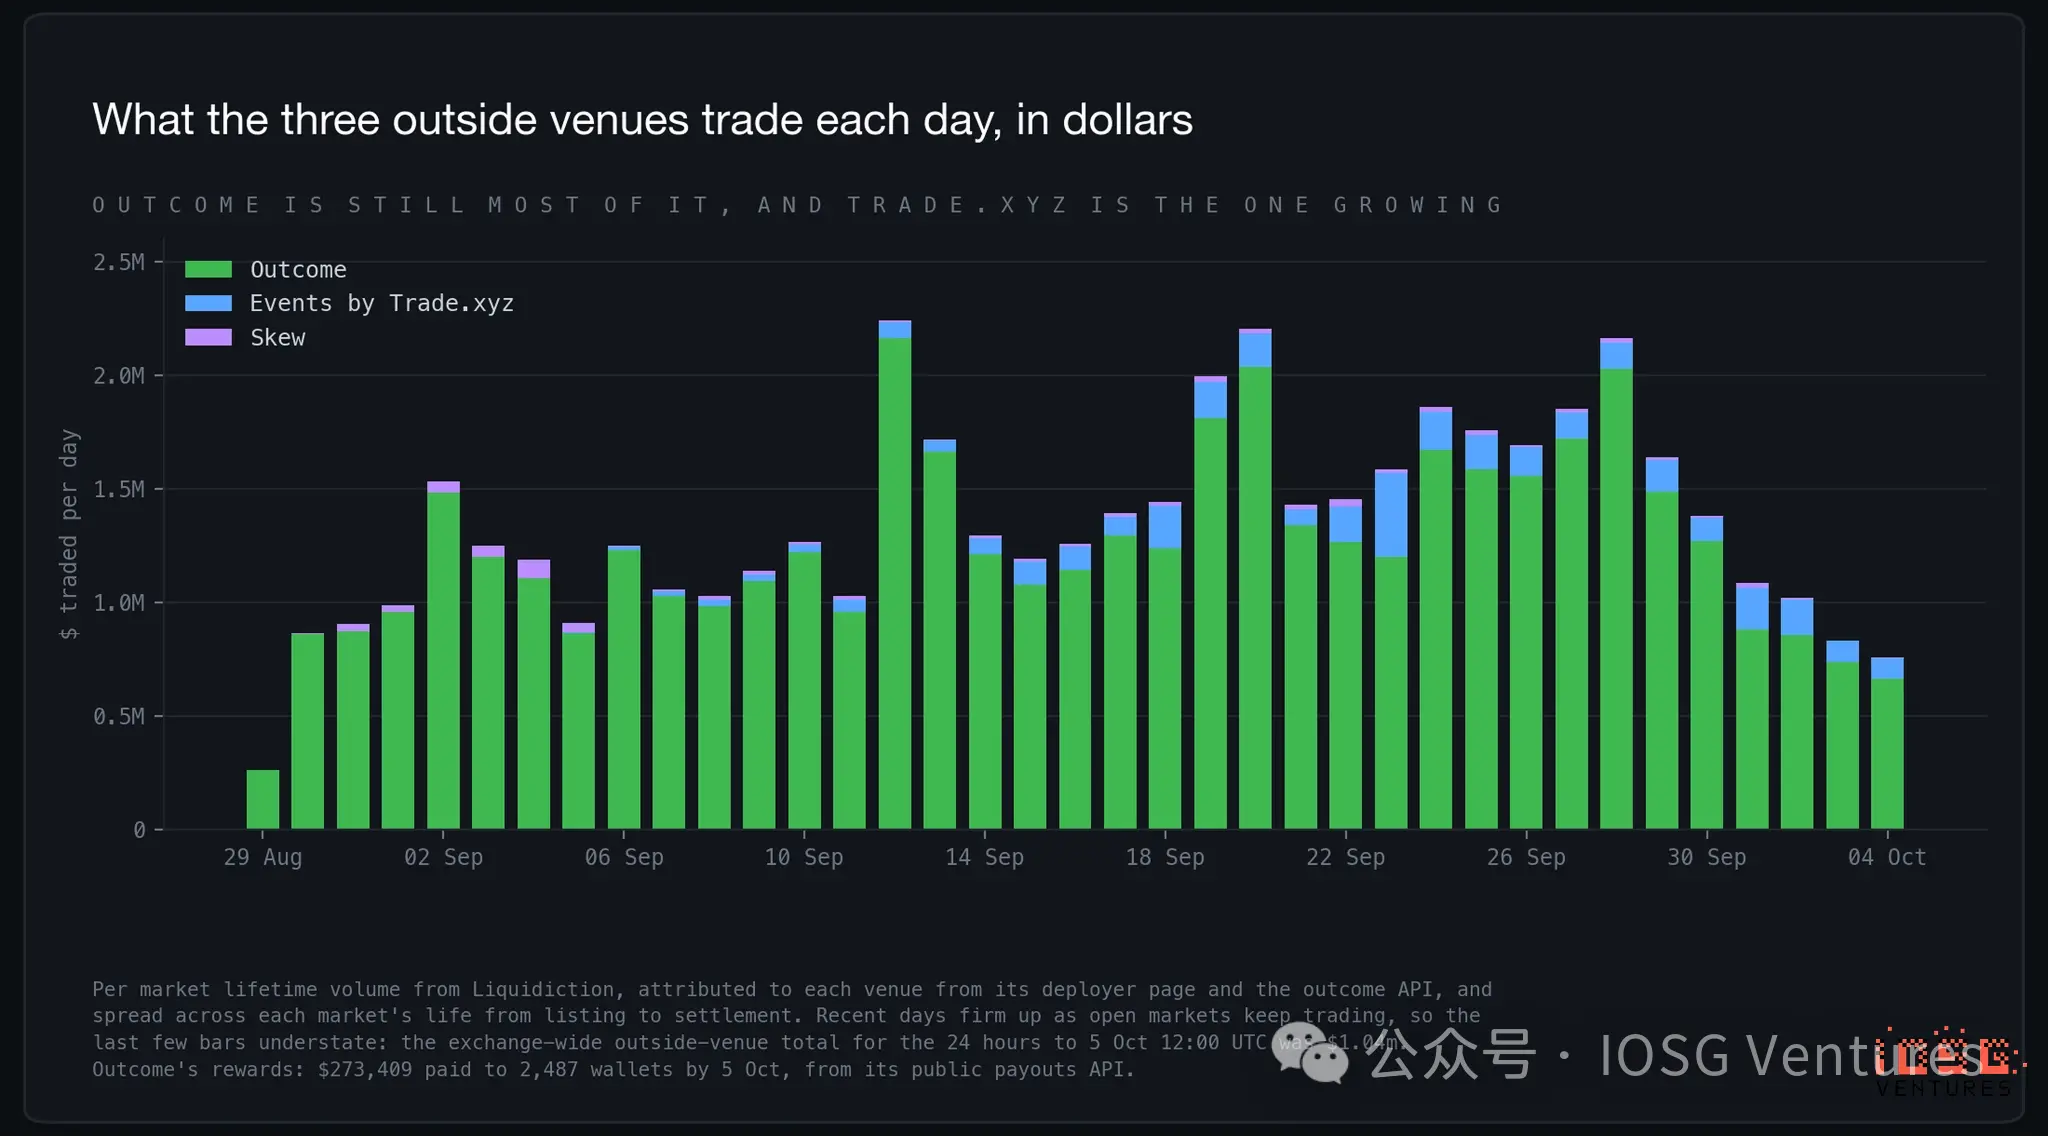 Outcome was the first to launch on August 29. Skew registered a market the next day, but has seen almost no transactions since. Events under Trade.xyz registered on September 5 and opened to the public on the 10th. Looking at the entire HIP-4, in the most recent day, Outcome accounted for 68%, Trade.xyz for 21%, and the protocol's self-operated markets for 10%, with the rest being Skew. Just counting external venues, since August 29, Outcome has accounted for 92%, while Trade.xyz has risen from zero to nearly a quarter in the most recent day. The markets it chose are the most opinionated: binary contracts betting on its own stocks and commodity perpetual prices, NFL, and the only questions in the exchange about whether Anthropic and OpenAI can go public before the deadline.
These transaction volumes should be viewed with a discount. Outcome has a $1 million reward program that distributes money to market makers and traders daily based on the market, but only rewards orders that carry its own application code. As of October 5, it has distributed $273,409 to 2,487 wallets, averaging about $7,400 daily, which is about 0.6% of Outcome's total transaction volume, equivalent to four times the round-trip trading cost. A quarter of the budget has already been spent, and the daily distribution has not slowed down. External venues saw daily transactions of $1 million to $2 million in September, with weekends being the busiest; by October, it fell back to about $1 million daily, while rewards continue to be distributed.
The open listing has also seen the first batch of repeated markets. Both Outcome and Trade.xyz listed markets for the Federal Reserve's October interest rate decision, with Outcome seeing $354,000 in transactions over the past seven days, while Trade.xyz only saw $90. Both also listed a question about Anthropic's market capitalization on its first day, with little transaction activity on either side. Anyone can list a question, which means both can list the same question, and their order books will not merge. The transaction flow has shifted to the one providing the subsidies.
The trading content is leaning towards sports. Over the past 30 days, football, American football, and esports accounted for 45% of the transaction volume, crypto price questions accounted for 42%, stocks and commodities accounted for 7%, and the Federal Reserve accounted for 6%. The positions are more skewed: two-thirds of the at-risk funds are bet on sports, mostly on long-term bets like the Premier League, UEFA Champions League, and NFL championships, with crypto prices only accounting for 17%.
The optional templates are increasing faster than the venues. Validators have approved 28 templates, up from 18 in mid-September, adding templates for point spreads and totals, the Ballon d'Or, a duel between two AI models on the leaderboard, and company listing market capitalization on the first day. The next network upgrade will double the limit for each venue, allowing up to 200 markets online at the same time, with 1,000 new openings daily. A total of 95 deployers have registered on the test network, while the mainnet still has three.
3. Source of Orders: 70% of Traffic via Outcome
Frontend applications wanting to place orders on your behalf require you to authorize a separate signing key, which will be named after the application. Therefore, wallets registered on outcome.xyz will always carry a label like Outcome-9d3c74de, which anyone can publicly check. The exchange's own mobile login will also show this as Mobile QR; the desktop version signs every step with your own key, leaving no label. We only looked at Outcome because it accounts for about 90% of external venue transactions, and only its answers carry weight.
About 70% of the transactions come from wallets registered on outcome.xyz, about one-fifth comes from wallets with no tags at all, and one-tenth comes from scripts and third-party tools that have named their own keys. The larger the scale, the higher the proportion of Outcome: it accounts for three-quarters of the amount in the largest 20 wallets, while the remaining wallets account for about half. This is precisely the result of the reward program: it only rewards orders routed through Outcome's code, and the market makers receiving the rewards happen to be the largest batch of wallets.
This method has its limitations. A tag only indicates that the wallet has registered through a certain application; it does not indicate that a specific transaction was routed by it. The one-fifth without tags cannot be considered users of the exchange's official page: most of them are simultaneously quoting on many order books and are scripts signed with their own keys. The sample was drawn from 121 wallets from the recent transactions of the 60 most active order books, weighted by transaction amounts within 48 hours, naturally biased towards market makers. The transaction fees also do not answer this question. Less than 1% of the amount in the sample paid builder fees, totaling nine dollars over two days, while Outcome's own code charges no fees; free routing applications and those without applications look exactly the same.
4. **Comparison with Kalshi and Polymarket: ** The gap is about 1,400 times and is still widening
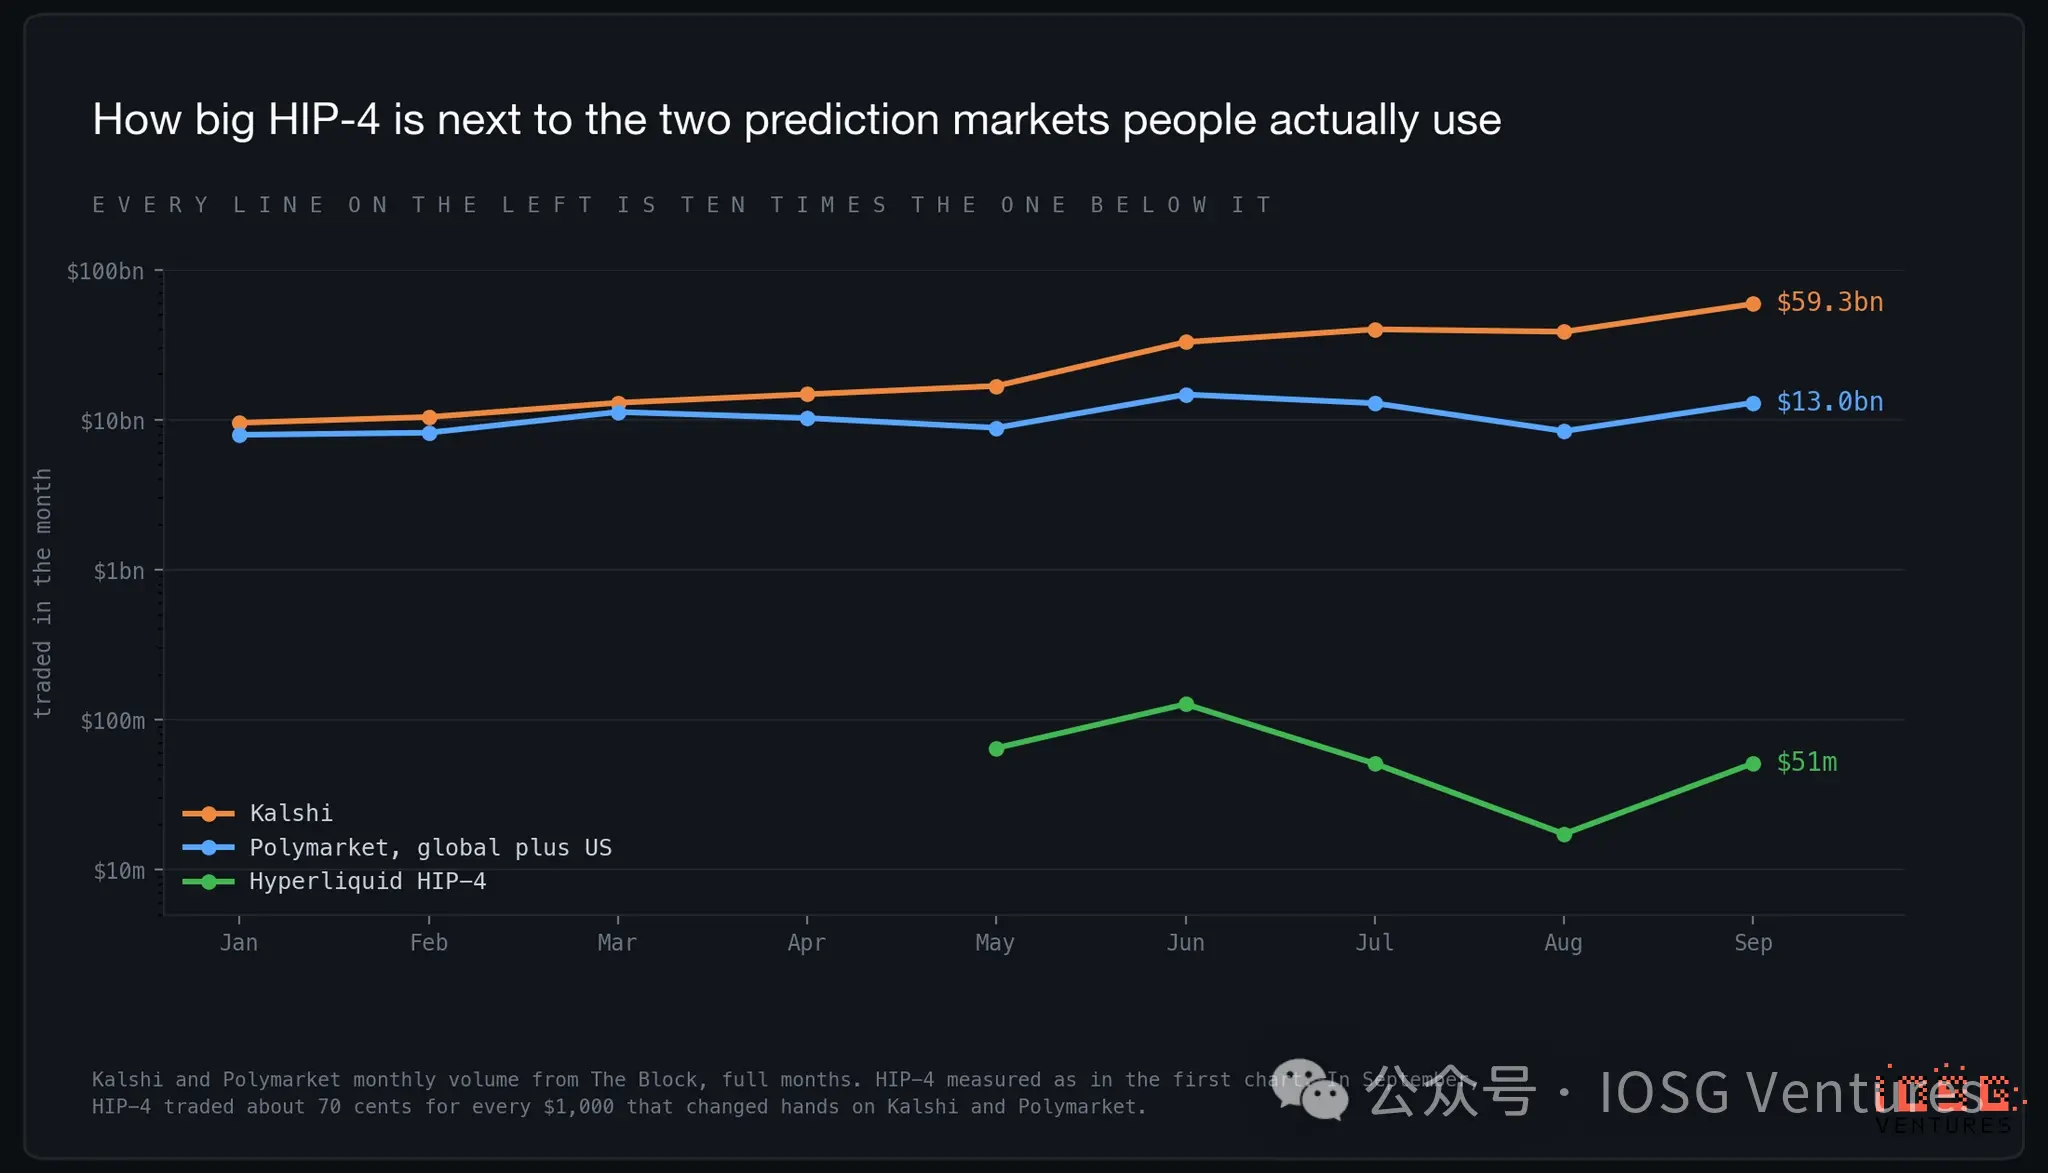
The gap is about 1,400 times, and in terms of dollars, it is still widening, even though HIP-4 itself is also growing. Kalshi had a transaction volume of 59.3 billion dollars in September, an increase of 20.6 billion from August. Polymarket, including its U.S. operations, had a transaction volume of 13 billion dollars, with the majority now in U.S. applications. HIP-4 is at 51 million dollars.
 The advantage of established platforms does not lie in market design; they win in two key areas that truly drive transaction volume. One is the events that everyone cares about, thousands of them, which can be listed within hours of news breaking; the second is distribution channels: applications, brands, sports audiences, and Kalshi also has a compliant shell that U.S. brokers can directly access. HIP-4 has 28 templates, three venues, and a group of users who are already engaged in perpetual trading.
Established platforms are also beginning to move towards Hyperliquid. At the beginning of September, Polymarket launched perpetual contracts for users outside the U.S., covering 67 markets in crypto, stocks, indices, and commodities, with leverage up to 20 times. Combining betting and leveraged positions under the same roof was originally unique to HIP-4. Now this has become a functional competition, and Polymarket entered the arena holding events.
5. **Economic Account: ** Total market fees are less than half of a single staking yield
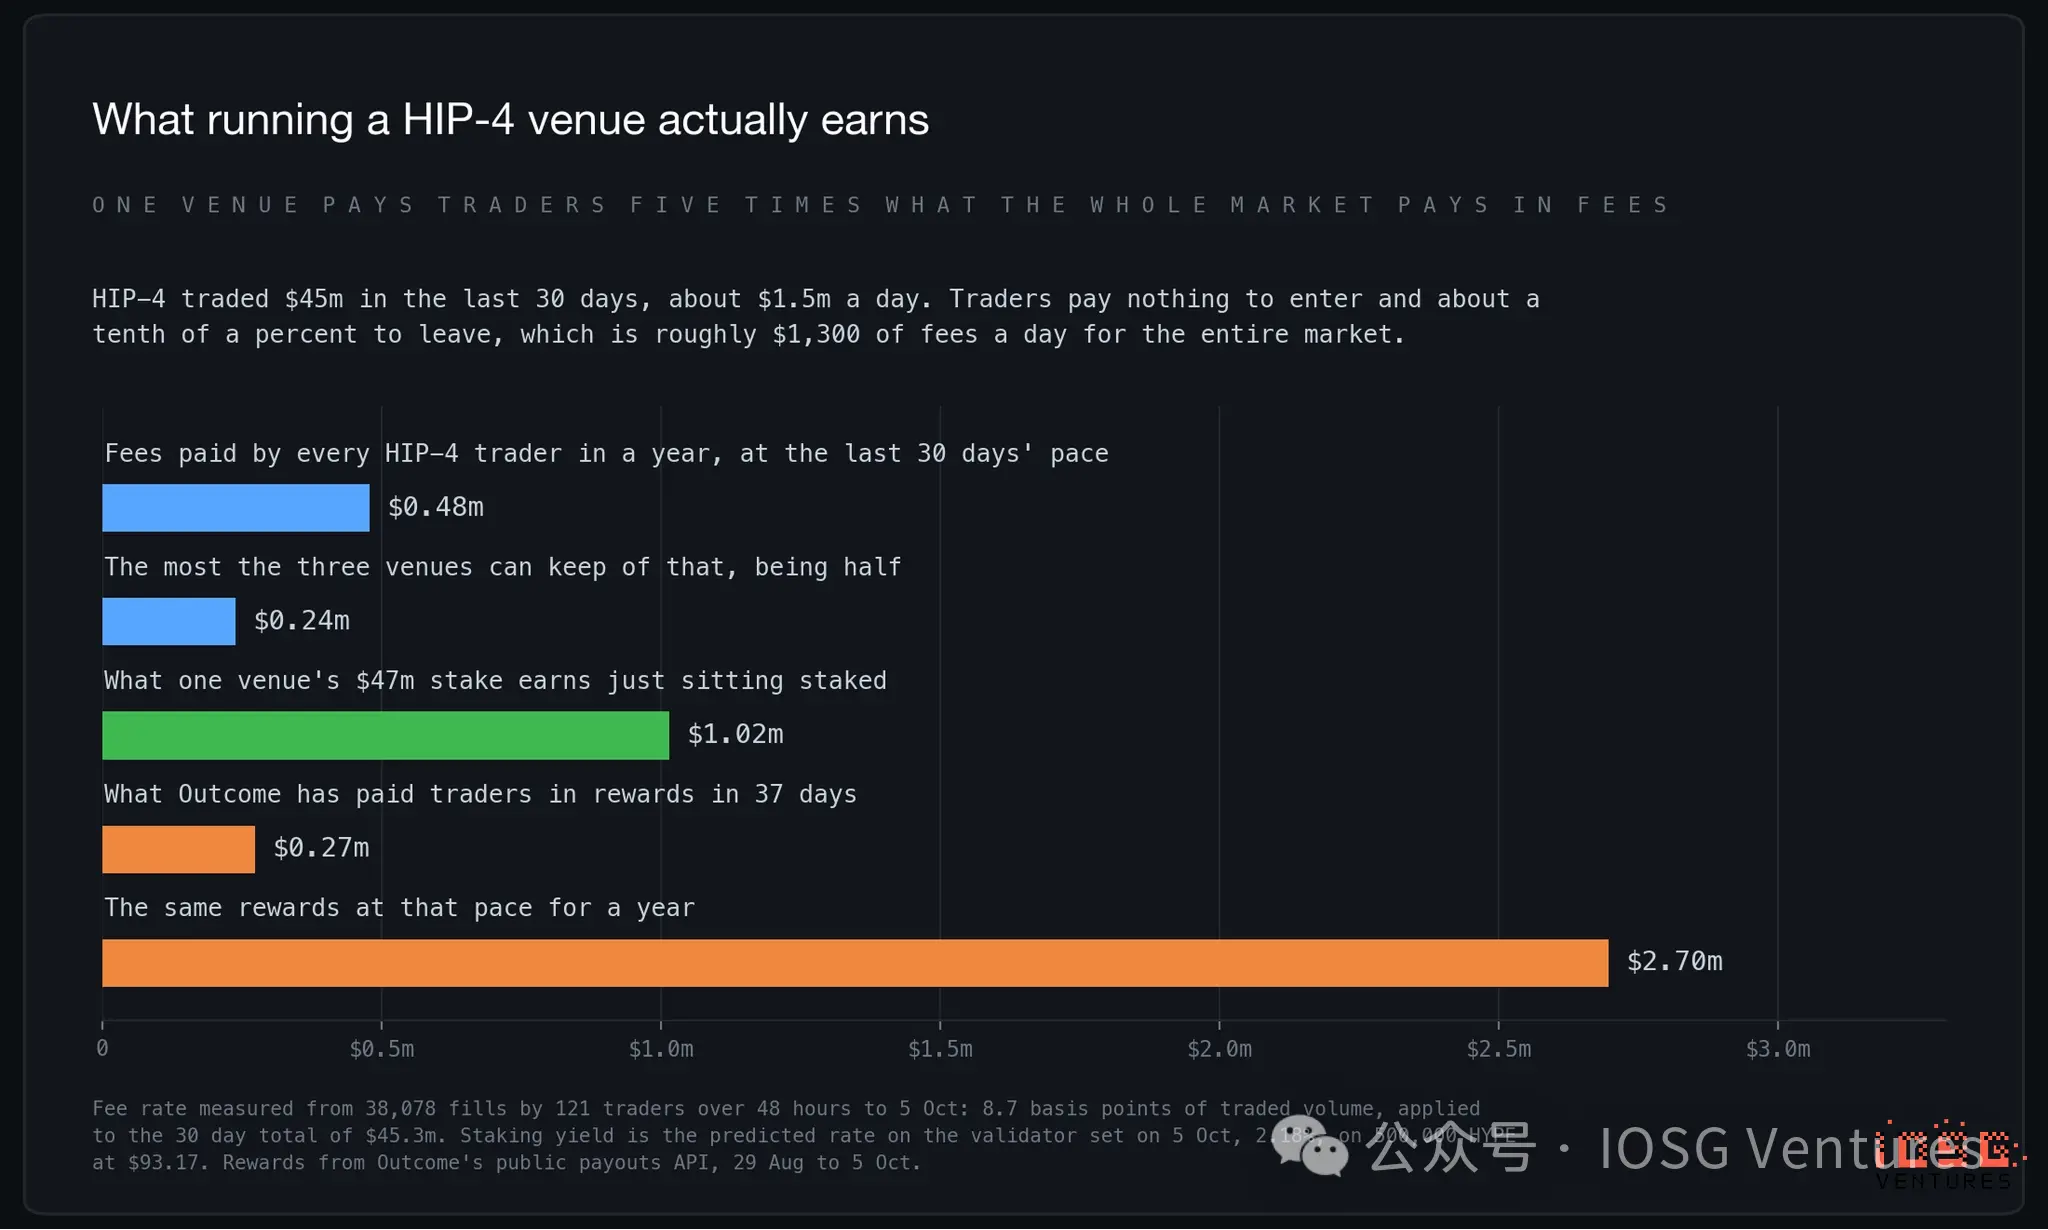
Based on the past 30 days' pace, the total fees paid by all traders on HIP-4 in a year are about 480,000 dollars. The venue takes at most half, and it has to be split among three parties. A venue that must lock up staking to enter can earn 1 million dollars by leaving it idle for a year; meanwhile, the one with the highest transaction volume is issuing rewards at a rate of 2.7 million dollars per year to exchange for these transactions.
According to these figures, no venue is actually doing business. They are buying an option, which also has value: Hyperliquid states that the deployer can later raise the rates themselves, and the transaction volume can grow to support the costs, while the private equity valuations for this track are 22 billion and 21 billion dollars, and Kalshi is still negotiating at 40 billion. But it is ultimately an option, and the holding cost is a stake of 47 million dollars; if transactions do not come in, it will expire worthless.
6. Conclusion: Design leads, market has not arrived
The building blocks are well assembled, but the market has not yet come.
Based on the dimensions that engineers would choose, Hyperliquid has created a better product: one account, one pool of margin, with betting and the positions it needs to hedge on the same interface; the settlement method is written into the template before the first transaction; the Yes and No for the same question share the order book, ensuring liquidity is not split. There have been no signs in the past five months indicating that design is a bottleneck.
The strongest reason supporting it is that you never have to leave. Margin, hedging, and betting are all in one account, and for a trading desk already engaged in perpetual trading on Hyperliquid, adding a predictive position is just a matter of clicking, without needing to switch platforms, open new balances, or transfer back and forth. Regardless of the outcome of the competition with Kalshi, this aspect has value and is the reason it will continue to exist at some scale even if it cannot do business. However, it is no longer as unique as it was in August: Polymarket is now also selling leverage next to betting, and it started from the side with users.
It is still not deep enough. On the 25 most active order books, the median bid-ask spread is 0.29 cents, with about 4,700 dollars hanging within one cent of the best sell price. A market order of 1,000 dollars only executes a few basis points above the best sell price; a 10,000 dollar order has to pay an additional 2% to 3%, and among these 25 order books, there are four or five that cannot be filled based on visible orders. Retail scale trading is fine here, but large funds cannot. Market makers are constantly repricing, and the result of patiently placing orders will be better than these numbers, but the order book is so thin, which is what a market that has been online for five months looks like.
There is also not much to trade. The transaction volume in prediction markets is composed of topics, which either come from an editorial team that lists hundreds of events weekly or from sports schedules. HIP-4 has 28 approved phrases, and three venues each staked 47 million dollars to use them, with two already listing the same questions. Kalshi can open a market for a piece of news in an afternoon.
The user base is also very specific. Each address trades eight times a day; this is a trading desk, not the general public for betting. If the goal is to create capped-yield tools for crypto traders, that is fine, as this design excels at that. However, if the goal is to target the group that Kalshi and Polymarket are competing for, it does not work, and the fact that two-thirds of the risk capital is staked on long-term football markets indicates that each venue is still pushing in that direction.
The most likely trajectory is the mundane one. HIP-4 will always be a feature of Hyperliquid, earning a small amount; its significance lies in allowing perpetual traders to avoid opening accounts elsewhere. This is worth doing, but it is not worth valuing as a standalone prediction market business.
 Risk warning
Popular articles





