








Non-farm payrolls disappointed, and the bets on an interest rate hike in October collapsed overnight, but the warning of 5.34% for U.S. Treasuries has not yet been lifted

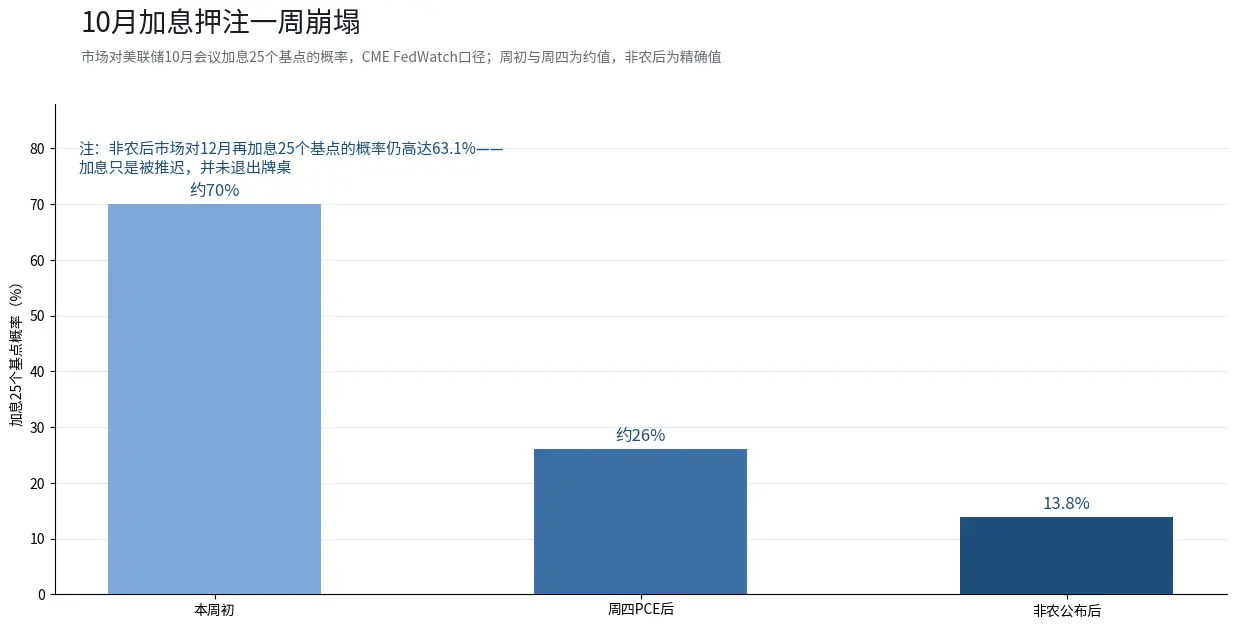
 After the data was released, the market's bets on the Federal Reserve raising interest rates in October suddenly cooled: a week ago, the probability of a rate hike was close to 70%, but it closed at 13.8% on Friday, while the probability of no action in October rose to 86.2%. However, the market's reaction is much more complex than simply "cooling rate hike expectations and rising stock markets."
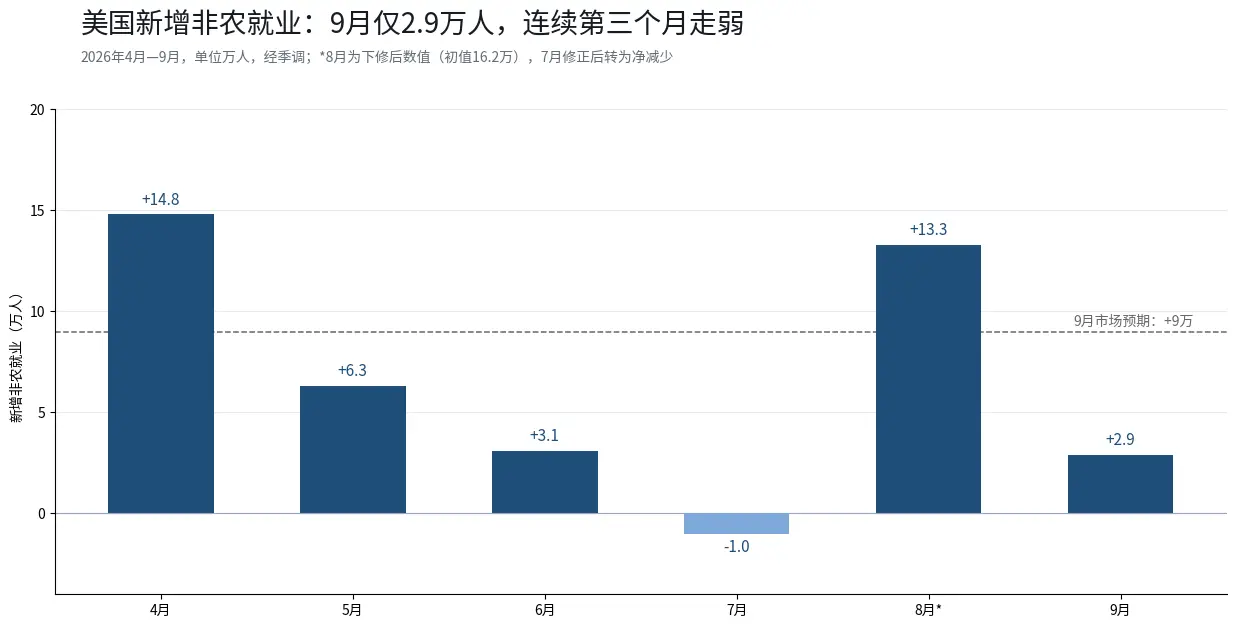
On October 2, the U.S. non-farm payroll report for September delivered an unexpected "dovish punch" to the market.
In September, non-farm employment increased by only 29,000, far below the market expectation of 90,000, only one-third of the anticipated value; the unemployment rate rose from 4.1% to 4.2%; the average hourly wage fell to 3.0% year-on-year, with a month-on-month increase of only 0.1%. More notably, there were revisions to historical data: August's new jobs were revised down from 162,000 to 133,000, and July's data was revised down by another 31,000, resulting in a net decrease after revisions— the employment picture over the past three months is weaker than what single-month data suggests.
After the data was released, the market's bets on a rate hike by the Federal Reserve in October suddenly cooled: just a week ago, the probability of a rate hike was close to 70%, but it closed at 13.8% on Friday, with the probability of no action in October rising to 86.2%.
However, the market's reaction is much more complex than just "cooling rate hike expectations and rising stock markets."
1. Rate hike bets collapse, but U.S. Treasury yields do not back down
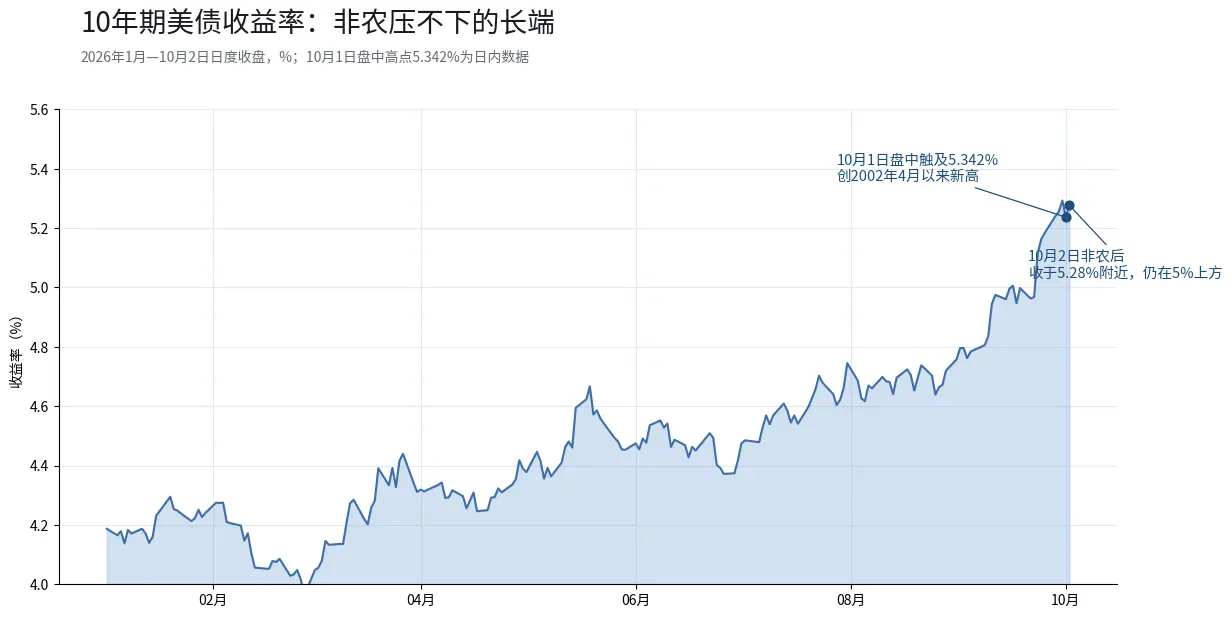
After the non-farm data was released, the 10-year U.S. Treasury yield briefly fell during the day but rebounded towards the end, closing around 5.28%. Just the day before (October 1), this number had touched 5.342%, reaching the highest level since April 2002— even after the pullback, it still stands above 5%, in a historically high range.
This is a warning signal worth noting. Weak employment data lowered the probability of a rate hike but did not pull down long-term yields. Some institutional investment managers believe that considering the resilience of the U.S. economy, there is a credible possibility for the 10-year yield to rise towards 5.5% to 6%, and rising borrowing costs may suppress stock returns. High long-term yields mean that the market's focus is not just on "whether to hike rates," but also on "how long high rates will be maintained." Even if the Federal Reserve stops raising rates, as long as long-term yields do not fall, the valuations of high-value assets may still be under pressure.
Changes in rate hike expectations also need to be understood precisely. Interest rate futures show that the probability of a rate hike in October dropped from about 26% before the data release to 13.8%, but the probability of a 25 basis point hike in December remains as high as 63.1%, and the market is no longer fully pricing in "one more complete rate hike this year." Goldman Sachs has pushed back the timing of the next rate hike by the Federal Reserve from October; New York Fed President Williams stated that there is no rush to act again after the September rate hike, but another hike later this year may be appropriate.
In other words: the rate hike has not exited the table, it has just been postponed.
2. Divergence in technology and semiconductors: AI narrative continues, traditional cycles lag behind
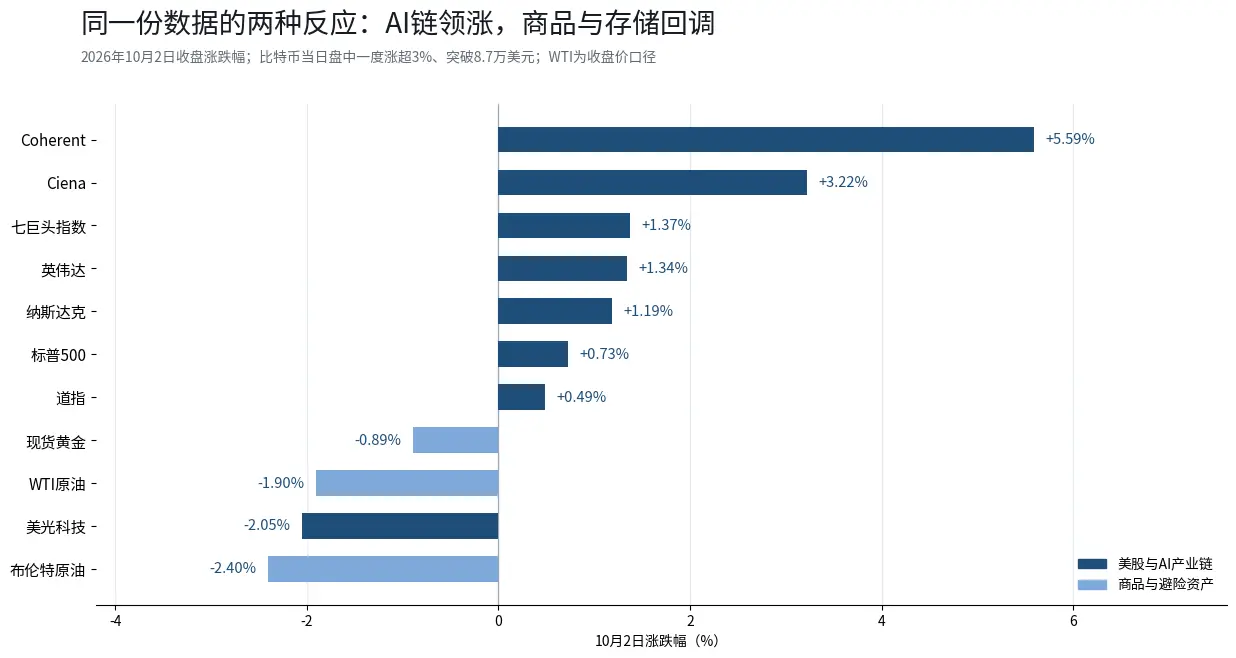
After the non-farm data was released, U.S. stock index futures briefly surged, with funds further trading on the main logic of "economic soft landing, delayed rate hikes." On Friday, the Dow Jones Industrial Average rose 0.49% to close at 51,176.96 points, the S&P 500 index rose 0.73% to close at 7,722.72 points, and the Nasdaq rose 1.19% to close at 27,190.86 points, hitting a new historical high during the day; the index of the seven major U.S. technology companies rose 1.37%, with Tesla surging 4.65% due to better-than-expected third-quarter deliveries, and Nvidia closing up 1.34%, touching $237.88 during the day, setting a new historical high, with its market capitalization briefly returning to $5.7 trillion.
However, the divergence within sectors is more informative than the index itself.
The AI industry chain continues to lead: the optical communication sector maintained its strong momentum from the previous day, with Coherent rising 5.59% and Ciena rising 3.22%— just on October 1, Coherent had surged 10.90% in a single day, and the Philadelphia Semiconductor Index rose 1.59% overall. Meanwhile, the storage sector began to lag: Micron Technology fell 2.05% on Friday, contrasting with the previous day's 3.03% gain; traditional cyclical and value sectors were also weak, with the equal-weighted S&P 500 index underperforming the weighted index, and most of the 11 sector indices showed weak performance. The index is rising, but the upward momentum is still mainly concentrated in a few AI main lines.
3. The same data, divergent answers across assets
The impact of non-farm data on various assets shows a clear directional difference.
Bitcoin briefly broke through $87,000 after the data was released, with an intraday increase of over 3%, fluctuating widely between approximately $83,700 and $87,200 throughout the day, and reported around $86,600 on the morning of October 5. The $87,000 to $87,500 area has been tested multiple times by the market recently, and whether it can effectively break through remains uncertain and may be influenced by risk appetite factors next week.
Gold experienced a "roller coaster" of rising and falling: after the non-farm data was released, spot gold briefly surged over 1%, surpassing $4,200, but the upward momentum could not be sustained, closing at $4,140.09, down 0.89% for the day, while COMEX gold futures closed at $4,172.1. On the previous trading day (October 1), gold prices had also surged to $4,218 before plummeting. Since late August, gold prices have cumulatively fallen by over 10%. The suppressing factors are clear: a strong dollar and persistently high U.S. Treasury yields have outweighed the positive impact of the employment data; some institutions analyze that short-term precious metals will mainly fluctuate, waiting for clearer monetary policy paths.
Oil prices fell sharply on Friday: the Group of Seven announced the release of 100 million barrels of strategic oil reserves, coupled with the recovery of Middle Eastern crude oil exports, with WTI briefly dropping over 4% during the day, closing at $91.11 per barrel (approximately -1.9%), while Brent fell below $100, closing around $99.9 (approximately -2.4%). However, the U.S. continues to deploy aircraft carriers and troops to the Middle East and urges allies to accelerate the release of diesel reserves, indicating that the geopolitical premium has not completely dissipated— the part of the oil price that is falling is supply, while the part that does not fall is risk.
The U.S. dollar index rose above 102.2 this week, reaching a new high since April 2025, and fell slightly to around 101.9 on Friday, but still maintained an upward trend for the week, with the dollar rising to a 17-month high against the euro. A strong dollar poses additional resistance to the rebound of gold and emerging market assets.
4. What to watch this week: three verification points
The first verification point: ISM Services PMI (Monday). This is the first major data of the week. If the service sector's prosperity cools and the price index falls, it may further solidify expectations of "high rates peaking"; if service sector inflation proves stickier than expected, it may again drive up tightening expectations and put pressure on technology stock valuations.
The second verification point: FOMC meeting minutes (Wednesday). In September, the Federal Reserve raised rates by 25 basis points to the 3.75%--4.00% range, and the key point of the minutes is how strong the committee's internal consensus is on "maintaining high rates for a long time." If more officials lean towards "no further action this year," it may provide short-term support for high-valued technology stocks; if the minutes show the committee remains vigilant about sticky inflation, the pressure on long-term yields may continue.
The third verification point: September CPI and oil price trends. Before the interest rate meeting in late October, the September CPI is the last key piece of the puzzle; with recent significant fluctuations in oil prices, OPEC+ decided on October 4 to maintain the November production target unchanged. Future production policies and oil price trends may still affect energy prices and inflation expectations, becoming one of the factors for the market to assess the December rate path.
The disappointing non-farm data has pushed October rate hike bets off the table, but the warning signal of 5.34% in U.S. Treasuries has not been lifted. Weak employment data lowered the probability of a rate hike but did not significantly lower long-term yields— this contradiction may be one of the important variables affecting technology stock valuations going forward.
Data notes: Market data as of the close of U.S. stocks on October 2, 2026 (U.S. Treasuries and commodities as of October 2 close, Bitcoin as of October 5 morning quote); non-farm employment data from the U.S. Bureau of Labor Statistics released on October 2, historical series from FRED; rate hike probabilities from CME FedWatch; U.S. stock index and individual stock price changes as of the close on October 2 (sector data for October 1 based on the previous trading day's close).
Disclaimer: The content of this article is for general information and market commentary only, compiled from publicly available information as of the time mentioned in the text, and relevant market data, expectations, and probabilities may change with market conditions. The views and investment strategies of third-party institutions, analysts, or others cited in the text represent the views of the relevant third parties at a specific time and do not represent the views or recommendations of BIT. This article does not constitute investment advice, investment research, an offer, solicitation, or recommendation of any securities, investment products, or trading strategies, nor should it be the basis for any investment decision. Financial markets carry risks, and securities prices and market performance may fluctuate; past performance and historical market trends do not represent or guarantee future results. Investors should independently assess relevant risks based on their own circumstances and seek professional advice when necessary.
 Risk warning




Popular articles





