








Kimi's parent company is reportedly preparing for an IPO in Hong Kong, with a valuation of about 50 billion USD! KeLing AI is also coming

 According to Bloomberg, KeLing AI is collaborating with China International Capital Corporation, Goldman Sachs, and UBS to prepare for an IPO on the Hong Kong Stock Exchange, aiming to go public as early as next year, with plans to raise at least $1 billion; details may still be adjusted.
Introduction: Many people use Kimi to write reports and pursue long articles, but few know that its parent company has not yet gone public. On October 6, Bloomberg brought this matter to light: Dark Moon has reportedly completed its final round of private financing before going public, with a valuation of approximately $50 billion—an increase of about five times from around $10 billion within a year; on the same day, Kuaishou also pushed its most valuable AI asset, Keling AI, onto the IPO track. This is not just two isolated pieces of news about new stocks, but a signal that the capitalization of AI in the Hong Kong stock market is moving from individual cases to batches: the window is real, and the competition within the window is also real.
I. What Happened: Two News Items, One Signal
According to Bloomberg, Dark Moon has completed its final round of private financing before going public, with a valuation of approximately $50 billion. The company has begun preparing for investor communication and may start preliminary discussions as early as this month; previously, it was reported that the company had submitted a confidential listing application to the Hong Kong Stock Exchange, with Bank of America serving as the overall coordinator, and China International Capital Corporation, Deutsche Bank, and Goldman Sachs acting as sponsoring banks. Reports indicate that discussions are still ongoing, and the IPO timeline may change; Dark Moon has not responded to requests for comment.
On the same day, Bloomberg reported that Keling AI is collaborating with China International Capital Corporation, Goldman Sachs, and UBS to prepare for a Hong Kong IPO, aiming to go public as early as next year and planning to raise at least $1 billion; details may still be adjusted, and Goldman Sachs and UBS declined to comment. Additionally, The Information previously reported that regulators have initiated data security investigations into DeepSeek and Dark Moon—whether this will affect valuations or timelines is currently inconclusive.
The simultaneous release of these two news items leads us to believe it is not a coincidence: the current capacity of the Hong Kong new stock market, the channel of Chapter 18C, and the preferences of southbound funds together constitute a window that may not exist for long. For companies preparing for an IPO, what they gain by submitting their applications is not time, but pricing power.
II. Valuation: A 50x Price-to-Sales Ratio is Not Valuation, It's a Bet Agreement
First, look at this curve: According to publicly reported data, from January to February, the valuation rose from $10 billion to $18 billion over three rounds of financing; after the D round in May, it was about $20 billion; a summer round was approximately $31.5 billion (other reports indicate a subsequent round of about $35 billion, with discrepancies in figures); the latest round is about $50 billion. About five times in one year.
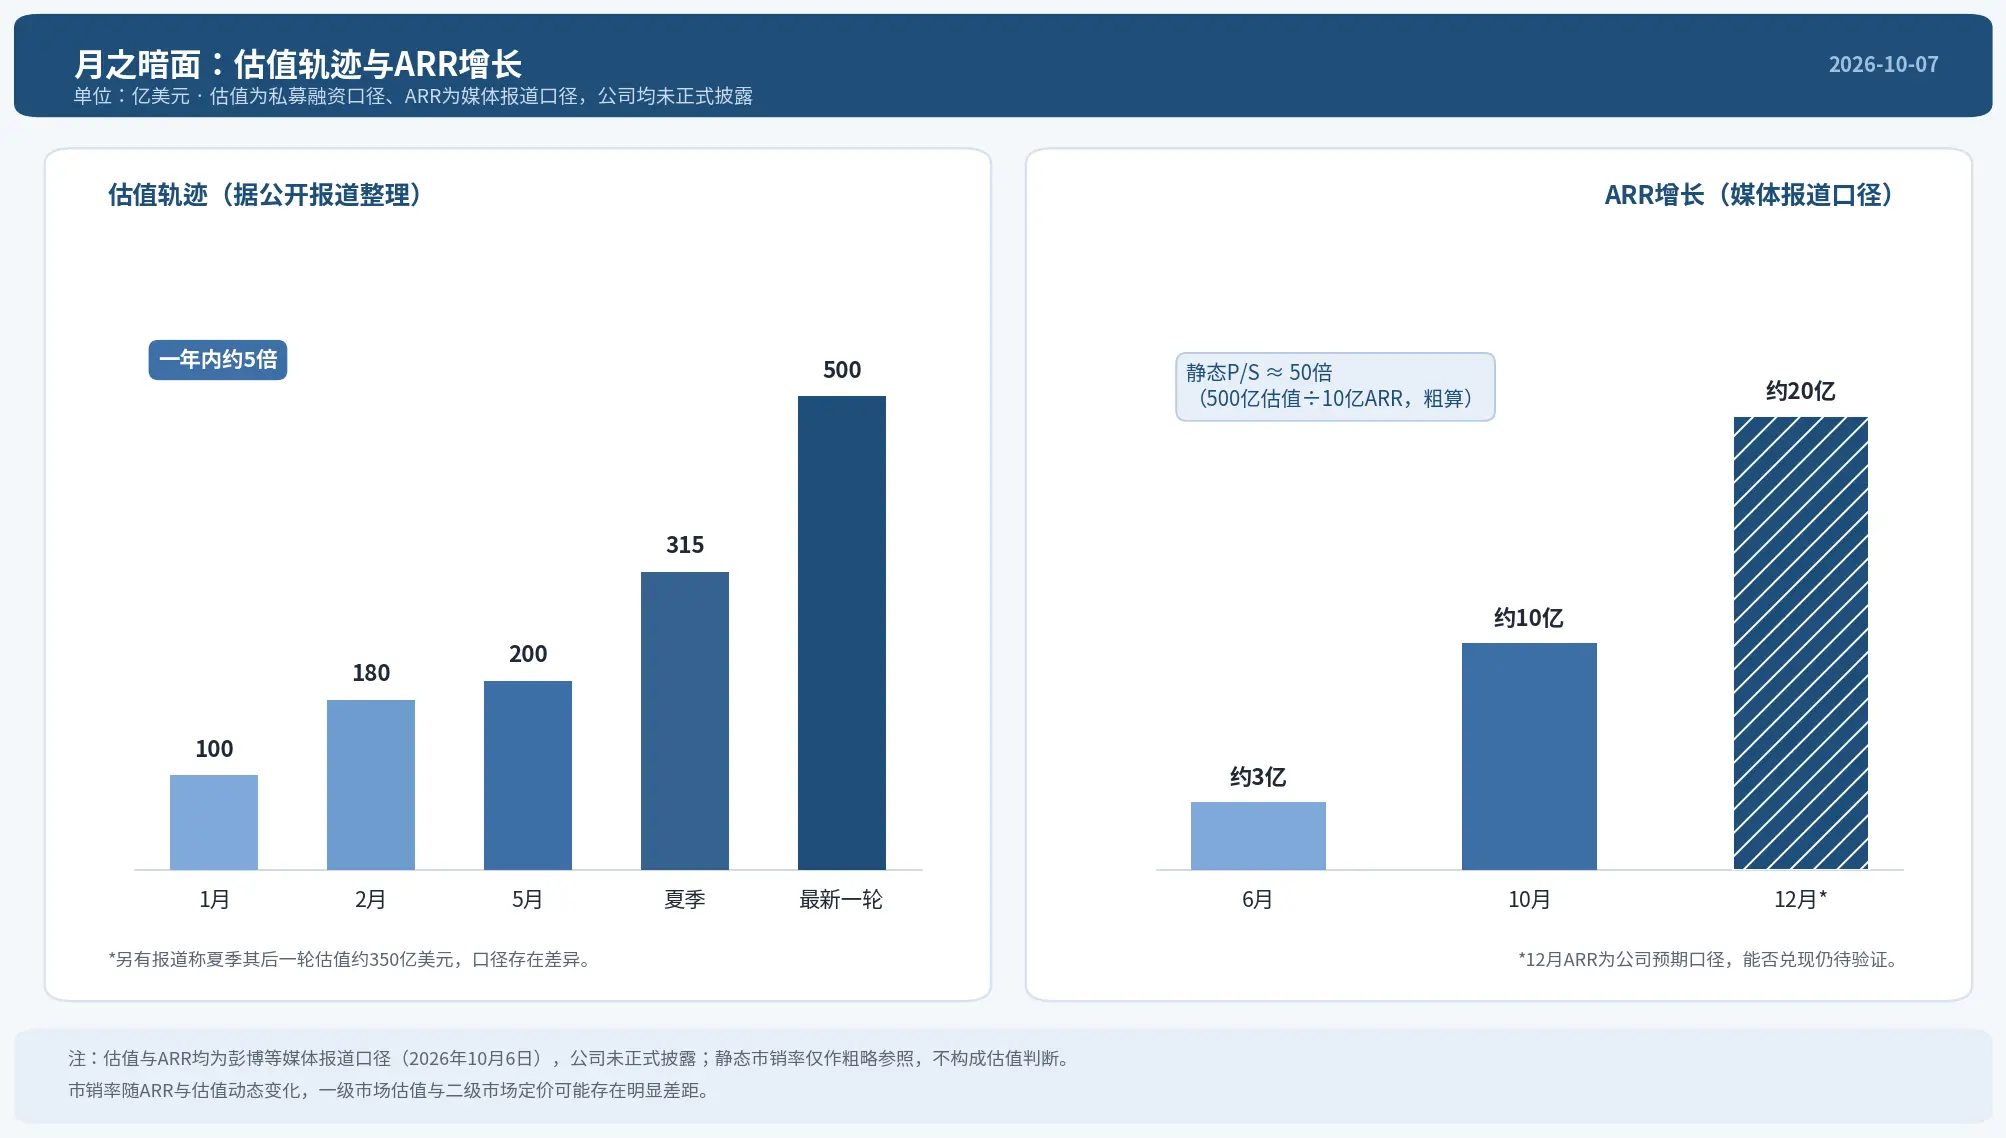
The supporting story is revenue growth rate, not revenue scale. According to Bloomberg, ARR rose from about $300 million in June to about $1 billion currently, and the company expects it could reach $2 billion by December—note that this is the company's expected figure. In terms of business model, the C-end is Kimi's tiered subscription, while the B-end outputs underlying technical capabilities to enterprises. In June, the intelligent product Kimi Work was launched, and in July, the open-source model Kimi K3 was reported to be comparable to leading models from OpenAI and Anthropic on some evaluation metrics.
Our view is that the approximately 50x static price-to-sales ratio does not reflect the current Dark Moon, but rather a bet agreement regarding the speed of ARR realization. Let's do two rough calculations: $50 billion against $1 billion ARR gives a static ratio of about 50x; even if ARR doubles to $2 billion as expected, the forward price-to-sales ratio would still be 25x. The reference point is the secondary market: Zhizhu's market value was approximately HKD 313.4 billion on October 6, with about $1.8 billion ARR, giving a static ratio of about 22x. The multiple given to Dark Moon in the primary market is more than twice that given to its listed peers in the secondary market—the gap in between can only be filled by two things: either ARR continues to grow at a rate exceeding the current pace, or the IPO pricing falls back to the secondary anchor. The essence of the IPO pricing discussion is this negotiation; if the ARR reaches about $2 billion in December, it will be the first acceptance point of this bet agreement.
III. Hong Kong New Stock Market: The Window Exists, But Is Being Used Up
KPMG's third-quarter review released on October 6 shows (as reported by the media): In the first three quarters, there were 116 new stock listings, raising a total of over HKD 388 billion, more than double the same period last year, setting a record for the highest amount ever raised in the same period; active listing applications exceeded 600, significantly higher than previous years; the total amount raised for the year could reach HKD 500 billion, which would break the annual record of HKD 427 billion set in 2010.
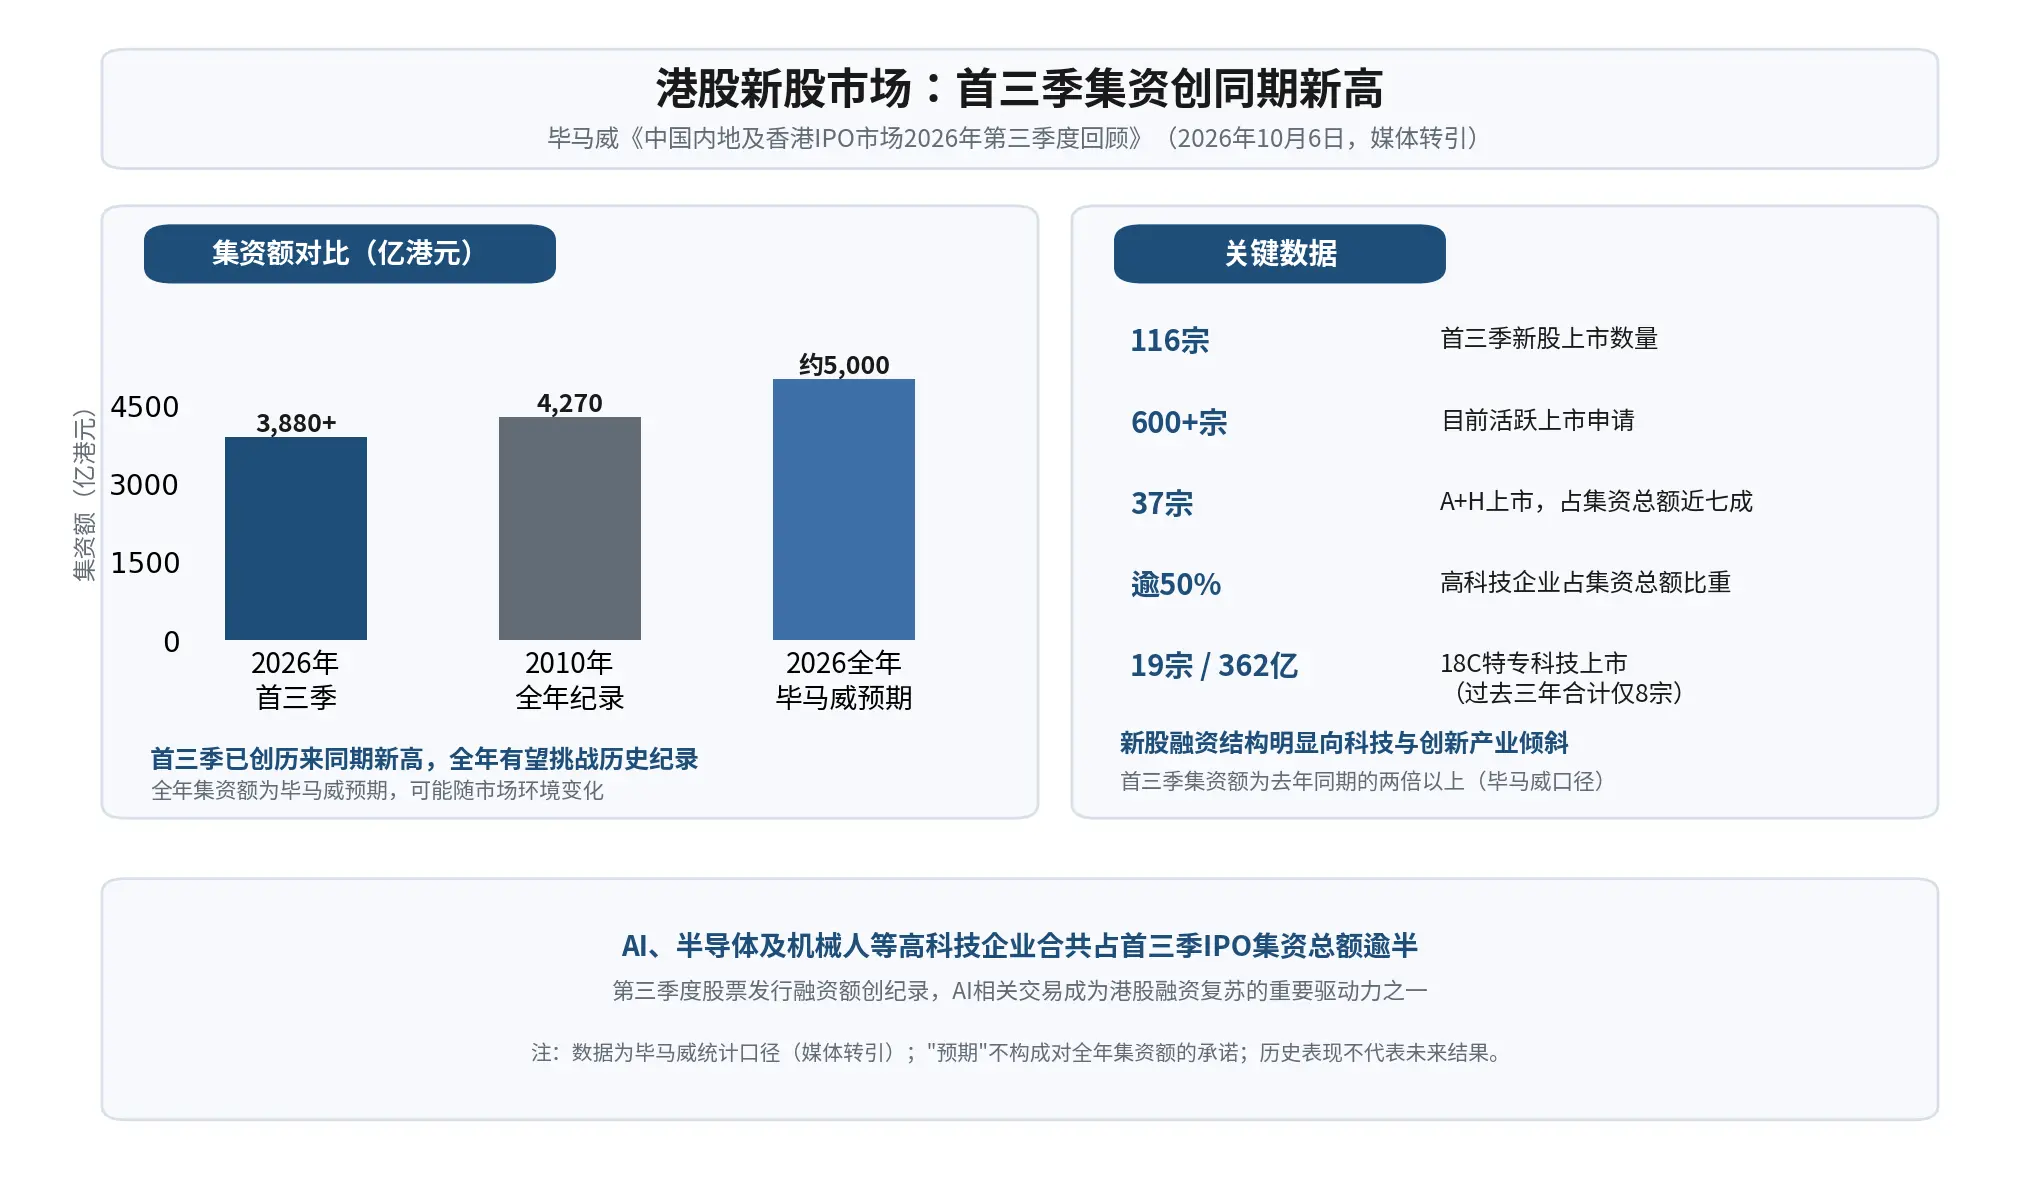 Two structural clues are worth noting: High-tech companies (AI, semiconductors, robotics) account for more than half of the total amount raised, and the stock issuance financing amount in the third quarter reached a record; during this period, 19 specialized technology companies listed under Chapter 18C, raising HKD 36.2 billion, while only 8 listings occurred in the past three years combined. Our judgment on the Chapter 18C channel is that it has transformed from a backup door to the main door, and once the main door opens, the countdown to scarcity begins. The listing qualification requirements for Chapter 18C mainly include market value, R&D investment, and other related conditions, and do not require profitability as a prerequisite, thus providing a listing path for specialized technology companies still in the investment phase. However, the larger the throughput of the channel, the thinner the scarcity premium that individual targets can enjoy—the companies that submit applications this year enjoy the window, while those submitting applications next year may face a filled allocation.
IV. Keling AI: Continuation of Ammunition in the Arms Race, Not a Simple Exit
Keling AI is set to launch in 2024, focusing on generative AI video. According to Bloomberg, after OpenAI shut down Sora, Keling and other Chinese service providers are vying to capture the market space left behind; in July, it completed a $2.8 billion financing round, with a pre-investment valuation of about $15 billion, and investors include Alibaba, Tencent, and Baidu. At the end of August, according to announcements and reports from Kuaishou, another round of capital increase was completed, and the independent financing quota initiated this year has been fully utilized.
Placing Keling's IPO within the competitive landscape, our interpretation is that this is a continuation of ammunition in the arms race, rather than a simple exit of shareholders. ByteDance's Seedance, Shusheng Technology (which is also reportedly planning to go public in Hong Kong), and PixVerse (Aishi Technology, same as above) are all betting on the same track; the computing and data costs for video generation are extremely high, and the decisive factor in this track is likely not the model rankings, but cash flow sustainability—whoever exhausts their capital ammunition first will fall behind. There is currently no answer to how much of the void left by Sora's exit can be filled and for how long; however, the length of the competitor list itself is a hint: money in this track is currently being burned faster than it is earned.
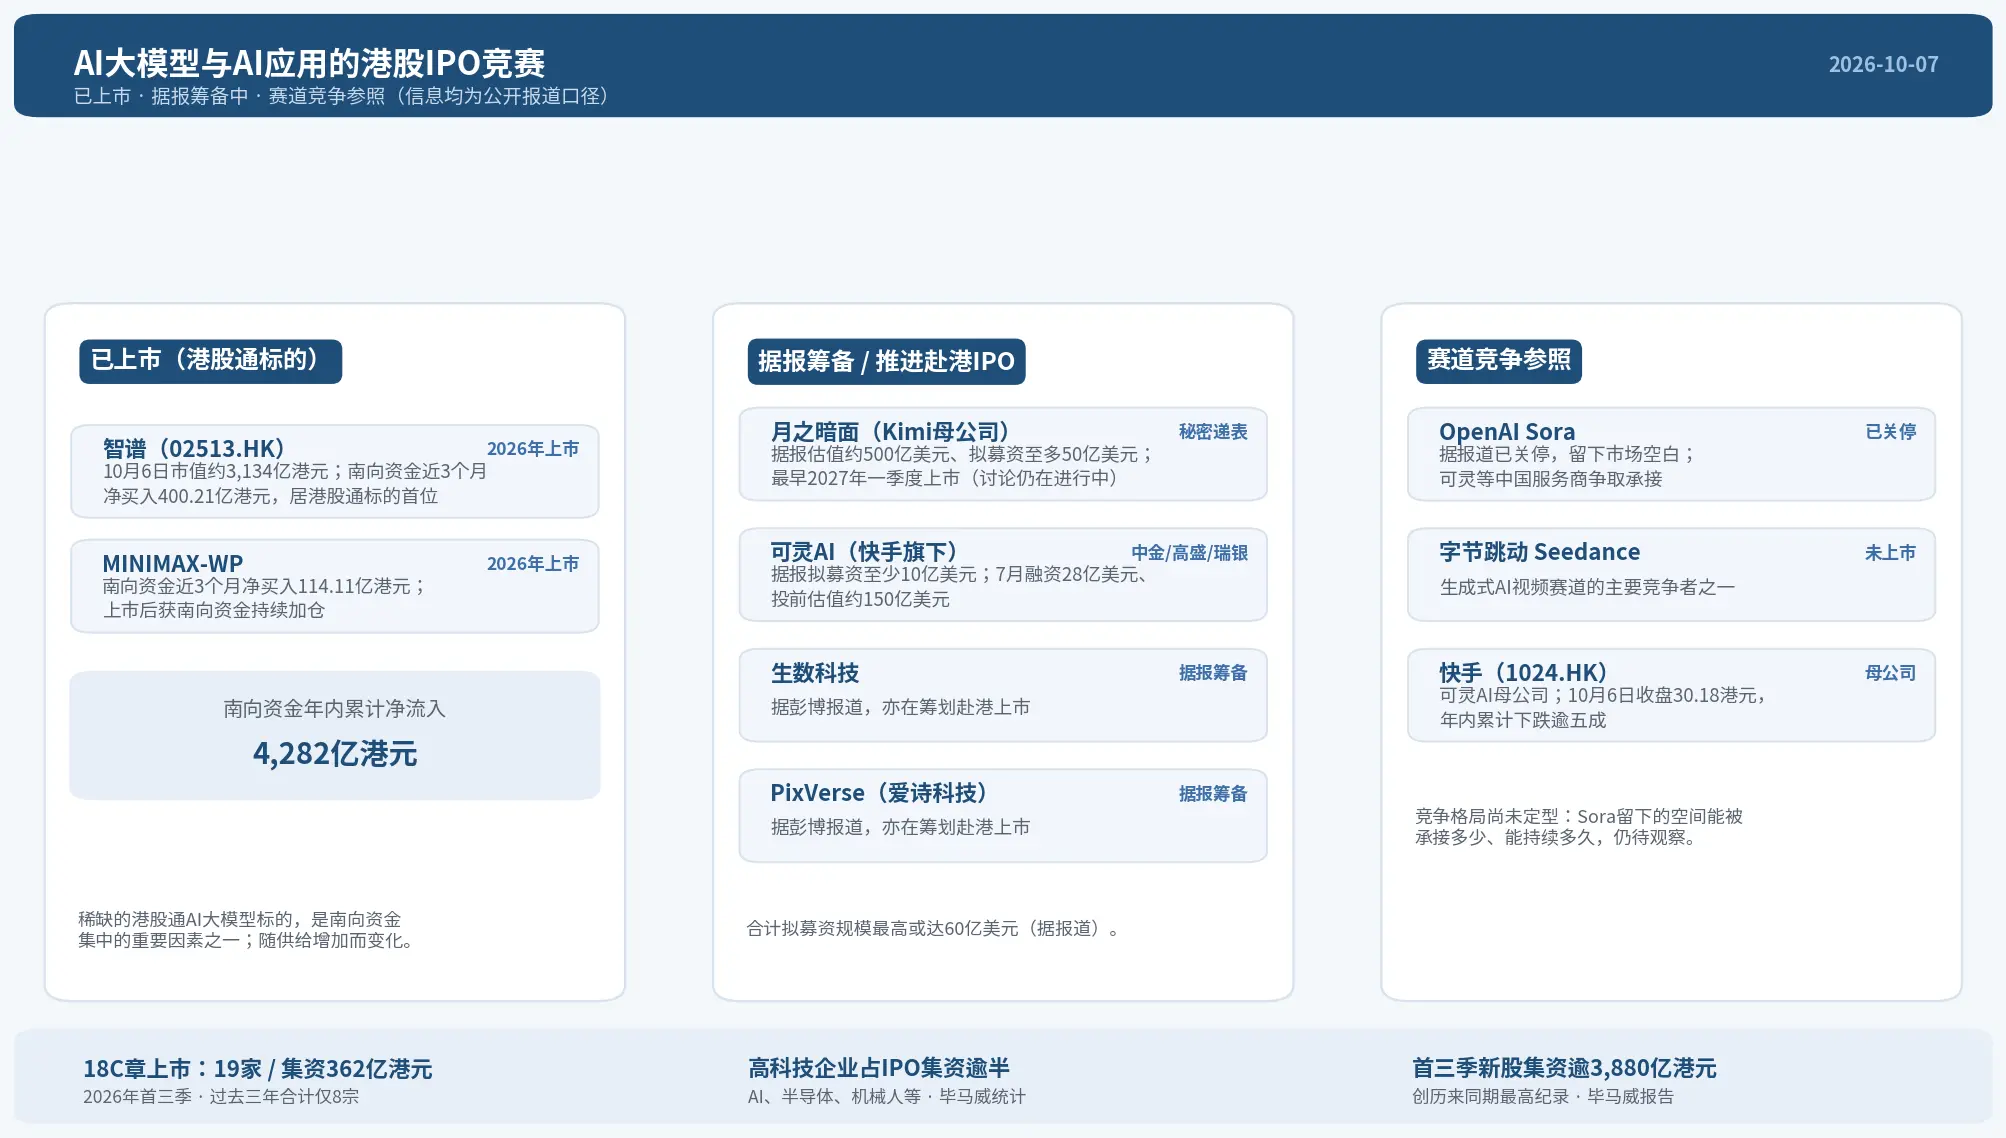 The stock price of the parent company is another variable worth considering. According to Bloomberg and verified by market data, Kuaishou has fallen by more than 50% this year (closing at HKD 66.25 on the first trading day of 2026 and HKD 30.18 on October 6). This double-edged sword is sharp on both sides: a weak parent company may suppress Keling's valuation expectations; conversely, separating the AI assets from Kuaishou's "content platform valuation" for independent pricing is precisely the first opportunity for the market to quote the AI video business separately—whether this separation results in a premium or discount will be answered by the issuance pricing. We tend to believe that the latter may also be one of the factors Kuaishou is considering for a spin-off.
V. Why Hong Kong, Why Now
Southbound funds are the key variable for absorption. According to Wind, southbound funds have accumulated a net inflow of HKD 428.203 billion this year (as of September 28), with a holding market value of about HKD 6.02 trillion (as of September 29); in the past three months, the top net purchases have all been AI-related stocks—Zhizhu at HKD 40.021 billion leading, followed by MINIMAX-W at HKD 11.411 billion. Based on this structure, if Dark Moon and Keling AI go public and are included in the Hong Kong Stock Connect, marginal buyers are likely still within this batch of funds; their performance after going public will, in turn, determine southbound funds' overall attitude towards large models as an asset class—the performance of the first batch of targets will set the pricing environment for later entrants.
Scarcity premiums have a shelf life, which is the answer to "why now." After the listings of Zhizhu and MINIMAX-W, southbound funds continued to increase their positions, with the important background being that there are simply too few large model stocks in the Hong Kong Stock Connect; according to KPMG, there were 19 Chapter 18C companies listed in just the first three quarters, with over 600 applications queued. When "scarcity" turns into "bulk," the first movers enjoy pricing power, while later movers face the tail end of the allocation. For companies preparing for an IPO, the pricing power during the window period is more valuable than the window itself—this is our core understanding of the current intensive application submission rhythm.
VI. What to Watch Next
Progress of applications and hearings: The formal application version disclosed by the Hong Kong Stock Exchange, especially the disclosure standards for ARR composition, subscription, and B-end revenue breakdown;
Feedback from preliminary investor discussions: The intention communication that may start as early as this month is the first-hand window to observe secondary buyers' attitudes towards the 50x static price-to-sales ratio;
Whether the ARR can realize the expected $2 billion by December: This is the core data point for whether the valuation story can be self-consistent;
Kuaishou's stock price and market environment: The performance of the parent company, interest rate environment, and overall enthusiasm for new stocks will all influence the issuance pricing.
Conclusion
Three sentences summarize our judgment. First, the approximately 50x static price-to-sales ratio for Dark Moon compared to Zhizhu's approximately 22x reflects a gap in growth expectations between the primary and secondary markets—the December ARR data will be one of the important observation points: if it can be realized, it will provide some support for the current valuation logic; if it cannot be realized, it may increase the likelihood of the market reassessing its valuation. Second, the transformation of the Chapter 18C channel from a backup door to the main door means that scarcity is entering a countdown, and the essence of this round of intensive application submissions is to seize pricing power, rather than just joining the excitement. Third, Keling AI's IPO is a continuation of ammunition in the AI video arms race, where the decisive factor lies in cash flow sustainability rather than rankings; the weakness of Kuaishou's stock price may suppress valuations, but it may also be the motivation for a spin-off. The above judgments are based on current publicly available information, and conclusions may change with changing conditions.
Data Sources
Bloomberg (2026/10/6), KPMG Q3 2026 Review, Wind, exchange market data, and public reports.
Dark Moon: Valuation of approximately $50 billion, planning to go public in Q1 2027, raising up to $5 billion; ARR $300 million → $1 billion → $2 billion; valuation $10 billion → $18 billion → $20 billion → $31.5 billion (with another figure of $35 billion). The company has not officially disclosed this.
Dark Moon Sponsors/Applications: Bank of America, China International Capital Corporation, Deutsche Bank, Goldman Sachs; confidential application submission.
Keling AI: Underwriting by China International Capital Corporation, Goldman Sachs, UBS; planning to raise at least $1 billion; completed $2.8 billion financing in July, with a pre-investment valuation of about $15 billion. Kuaishou's announcement includes discrepancies such as an additional financing quota of about $3 billion.
Hong Kong IPO: 116 listings, over HKD 388 billion raised, 600+ applications; 19 listings/362 billion HKD under Chapter 18C; high-tech companies account for more than half; the record in 2010 was HKD 427 billion.
Southbound Funds: Cumulative net inflow of HKD 428.203 billion, holding about HKD 6.02 trillion; Zhizhu at HKD 40.021 billion, MINIMAX-W at HKD 11.411 billion. As of 9/28--29.
Kuaishou: Closed at HKD 66.25 on the first trading day of 2026, and HKD 30.18 on 10/6 (approximately -54%).
Price-to-Sales Ratio: The Dark Side of the Moon is approximately 50 times static; Zhipu is about 22 times (as of October 6, the market value is approximately HKD 313.4 billion, and the mid-term ARR is roughly USD 1.8 billion). This column roughly estimates the exchange rate at approximately HKD 7.78/USD, for reference only, and does not constitute a valuation judgment.
Note: The Dark Side of the Moon and Keling AI related information has not been officially disclosed by the company and is based on media reports; there are discrepancies in the announcements from Keling AI and Kuaishou, which have been noted in the text.
Disclaimer: The content of this article is for general information and market commentary purposes only, compiled based on publicly available information as of the time mentioned in the text. Relevant market data, expectations, and probabilities may change with market conditions. The views and investment strategies quoted from third-party institutions, analysts, or other individuals only represent the views of the relevant third parties at a specific time and do not represent the views or recommendations of BIT. This article does not constitute investment advice, investment research, an offer, solicitation, or recommendation for any securities, investment products, or trading strategies, nor should it be used as the basis for any investment decision. Financial markets carry risks, and securities prices and market performance may fluctuate; past performance and historical market trends do not represent or guarantee future results. Investors should independently assess the relevant risks based on their own circumstances and seek professional advice when necessary.
 Risk warning




Popular articles





