The most profitable quarter in Samsung's history, yet the stock price is 30% lower than the peak in June

Introduction: A company has reported the most profitable quarterly performance in the history of its domestic enterprises, yet its stock price fell on the same day, retreating about 30% from its peak six months ago. Putting these two facts together, the question shifts from whether the performance is good or not to what the market is pricing. This article first verifies the performance itself, then examines the sources and destinations of profits, explains how to interpret the stock price, and finally places Samsung's accounts back into the entire AI hardware industry chain.
1. The performance itself: Quarterly profit is approximately 2.5 times the total for the year 2025
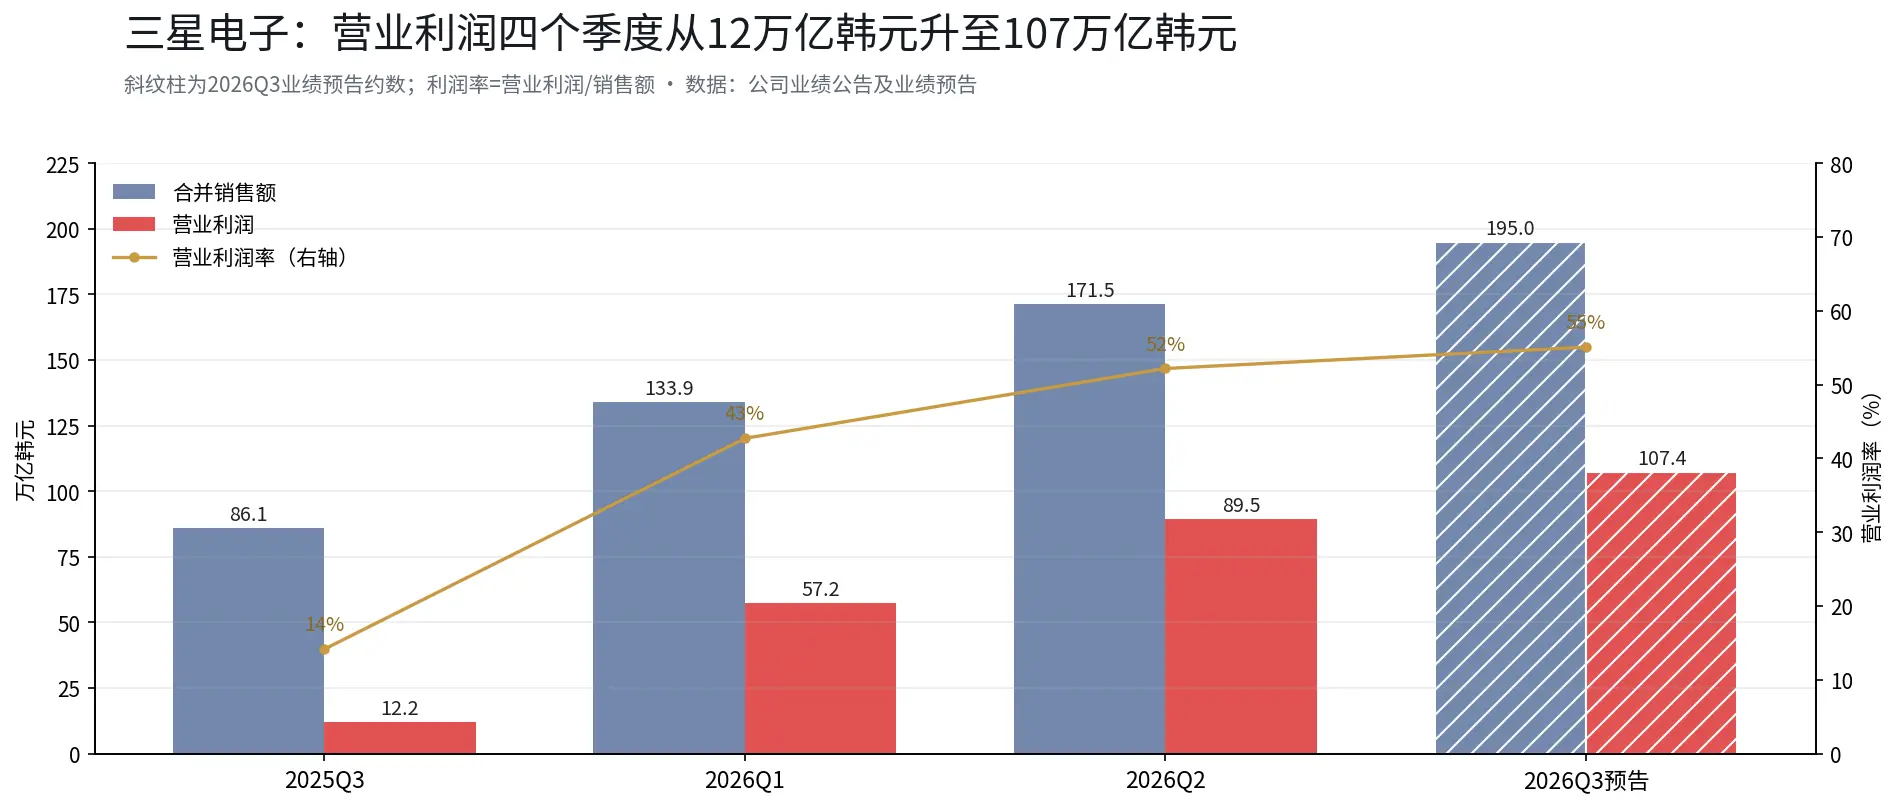
First, let's verify the numbers. The forecast for Q3 2026: consolidated sales are approximately 195 trillion Korean won, a year-on-year increase of 126.6%; consolidated operating profit is approximately 107.4 trillion Korean won, a year-on-year increase of 782.5%. This marks the first time in the history of Korean enterprises that quarterly operating profit has exceeded 100 trillion Korean won; for comparison, Samsung's total operating profit for the year 2025 is 43.6 trillion Korean won, meaning it achieved about one and a half years' worth of profit in just one quarter.
Looking at the last four quarters, the slope itself forms a narrative: Q3 2025 operating profit was 12.17 trillion Korean won, Q1 2026 was 57.2 trillion, Q2 was 89.5 trillion, and the Q3 forecast is 107.4 trillion. The operating profit margin rose from 14% to about 55%.
However, the same number can be interpreted in two ways. The first interpretation is horizontal: 107.4 trillion Korean won is a historical record. The second interpretation is slope: the year-on-year growth rate in Q2 was 1813.8%, which dropped to 782.5% in Q3. Both interpretations are true, but the stock price chose the second one. It is important to note a technical fact: such a large year-on-year growth rate largely stems from the low base in the same period of 2025. Looking at the two years together, the memory industry is in the middle of a historically significant upward cycle, and past performance does not guarantee future results.
2. Where the money comes from and where it goes
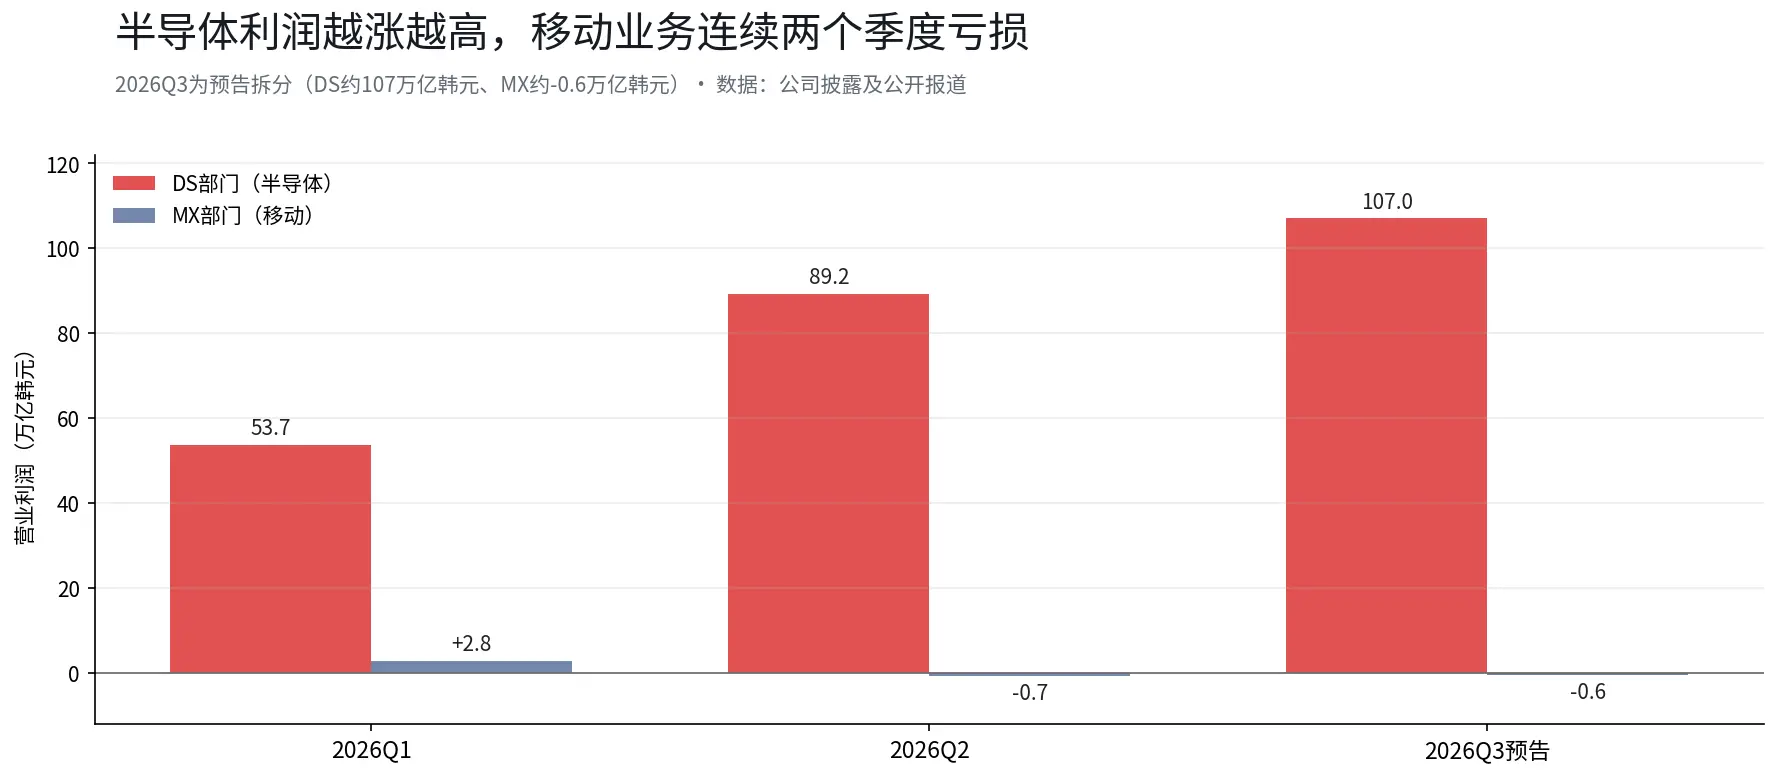
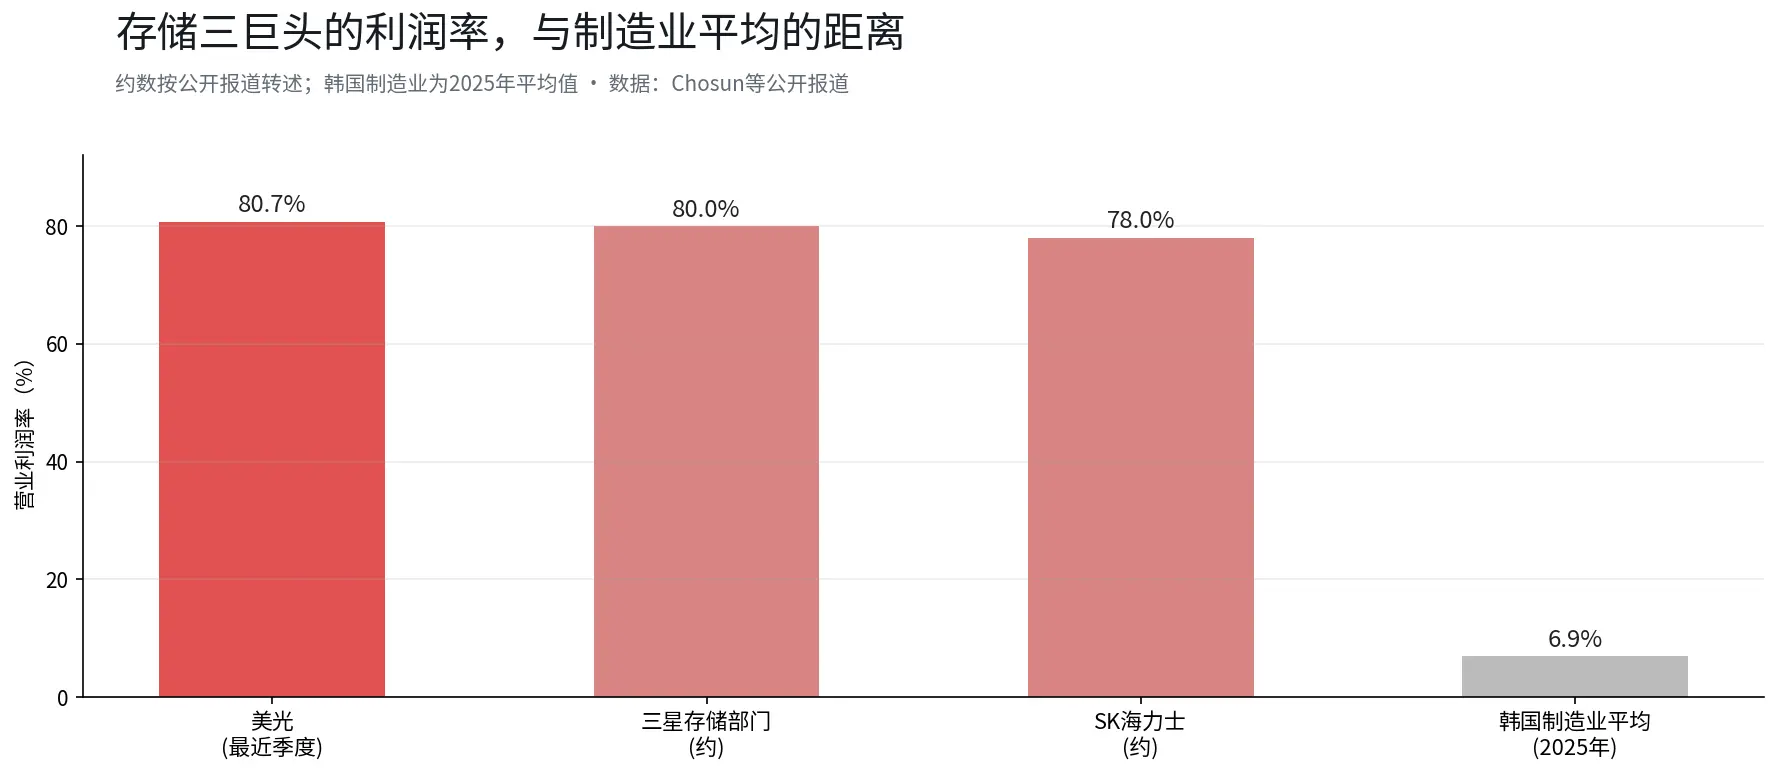
According to Citigroup's breakdown, Samsung's semiconductor division's operating profit for Q3 is approximately 107 trillion Korean won, further increasing from Q2's 89.2 trillion. The profitability levels of the three major memory manufacturers are rewriting the common knowledge of the manufacturing industry: according to public reports from Chosun and others, Micron's operating profit margin in the most recent quarter was 80.7%, Samsung's memory division was about 80%, and SK Hynix was about 78%. For reference, the average operating profit margin for Korean manufacturing in 2025 is only 6.9%.
On the other end of the same income statement, money is flowing in the opposite direction. The mobile and consumer electronics divisions are expected to incur a loss of approximately 0.6 trillion Korean won in Q3, marking the second consecutive quarter of losses; smartphone shipments fell 9% quarter-on-quarter to 58 million units. A more direct action is occurring on the supply side: according to South Korean media reports, Samsung's mobile experience division has notified suppliers of plans to cut smartphone production by 20% to 30% in Q4. The company has also raised the prices of the Galaxy S26 series, with reports indicating that the starting price of the S26 has increased by 800 won to 7,799 won, and the S26+ and S26 Ultra have each increased by 1,000 won.
These two divisions are two accounts of the same company and are mutually causal. Rising prices of memory chips have pushed the semiconductor division's profit margin to around 80%; the same price increases are the direct cause of cost overruns in the mobile division. Morgan Stanley estimates that Samsung's mobile division could accumulate operational losses of up to $16 billion from 2026 to 2028 (according to its industry report released on July 21). Some of the money earned from semiconductors is being lost in its own complete machine business.
3. Why the stock price does not agree
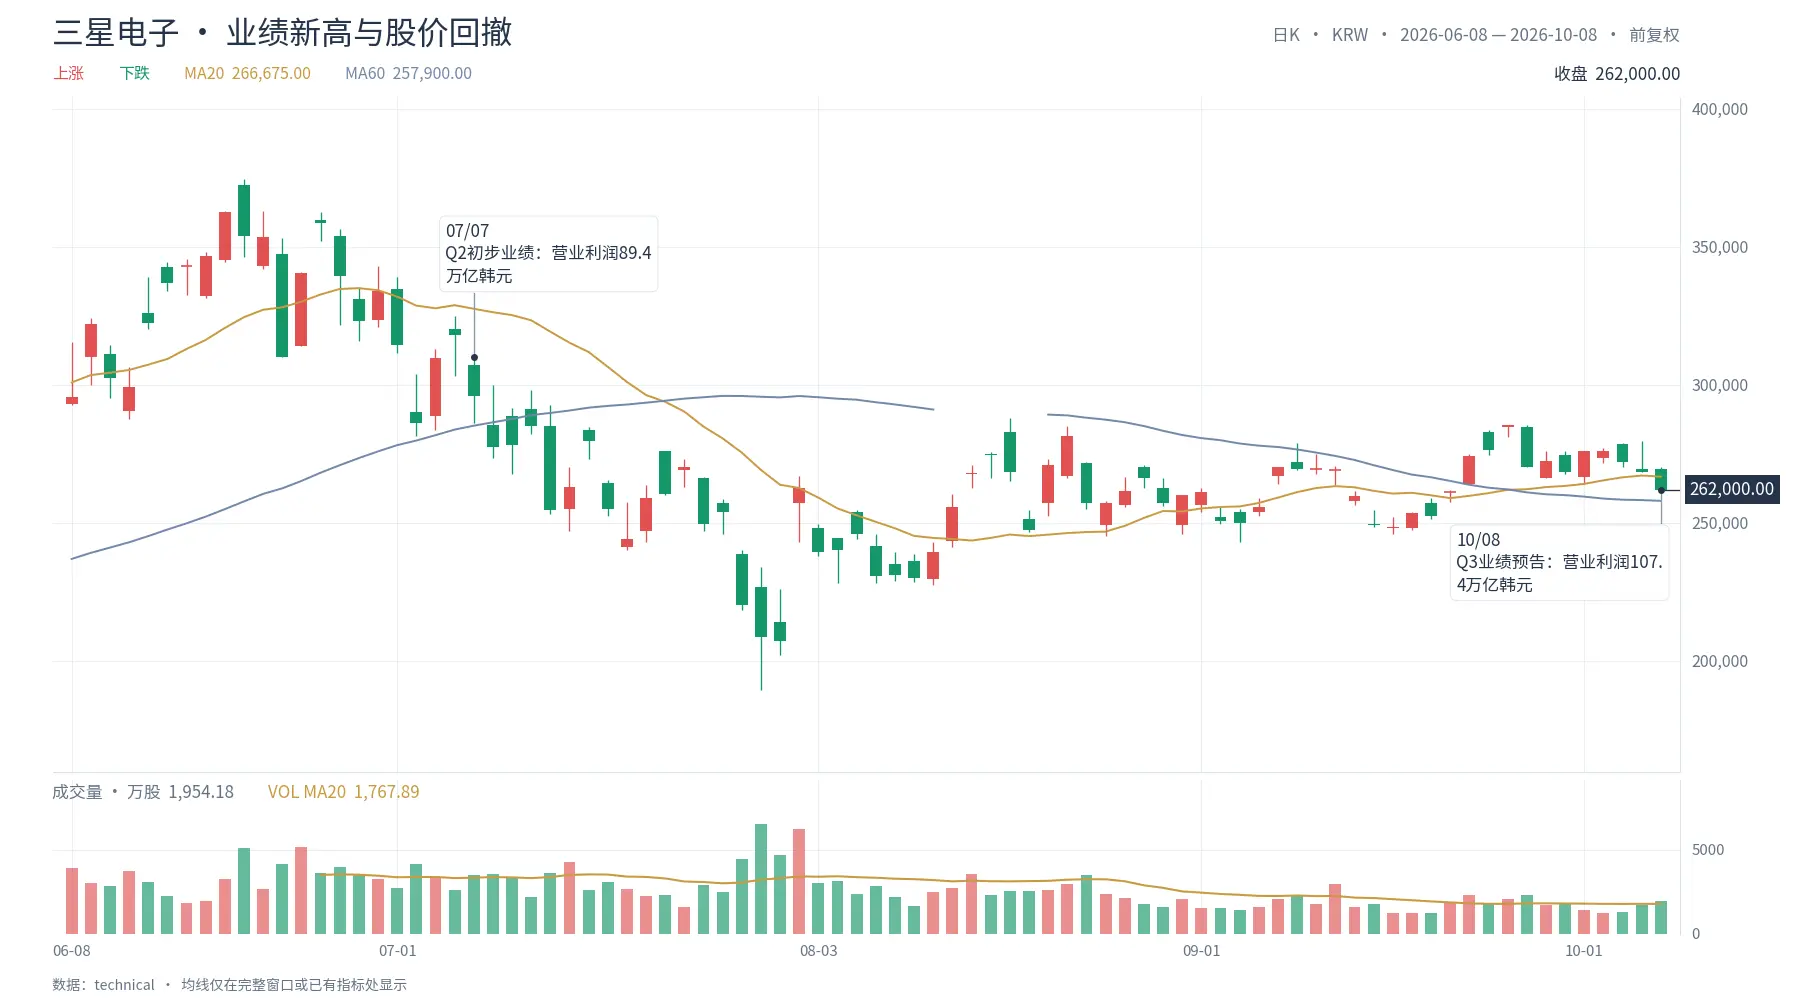
As of the close on October 8, Samsung Electronics was priced at 262,000 won, down 2.42% for the day; in the three trading days of October, it has cumulatively fallen 5.07%; compared to the intraday peak of 374,500 won on June 18, it has retreated about 30%. The stock price fell on the day the performance forecast was released, indicating that the market's pricing of this record performance occurred before the forecast, and the disclosure itself did not provide new upward momentum.
Three questions are placed on the same table. The first is the gap: Q3 revenue of 195 trillion won was lower than the brokerage estimate of about 201.9 trillion; operating profit of 107.4 trillion was lower than the estimate of about 108.67 trillion. The gap is only around 1%, which usually would not shake the stock price, but at a time when expectations are highly consistent, a slightly lower-than-expected signal will be amplified. The second is the slope: the year-on-year growth rate dropped from 1813.8% in Q2 to 782.5% in Q3, and on a quarter-on-quarter basis, the increase in operating profit also slowed from 56% in Q2. The third is inventory and upward momentum: according to Morgan Stanley's July report, the market's upward momentum for memory manufacturers' profits is weakening, with the proportion of net profit revisions falling from a peak of 92% to 77%, and the year-on-year growth rate of DRAM contract prices has fallen from the cyclical high, with both DRAM and NAND inventories having rebounded in Q2.
Capital expenditure is another layer of pressure hidden in the downstream of the profit statement. In Q2, Samsung's capital expenditure was 16.8 trillion won, of which 15.4 trillion was for the semiconductor division; to fill the capacity gap, the company has initiated and plans to continue investing hundreds of trillions of won to expand memory wafer fabs over the next two years. If in the second half of the year, to expedite the production of HBM4, the company continues to increase factory construction and depreciation investments, this expense may appear in the next one or two quarters' reports. The market is concerned that this expenditure might consume a large portion of incremental profits in some quarter.
4. Citigroup's logic and a more fundamental question
According to public reports, Citigroup maintains a buy rating on Samsung with a 12-month target price of 430,000 won, implying about 60% upside from the closing price of 268,500 won on October 7; this view only represents the judgment of the relevant institution. Citigroup's core basis lies in the pricing elasticity of HBM4: reports suggest that its estimate for the average price per GB of HBM4 12hi may rise from about $2 in 2026 to a range of $4 to $5 in 2027, with HBM4 8hi commanding a 20% to 30% premium on top of that. Samsung's management also indicated in the Q2 earnings call that they expect HBM4 sales to triple in Q3 and account for over 60% of total HBM revenue in the second half of the year (according to the earnings call transcript).
The bullish logic is price elasticity, while the opposing question is the demand's bearing capacity. According to Morgan Stanley's estimates, global capital expenditure by cloud service providers may reach $1.2 trillion in 2027, with more than half flowing to storage; at the same time, the ratio of capital expenditure to EBITDA for Google, Amazon, Microsoft, and Meta has exceeded 70% in 2026, and for some companies, capital expenditure may exceed EBITDA in 2027. The pricing power of storage lies on the supply side, and the profits on the supply side ultimately come from the spending on the demand side. Once buyers' spending approaches or even exceeds their profitability, how far the price increase curve can extend depends on a balance sheet that Samsung cannot control.
5. Samsung's accounts are also the accounts of the entire AI hardware chain
Samsung's financial report contains two opposing facts. One is that the demand for HBM and DRAM from AI data centers is still exploding, and the tight supply-demand situation in storage may continue, with industry profit margins at historical highs; the other is that the same company's consumer electronics business is reducing production, raising prices, and incurring losses, with rising storage prices squeezing the profit margins at the end. These two facts are not coincidental; the latter is partly caused by the former: the more expensive the computing power, the harder it is to produce at the end. Similar pressures are being transmitted throughout the entire AI hardware industry chain, but the ways different links bear the pressure vary.
We believe that the interpretation of Samsung's stock price essentially reflects the market pricing for growth rates rather than profit levels: the level has already been realized, and the slope is part of the valuation. This interpretation has a premise and a counterexample. The premise is that the slope of cloud vendors' spending remains stable; if the capital expenditure guidance for 2027 shows a systematic downward revision, both the volume and price of storage will be under pressure; the counterexample is that if tighter guidance on long-term supply agreements and 2027 supply-demand outlook is provided at the earnings briefing on October 29, concerns about the slope may be temporarily alleviated. Whether profits are at the peak of this cycle cannot be confirmed in advance; only three answers can be verified on October 29: 2027 supply-demand, progress on long-term agreements, and details on capital expenditure and shareholder returns. To what extent this quarter's profits have already been factored into the price remains to be seen.
Data Explanation
Samsung's performance and departmental breakdown: Company announcements (2026/10/8, 7/30, 5/6).
Comparison of Q3 2025 and total operating profit for the year: Company disclosures, Yonhap News (2026/4/7, 7/7).
Samsung stock price and retreat: Public market data, as of the close on 2026/10/8; the peak on 6/18 was an intraday price.
Citigroup's viewpoint: Citigroup research report, media summary.
Morgan Stanley's viewpoint: Morgan Stanley's industry report from 2026/7/21, media summary.
Smartphone production cuts, shipments, and S26 pricing: South Korean media, TrendForce.
Profit margins of the three major memory manufacturers: Public reports from Chosun and others.
Disclaimer: The content of this article is for general information and market commentary only, compiled based on publicly available information as of the time mentioned in the text. Relevant market data, expectations, and probabilities may change with market conditions. The views and investment strategies of third-party institutions, analysts, or other individuals cited in the text only represent the views of the relevant third parties at a specific time and do not represent the views or recommendations of BIT. This article does not constitute investment advice, investment research, an offer, solicitation, or recommendation for any securities, investment products, or trading strategies, nor should it be the basis for any investment decision. Financial markets carry risks, and securities prices and market performance may fluctuate; past performance and historical market trends do not represent or guarantee future results. Investors should independently assess the relevant risks based on their own circumstances and seek professional advice when necessary.
 Risk warning


Popular articles